PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2120740

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2120740
Biosurfactants - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the biosurfactants market size is expected to increase from USD 3.01 billion in 2025 to USD 3.18 billion in 2026 and reach USD 4.16 billion by 2031, growing at a CAGR of 5.52% over 2026-2031.
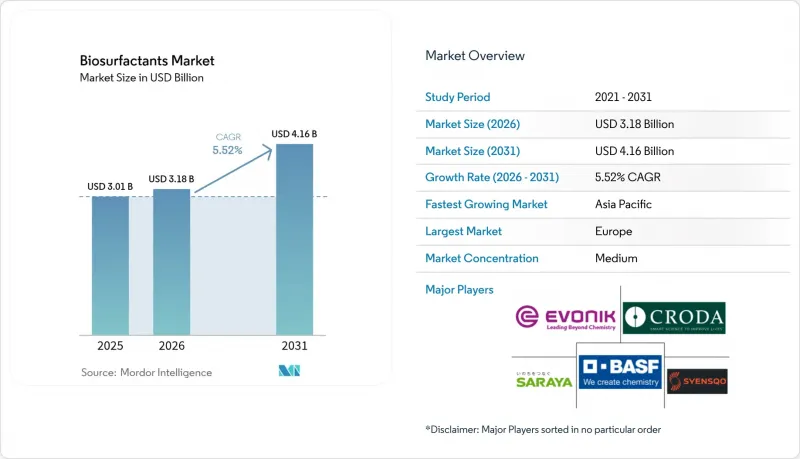
This report is Segmented by Product Type (Glycolipids, Phospholipids, Surfactin, Lichenysin, Polymeric Bio-Surfactants, and Other Product Types), Feedstock (Vegetable Oils, Industrial Waste Glycerol, Agricultural Residues, and Others), Application (Detergents and Industrial Cleaners, and More), and Geography (Asia-Pacific, North America, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Biosurfactants Market Trends and Insights
Expansion of Personal-Care and Cosmetics Demand in Asia-Pacific
In 2025, China's cosmetics expenditure surged, reaching significant levels. Domestic brands, keen on meeting "clean beauty" standards, began reformulating their cleansers with sophorolipids. Meanwhile, in India, personal-care sales saw an uptick, bolstered by Hindustan Unilever's glycolipid handwash, which gained market share just 90 days post its October 2025 launch. South Korea's regulatory body greenlit rhamnolipids for leave-on cosmetics in February 2025. This move paved the way for premium K-beauty serums, which boast high margins. Japanese exporters capitalized on rising demand from ASEAN, dispatching biosurfactant-infused products. This boost in exports propelled regional toiletries sales in 2025. In a strategic move, Croda inaugurated a joint venture in Shanghai in November 2025, establishing a glycolipid capacity to cater to this burgeoning consumer market.
Regulatory Push for Biodegradable Surfactants (EU, US)
Household products must now achieve 60% biodegradation within 28 days, as mandated by REACH Annex XVII. While rhamnolipids meet this requirement, many ethoxylates do not. In March 2025, the U.S. EPA included rhamnolipids and sophorolipids in its Safer Choice ingredient list. This endorsement provides detergents with a shelf-labeling advantage, which can boost purchase intent. Starting January 2025, California's Cleaning Product Right to Know Act will require brands to fully disclose ingredients, nudging them towards clearer, plant-based names. Meanwhile, European proposals to phase out PFAS are steering formulators more towards bio-based surfactants. Together, these initiatives bolster demand, even during economic downturns.
High Production Cost vs. Petro-Surfactants
Rhamnolipids still carry a surcharge over LAS. Downstream purification consumes a significant portion of the cash cost, with chromatography and spray-drying adding to the expenses. Margins face pressure from feedstock spikes, especially when glycerol or residues are in short supply. Despite the potential, achieving economies of scale proves challenging; the largest biosurfactant plants trail petrochemical units by a considerable factor.
Other drivers and restraints analyzed in the detailed report include:
- Brand-Level Sustainability Commitments by FMCG Majors
- Synthetic-Biology-Enabled Designer Biosurfactants
- Tight Purity Specs for Food and Pharma Grades
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
In 2025, glycolipids accounted for 68.91% of the revenue and are also advancing at a 5.81% CAGR through 2031. Their share of the biosurfactants market is poised to increase, thanks to rhamnolipids achieving critical micelle concentrations. Sophorolipids, bolstered by laundry liquids in Europe, commanded a notable portion of the glycolipid segment. Meanwhile, surfactin, capitalizing on its thermal stability, secured a share for oilfield and drilling fluid applications.
Regulatory approvals are driving increased adoption: In March 2025, Japan's PMDA approved sophorolipids for over-the-counter skincare, and the ECHA expedited the registration process for rhamnolipids following their pre-registration in 2024. Kaneka introduced high-purity grades for cosmetic serums, which command significant price premiums, underscoring a trend towards premiumization.
Complete Report Scope:
- By Product Type
- Glycolipids
- Phospholipids
- Surfactin
- Lichenysin
- Polymeric Bio-surfactants
- Other Product Types
- By Feedstock
- Vegetable Oils (soy, palm, rapeseed)
- Industrial Waste Glycerol
- Agricultural Residues (molasses, whey)
- Others (Animal Fat, Synthesised Sugars)
- By Application
- Detergents and Industrial Cleaners
- Cosmetics (Personal Care)
- Food Processing
- Oilfield Chemicals
- Agricultural Chemicals
- Textiles
- Other Applications
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- ASEAN
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Europe held 51.75% revenue in 2025 as REACH, driven by the convergence of REACH regulations, proposals for phasing out PFAS, and a growing consumer preference for ecolabeled detergents. Germany, the United Kingdom, and France collectively accounted for the region's consumption, primarily sourcing from the multi-modal hubs of Evonik and BASF. Additionally, carbon-intensity disclosures mandated by the Corporate Sustainability Reporting Directive are pushing retailers to increasingly stock private labels based on biosurfactants.
North America, contributing significantly to the turnover, benefited from EPA's Safer Choice designations, which facilitate prominent shelf-edge callouts. Procter & Gamble's swift expansion into renewable surfactants, coupled with Colgate-Palmolive's introduction of sophorolipids in the U.S. and Mexico, heightened the demand for sourcing. Furthermore, Canada's EcoLogo endorsement has carved out niche contracts within the institutional cleaning supplies sector.
Asia-Pacific will post the fastest 6.04% run-rate to 2031. This surge is fueled by China's staggering appetite for cosmetics and India's robust growth in personal care. Japan's endorsement of rhamnolipids for premium leave-on products, alongside Korea's flourishing export channel to ASEAN markets, bolsters regional consumption. Addressing supply security, a Croda-Shanghai joint venture is poised to commence operations in 2027, boasting a significant capacity.
South America and the combined regions of the Middle East and Africa hold a modest share. Their growth is tempered by price sensitivity, yet they are gaining traction, especially in areas abundant with crude glycerol and where oilfield applications are prevalent. Brazil's biodiesel initiative churns out an impressive amount of glycerol annually. This bounty serves as an economical fermentation feed for domestic producers. Meanwhile, in alignment with its Vision 2030 objectives, Saudi Aramco is experimenting with biosurfactant drilling fluids.
- AGAE Technologies, LLC
- AmphiStar Biosurfactants
- BASF
- Biotensidon GmbH
- Croda International Plc
- Dispersa Inc.
- Ecover
- Evonik Industries AG
- Givaudan
- GlycoSurf
- Jeneil Biotech
- Kaneka Corporation
- Saraya.Co.Ltd
- Stepan Company
- Syensqo
- TeeGene Biotech
- TensioGreen
- WHEATOLEO
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Expansion of Personal-Care and Cosmetics Demand in Asia-Pacific
- 4.2.2 Regulatory Push for Biodegradable Surfactants (EU, US)
- 4.2.3 Brand-Level Sustainability Commitments by FMCG Majors
- 4.2.4 Fermentation Scale-Up Lowering Cost Curves
- 4.2.5 Synthetic-Biology-Enabled "Designer" Biosurfactants
- 4.3 Market Restraints
- 4.3.1 High Production Cost vs. Petro-Surfactants
- 4.3.2 Tight Purity Specs for Food and Pharma Grades
- 4.3.3 Patent Thickets around Production Strains
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Product Type
- 5.1.1 Glycolipids
- 5.1.2 Phospholipids
- 5.1.3 Surfactin
- 5.1.4 Lichenysin
- 5.1.5 Polymeric Bio-surfactants
- 5.1.6 Other Product Types
- 5.2 By Feedstock
- 5.2.1 Vegetable Oils (soy, palm, rapeseed)
- 5.2.2 Industrial Waste Glycerol
- 5.2.3 Agricultural Residues (molasses, whey)
- 5.2.4 Others (Animal Fat, Synthesised Sugars)
- 5.3 By Application
- 5.3.1 Detergents and Industrial Cleaners
- 5.3.2 Cosmetics (Personal Care)
- 5.3.3 Food Processing
- 5.3.4 Oilfield Chemicals
- 5.3.5 Agricultural Chemicals
- 5.3.6 Textiles
- 5.3.7 Other Applications
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 ASEAN
- 5.4.1.6 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Spain
- 5.4.3.6 Russia
- 5.4.3.7 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle-East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle-East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials, Strategic Information, Products and Services, Recent Developments)
- 6.4.1 AGAE Technologies, LLC
- 6.4.2 AmphiStar Biosurfactants
- 6.4.3 BASF
- 6.4.4 Biotensidon GmbH
- 6.4.5 Croda International Plc
- 6.4.6 Dispersa Inc.
- 6.4.7 Ecover
- 6.4.8 Evonik Industries AG
- 6.4.9 Givaudan
- 6.4.10 GlycoSurf
- 6.4.11 Jeneil Biotech
- 6.4.12 Kaneka Corporation
- 6.4.13 Saraya.Co.Ltd
- 6.4.14 Stepan Company
- 6.4.15 Syensqo
- 6.4.16 TeeGene Biotech
- 6.4.17 TensioGreen
- 6.4.18 WHEATOLEO
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment

