PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2121229

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2121229
Bioinformatics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the bioinformatics market size is estimated at USD 19.97 billion in 2026, and is expected to reach USD 37.03 billion by 2031, at a CAGR of 13.10% during the forecast period (2026-2031).
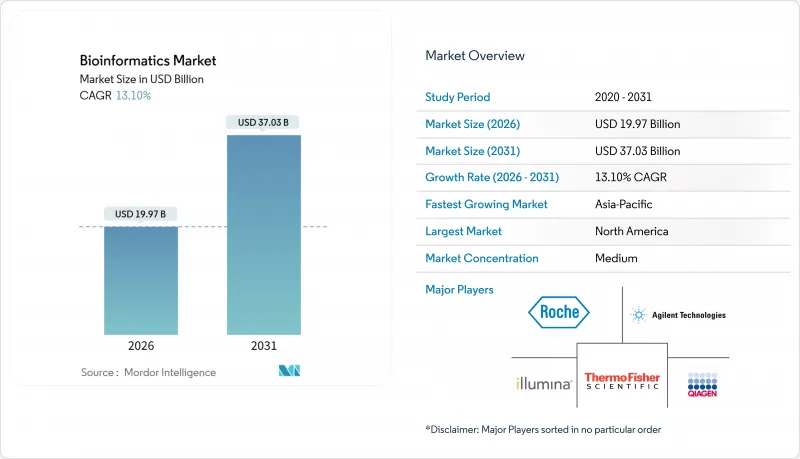
This report is Segmented by Products and Services (Knowledge Management Tools, Bioinformatics Platforms, Bioinformatics Services), Application (Genomics & Transcriptomics, Proteomics & Metabolomics, and More), End-User (Pharmaceutical & Biotechnology Companies, Academic & Research Institutes, and More), and Geography (North America, Europe, Asia-Pacific, and More). Market Forecasts are in Value (USD).
Global Bioinformatics Market Trends and Insights
Explosion of Multi-Omics Data Volumes
Sequencing throughput has surpassed 20 petabases per instrument per year, yet storage and compute infrastructure trail demand, creating bottlenecks that bioinformatics platforms must resolve. The cost to sequence a human genome fell below USD 200 in 2024, but downstream analysis now costs three to five times that amount, driving investment in compression algorithms and federated learning that process data in situ. Pharmaceutical sponsors increasingly integrate genomic, transcriptomic, proteomic, and metabolomic datasets from identical patient cohorts, a workflow that depends on GPU clusters and object storage optimized for petabyte-scale workloads. Cloud providers such as AWS, Google Cloud, and Microsoft Azure are responding with managed pipelines that accelerate variant calling and annotation. Edge appliances embedded inside sequencers further minimize data-transfer fees by handling base-calling and primary analysis locally. Together, these dynamics sustain double-digit spending on elastic compute even as per-sample sequencing costs decline.
Precision Medicine and Companion Diagnostics Adoption
Regulatory approvals for companion diagnostics rose in 2025 as compared to 2024, owing to reinforcing the need for pipelines that detect complex genomic alterations with clinical-grade accuracy. Tumor-agnostic therapies targeting NTRK fusions and MSI-high signatures require panels interrogating more than 300 genes, shifting demand from single-gene assays toward comprehensive profiling. The European Medicines Agency finalized guidance in 2024 that obligates analytical validation across diverse ethnic cohorts, prompting expansion of reference datasets and ethnicity-aware algorithms. Japan added reimbursement codes for liquid biopsy monitoring in 2025, catalyzing the uptake of tools that track circulating tumor-DNA dynamics. Collectively, these policies anchor bioinformatics spending in oncology, yet spill into cardiology and rare disease as payers recognize the pharmacoeconomic value of stratified therapeutics.
Shortage of Skilled Bioinformaticians
Academic programs graduated roughly 8,500 computational biologists in 2025, versus industrial demand for more than 15,000 new hires, widening a talent gap that inflates salaries past USD 150,000 for mid-career professionals . Companies launch in-house training to upskill molecular biologists in Python and R, while platform vendors embed no-code interfaces to widen usability. Offshore talent pools in India and Eastern Europe offer partial relief, though time-zone and data-sovereignty constraints restrict protected-health-information workflows.
Other drivers and restraints analyzed in the detailed report include:
- Pharma-Biotech Shift Toward Data-Centric R&D
- Government-Funded Genomic Initiatives
- Cybersecurity and Genomic-Data Privacy Risks
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Platforms accounted for 48.1% of the bioinformatics market in 2025, driven by tightly coupled sequence analysis workflows with Illumina and Oxford Nanopore instruments. Within this category, consumption-based cloud deployment is winning share as laboratories migrate away from depreciating on-premise clusters. Services grow at a 14.1% CAGR through 2031 by translating capital expenditure into variable operating expense and bundling compliance frameworks that satisfy CLIA and CE-IVDR requirements. Sequence analysis remains core, yet multi-omics integration and knowledge-management modules now bundle graph databases and text-mining engines that surface pathway insights faster than manual curation. Platform vendors that cannot deliver both cloud and edge codebases face consolidation pressure, as evidenced by recent mid-tier mergers.
Bioinformatics services capture expanding wallet share from small biotech and academic labs that lack internal computational teams. Hyperscalers amplify this trend by embedding genomics toolkits-AWS HealthOmics, Google Cloud Life Sciences API-into broader cloud offerings, often priced below cost to drive storage and compute consumption. As a result, the bioinformatics market size attributable to standalone software licenses is declining even though overall spend rises. Subscription and per-sample fees replace one-time hardware revenue, aligning vendor incentives with customer data volumes. Knowledge-management tools still monetize curation quality, yet open-access resources erode their pricing power, shifting emphasis toward proprietary algorithms that integrate with electronic lab notebooks and laboratory-information systems.
Complete Report Scope:
- By Products & Services
- Knowledge Management Tools
- Bioinformatics Platforms
- Sequence Analysis Platforms
- Sequence Alignment Platforms
- Sequence Manipulation Platforms
- Structural & Functional Analysis Platforms
- Multi-omics Integration Platforms
- Bioinformatics Services
- Sequencing & Data-Generation Services
- Database Construction & Management
- Data Analysis & Interpretation Services
- Cloud-native Bioinformatics-as-a-Service
- By Application
- Genomics & Transcriptomics
- Proteomics & Metabolomics
- Drug Discovery & Development
- Microbial Genomics (Metagenomics & AMR)
- Precision & Personalized Medicine
- Other Applications
- By End-user
- Pharmaceutical & Biotechnology Companies
- Academic & Research Institutes
- Clinical & Diagnostic Laboratories
- Contract Research Organizations (CROs)
- Other End-Users
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America commanded 39.4% of the bioinformatics market in 2025, backed by a dense cluster of pharmaceutical headquarters, academic centers, and venture funding. FDA guidance published in 2024 tightened clinical validity standards for next-generation sequencing tests, extending development cycles yet raising overall data-analysis complexity. Canada's precision-oncology networks deploy federated platforms that comply with provincial privacy acts, and Mexico's biosimilar producers adopt bioinformatics tools for comparability protocols, diversifying regional demand.
The Asia-Pacific region is forecast to expand at a 14.89% CAGR through 2031 as China's state-sponsored genomics ecosystem scales sequencing capacity and vertically integrates analytics platform India incubates start-ups that localize pipelines for South-Asian haplotypes, and Japan broadens reimbursement for 500-plus-gene panels, pushing hospital adoption of clinical-grade software. Australia and South Korea invest in national precision-medicine programs that couple cloud computing with sovereign data centers, ensuring compliance with domestic cybersecurity statutes.
Europe's In Vitro Diagnostic Regulation, enforceable from 2024, obliges software used in diagnostics to obtain CE-IVDR certification, increasing vendor compliance costs. Germany's National Genome Center centralizes rare-disease workflows, while the United Kingdom integrates whole-genome sequencing into the National Health Service, mandating turnaround times of less than 14 days. South America's market centers on Brazil's pharmacogenomics pilots and Argentina's crop genomics programs, whereas the Middle East and Africa remain nascent, with the United Arab Emirates and Saudi Arabia funding large-scale sequencing as part of their economic diversification agendas.
- 3rd Millennium
- Agilent Technologies
- BGI Genomics Co. Ltd.
- Dassault Systemes SE (BIOVIA)
- Data4Cure Inc.
- DNAnexus Inc.
- Eagle Genomics Ltd.
- Roche
- Gene42 Inc.
- Genedata
- Geneious (Biomatters)
- Illumina
- Ontoforce NV
- Oracle Corporation (Oracle Healthcare)
- Partek Inc.
- PerkinElmer
- QIAGEN
- Seven Bridges Genomics Inc.
- SoftGenetics LLC
- Thermo Fisher Scientific
- WuXi NextCODE Genomics
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Explosion Of Multi-Omics Data Volumes
- 4.2.2 Precision Medicine & Companion Diagnostics Adoption
- 4.2.3 Pharma-Biotech Shift Toward Data-Centric R&D
- 4.2.4 Government-Funded Genomic Initiatives
- 4.2.5 Edge/Near-Instrument Bioinformatics Processing
- 4.2.6 AI Model-Marketplaces Enabling Plug-And-Play Analytics
- 4.3 Market Restraints
- 4.3.1 Shortage of Skilled Bioinformaticians
- 4.3.2 Fragmented Data Standards
- 4.3.3 Cyber-Security & Genomic-Data Privacy Risks
- 4.3.4 Rising Cloud Egress & Long-Term Storage Costs
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Products & Services
- 5.1.1 Knowledge Management Tools
- 5.1.2 Bioinformatics Platforms
- 5.1.2.1 Sequence Analysis Platforms
- 5.1.2.2 Sequence Alignment Platforms
- 5.1.2.3 Sequence Manipulation Platforms
- 5.1.2.4 Structural & Functional Analysis Platforms
- 5.1.2.5 Multi-omics Integration Platforms
- 5.1.3 Bioinformatics Services
- 5.1.3.1 Sequencing & Data-Generation Services
- 5.1.3.2 Database Construction & Management
- 5.1.3.3 Data Analysis & Interpretation Services
- 5.1.3.4 Cloud-native Bioinformatics-as-a-Service
- 5.2 By Application
- 5.2.1 Genomics & Transcriptomics
- 5.2.2 Proteomics & Metabolomics
- 5.2.3 Drug Discovery & Development
- 5.2.4 Microbial Genomics (Metagenomics & AMR)
- 5.2.5 Precision & Personalized Medicine
- 5.2.6 Other Applications
- 5.3 By End-user
- 5.3.1 Pharmaceutical & Biotechnology Companies
- 5.3.2 Academic & Research Institutes
- 5.3.3 Clinical & Diagnostic Laboratories
- 5.3.4 Contract Research Organizations (CROs)
- 5.3.5 Other End-Users
- 5.4 Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 Japan
- 5.4.3.3 India
- 5.4.3.4 South Korea
- 5.4.3.5 Australia
- 5.4.3.6 Rest of Asia-Pacific
- 5.4.4 Middle East and Africa
- 5.4.4.1 GCC
- 5.4.4.2 South Africa
- 5.4.4.3 Rest of Middle East and Africa
- 5.4.5 South America
- 5.4.5.1 Brazil
- 5.4.5.2 Argentina
- 5.4.5.3 Rest of South America
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 3rd Millennium Inc.
- 6.3.2 Agilent Technologies Inc.
- 6.3.3 BGI Genomics Co. Ltd.
- 6.3.4 Dassault Systemes SE (BIOVIA)
- 6.3.5 Data4Cure Inc.
- 6.3.6 DNAnexus Inc.
- 6.3.7 Eagle Genomics Ltd.
- 6.3.8 F. Hoffmann-La Roche Ltd.
- 6.3.9 Gene42 Inc.
- 6.3.10 Genedata AG
- 6.3.11 Geneious (Biomatters)
- 6.3.12 Illumina Inc.
- 6.3.13 Ontoforce NV
- 6.3.14 Oracle Corporation (Oracle Healthcare)
- 6.3.15 Partek Inc.
- 6.3.16 PerkinElmer Inc.
- 6.3.17 Qiagen N.V.
- 6.3.18 Seven Bridges Genomics Inc.
- 6.3.19 SoftGenetics LLC
- 6.3.20 Thermo Fisher Scientific Inc.
- 6.3.21 WuXi NextCODE Genomics
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment

