PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2121276

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2121276
Sterilized Packaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, sterilized packaging market size in 2026 is estimated at USD 81.61 billion, growing from 2025 value of USD 75.93 billion with 2031 projections showing USD 117.18 billion, growing at 7.48% CAGR over 2026-2031.
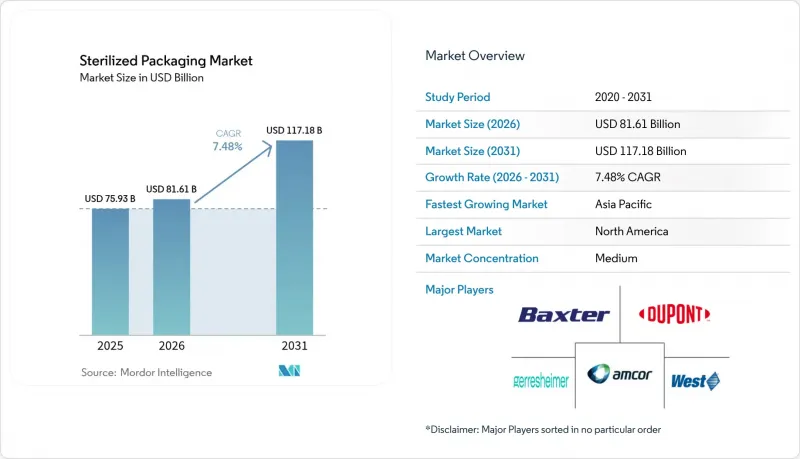
This report is Segmented by Product (Clamshells, Pouches, Bottles, Blisters and Ampoules, Vials, and More), Material (Plastics, Glass, Metals, and More), Sterilization Method (Chemical, Radiation, and More), End-User Industry (Medical and Surgical Instruments, Pharmaceutical and Biological, In-Vitro Diagnostics, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Sterilized Packaging Market Trends and Insights
Rising Incidence of Hospital-Acquired Infections
Healthcare-associated infections affect 1 in 31 U.S. hospital patients on any day, costing the system USD 28.4 billion annually. Hospitals are therefore mandating higher barrier trays and sterile wraps for critical instruments, and many facilities are shifting reusable sets to single-use formats to mitigate liability. Single-use sterilized packaging market demand rises further as antibiotic-resistant organisms render legacy cleaning inadequate. Packaging converters report growing orders for breathable Tyvek lids that withstand multiple EtO cycles while maintaining a sterility assurance level of 10-6.
Growth in Biologics and Injectable Drugs
Global biologics revenue is moving toward USD 856 billion by 2030, and demand for injectable formats requires ultra-clean containers that do not shed particulates. The prefilled syringe boom is compelling suppliers to certify tougher container-closure tests, while cell-therapy producers need packs that hold integrity at -196 °C. SCHOTT Pharma's USD 371 million U.S. syringe plant targets these therapies and shows how regional capacity expansion aligns with tighter Annex 1 rules.
Volatile Medical-Grade Polymer Prices
Medical-grade resins require specialty additives and lengthy validation, limiting supplier substitution. Geopolitical disruptions and refinery outages have spiked prices, squeezing converters that already face costly EtO abatement projects. Firms with multi-region supply contracts and in-house recycling capacity have more margin cover, whereas single-source buyers risk shortages and expedited-freight expenses.
Other drivers and restraints analyzed in the detailed report include:
- Stringent Global Sterilization Regulations
- Expansion of Outpatient and Home-Care Settings
- Cost of Ethylene Oxide Emission Compliance
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Trays and thermoform packs retained a 26.21% share of the sterilized packaging market in 2025 thanks to their ability to nest complex instrument sets and provide instant visual confirmation. Hospitals value clear lids that speed count-in and count-out procedures, reducing operating-room delays. Custom cavities lower product movement, cutting puncture risk in transit. Blisters and ampoules represent the fastest-rising product at a 9.02% CAGR through 2031, supported by unit-dose biologics where contamination can destroy high-value doses.
The push toward advanced barrier films within blisters illustrates premiumization. AI-equipped cameras on thermoform lines inspect seal integrity at full speed, improving batch yield and documentation. Pouches, bottles, IV containers, and clamshells remain relevant for specific dosage forms and reusable instruments, but growth is slower as unit-dose formats gain traction. Smart labels that log temperature or radiation exposure are migrating from trial to scale, reflecting broader digitization.
Plastics still accounted for 61.58% of sterilized packaging market size in 2025 because they balance strength, clarity, and cost. Polyethylene, polypropylene, and cyclic-olefin copolymers withstand EtO, gamma, and e-beam, yet rising sustainability rules and virgin-resin inflation encourage substitution. Non-woven and Tyvek substrates are forecast to rise 9.11% CAGR to 2031 as breathability and fiber strength help them pair with lower-residue sterilants.
Glass vials remain indispensable where drug-product interaction must approach zero, notably for biologics with long cold-chain legs. Metal trays occupy smaller niches such as orthopedic implant kits requiring rigid retention and shielded transport. Paperboard is gaining for secondary cartons where biodegradability is prized, though primary sterility still relies on higher barriers. As PFAS sunset dates approach, suppliers scale up plasma and silicon-oxide coatings to replace fluoropolymers.
Complete Report Scope:
- By Product
- Clamshells
- Pouches
- Bottles
- Blisters and Ampoules
- Vials
- Trays and Thermoform Packs
- IV Containers and Bags
- Others
- By Material
- Plastics (HDPE, PP, PET, PVC, Others)
- Glass
- Metals (Aluminum Foil, Stainless Steel)
- Paper and Paperboard
- Non-woven and Tyvek
- By Sterilization Method
- Chemical (EtO, Ozone)
- Radiation (Gamma, e-Beam, X-Ray)
- High Temperature / Steam
- Aseptic Fill-Finish
- By End-user Industry
- Medical and Surgical Instruments
- Pharmaceutical and Biological
- In-Vitro Diagnostics
- Food and Beverage
- Veterinary and Animal Health
- Other Industrial
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia and New Zealand
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Egypt
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America held 32.84% of sterilized packaging market share in 2025, anchored by FDA oversight and a high proportion of complex drug launches. Large contract sterilization networks and leading resin producers underpin supply security, while investment focuses on EtO abatement and new e-beam vaults. Becton Dickinson's biologic-delivery segment surpassed USD 1 billion in 2024, highlighting the region's tilt toward higher-value devices .
Europe follows with mature demand, driven by Annex 1 upgrades and early adoption of PFAS-free materials. Germany and Ireland host numerous fill-finish plants that feed global biologic supply chains. The EU's 2026 fluoropolymer limits spur rapid qualification of alternative coatings, positioning European converters as first movers. Sustainability targets also push circular-economy pilots for reusable secondary packs.
Asia-Pacific posts the fastest 8.95% CAGR to 2031 as China and India scale biologic and small-molecule output for domestic and export markets. Regional regulators are harmonizing with ICH guidelines, prompting investment in higher-grade cleanrooms and radiation capacity. Japan's aging population drives home-care syringe demand, while South Korea and Australia serve as test beds for smart-label cold-chain packs. Localizing sterilized packaging market capacity cuts lead times and cushions currency risk.
- Amcor plc
- DuPont de Nemours, Inc.
- Baxter International Inc.
- Gerresheimer AG
- SCHOTT AG
- West Pharmaceutical Services, Inc.
- AptarGroup, Inc.
- Tekni-Plex, Inc.
- Sealed Air Corporation
- Sonoco Products Company
- SteriPack Group
- Wipak Group
- Placon Corporation, Inc.
- SGD Pharma
- Becton, Dickinson and Company
- 3M Company
- Berry Global Group, Inc.
- Huhtamaki Oyj
- Sabert Corporation
- Winpak Ltd.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Market Definition and Study Assumptions
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising incidence of hospital-acquired infections
- 4.2.2 Growth in biologics and injectable drugs
- 4.2.3 Stringent global sterilization regulations
- 4.2.4 Expansion of outpatient and home-care settings
- 4.2.5 AI-enabled inline sterile-pack inspection
- 4.2.6 Cell and gene-therapy cold-chain needs
- 4.3 Market Restraints
- 4.3.1 Volatile medical-grade polymer prices
- 4.3.2 Cost of ethylene oxide (EtO) emission compliance
- 4.3.3 Limited pharma-grade gamma irradiation capacity
- 4.3.4 PFAS scrutiny in fluoropolymer barrier films
- 4.4 Value / Supply-Chain Analysis
- 4.5 Evaluation of Critical Regulatory Framework
- 4.6 Impact Assessment of Key Stakeholders
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Bargaining Power of Suppliers
- 4.8.2 Bargaining Power of Consumers
- 4.8.3 Threat of New Entrants
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
- 4.9 Impact of Macro-economic Factors
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product
- 5.1.1 Clamshells
- 5.1.2 Pouches
- 5.1.3 Bottles
- 5.1.4 Blisters and Ampoules
- 5.1.5 Vials
- 5.1.6 Trays and Thermoform Packs
- 5.1.7 IV Containers and Bags
- 5.1.8 Others
- 5.2 By Material
- 5.2.1 Plastics (HDPE, PP, PET, PVC, Others)
- 5.2.2 Glass
- 5.2.3 Metals (Aluminum Foil, Stainless Steel)
- 5.2.4 Paper and Paperboard
- 5.2.5 Non-woven and Tyvek
- 5.3 By Sterilization Method
- 5.3.1 Chemical (EtO, Ozone)
- 5.3.2 Radiation (Gamma, e-Beam, X-Ray)
- 5.3.3 High Temperature / Steam
- 5.3.4 Aseptic Fill-Finish
- 5.4 By End-user Industry
- 5.4.1 Medical and Surgical Instruments
- 5.4.2 Pharmaceutical and Biological
- 5.4.3 In-Vitro Diagnostics
- 5.4.4 Food and Beverage
- 5.4.5 Veterinary and Animal Health
- 5.4.6 Other Industrial
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Russia
- 5.5.3.7 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Australia and New Zealand
- 5.5.4.6 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Nigeria
- 5.5.5.2.3 Egypt
- 5.5.5.2.4 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Amcor plc
- 6.4.2 DuPont de Nemours, Inc.
- 6.4.3 Baxter International Inc.
- 6.4.4 Gerresheimer AG
- 6.4.5 SCHOTT AG
- 6.4.6 West Pharmaceutical Services, Inc.
- 6.4.7 AptarGroup, Inc.
- 6.4.8 Tekni-Plex, Inc.
- 6.4.9 Sealed Air Corporation
- 6.4.10 Sonoco Products Company
- 6.4.11 SteriPack Group
- 6.4.12 Wipak Group
- 6.4.13 Placon Corporation, Inc.
- 6.4.14 SGD Pharma
- 6.4.15 Becton, Dickinson and Company
- 6.4.16 3M Company
- 6.4.17 Berry Global Group, Inc.
- 6.4.18 Huhtamaki Oyj
- 6.4.19 Sabert Corporation
- 6.4.20 Winpak Ltd.
7 MARKET OPPORTUNITIES AND FUTURE TRENDS
- 7.1 White-space and Unmet-need Assessment

