PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2121317

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2121317
Lyophilization Equipment And Services - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the lyophilization equipment and services market size is estimated at USD 5.18 billion in 2026, and is expected to reach USD 8.25 billion by 2031, at a CAGR of 9.76% during the forecast period (2026-2031).
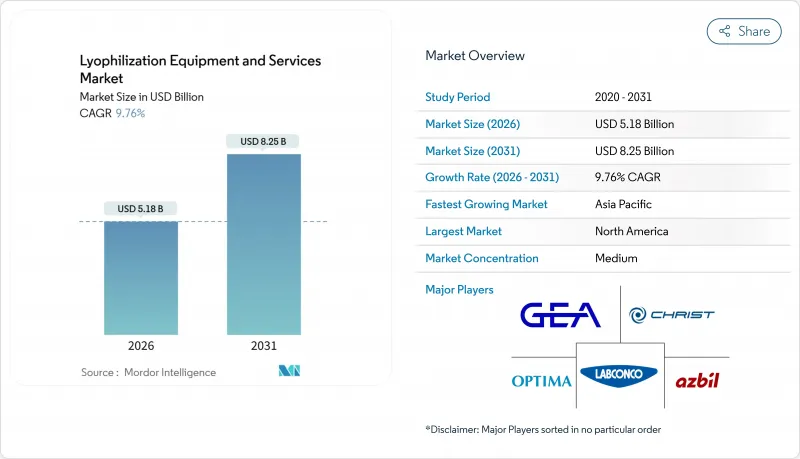
This report is Segmented by Modality (Dryer Type, Accessories, and Services), Application (Pharmaceutical & Biotech Manufacturing, Food Processing & Packaging, Medical & Diagnostics, and More), and Geography (North America, Europe, Asia-Pacific, Middle East & Africa, South America). The Market Forecasts are Provided in Terms of Value (USD).
Global Lyophilization Equipment And Services Market Trends and Insights
Rising Demand for Lyophilized Biologics & Injectables
Monoclonal antibodies, vaccines, and antibody-drug conjugates accounted for 68% of FDA biologics approvals in 2025, and most relied on freeze-drying to ensure multi-year room-temperature stability. Patent expiries accelerated biosimilar launches: Trastuzumab biosimilar Bisintex gained European approval in December 2024, and adalimumab biosimilars captured a 42% U.S. share by mid-2025, each emulating the originator's stability with lyophilized vials. Next-generation allogeneic CAR-T platforms are evaluating dry formats to avoid liquid-nitrogen logistics, potentially expanding required capacity by 15%-20% if commercialized at scale. Moderna disclosed pilot sugar-glass drying for mRNA vaccines in its 2024 10-K, signaling that nucleic-acid modalities may also pivot to freeze-drying. These pipelines directly swell order books for the lyophilization equipment and services market.
Expansion of Contract Lyophilization Capacity
CDMOs have outpaced in-house investments three-to-one since 2024, a pattern underscored by Samsung Biologics' Plant 5 build in Incheon and Lonza's eight-dryer expansion at Visp in 2025. Vetter's EUR 150 million project in Ravensburg added a high-speed line for pre-filled syringes, which command premium prices because aseptic freeze-drying prevents moisture ingress. Outsourcing eases capital burdens for start-ups yet concentrates know-how within a handful of service providers, reinforcing end-to-end offerings that now underpin a sizable share of the lyophilization equipment and services market.
High Capital & Maintenance Costs of Freeze-Dryers
A 100 m2 industrial tray dryer lists at USD 3 million to USD 5 million, and maintenance contracts consume up to 12% of the capital cost annually. Facility integration can add 30% due to HVAC and clean-room retrofits, as demonstrated by a 2024 Charleston project that spent USD 1.2 million on a single installation. Import tariffs of 15%-25% in India and Brazil elevate landed prices. At the same time, sparse local service networks increase downtime, prompting small firms to turn to CDMOs and limiting direct purchases in the lyophilization equipment and services market.
Other drivers and restraints analyzed in the detailed report include:
- Advances in High-Capacity Continuous & Microwave-Assisted Freeze-Drying
- Cold-Chain-Independent Vaccine Distribution Initiatives
- Adoption of Alternative Drying Methods
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Services generated the fastest growth in 2026 and are on track to post a 10.29% CAGR to 2031 as sponsors reallocate budgets from ownership to per-batch outsourcing. Accessories accounted for 39.28% of revenue in 2025, driven by a sizable installed base that requires vacuum pumps, SIP/CIP modules, and control upgrades. Lonza charges USD 150,000-USD 250,000 to validate a freeze-drying cycle, which is far less than the USD 3 million-USD 5 million required for an in-house dryer, encouraging smaller clients to outsource. CDMOs operating three dryers at 90% utilization achieve vial costs 40%-50% lower than single-dryer plants running at 60%, a structural advantage that expands the lyophilization equipment and services market through service revenues.
Tray-style systems retain the majority of equipment sales due to their flexibility across vial formats, while manifold units focus on personalized medicine. Rotary dryers claim premium niches where 10%-15% faster cycles offset 30% higher prices. Accessories demand remains linked to Process Analytical Technology (PAT) retrofits; adding tunable diode laser sensors can cut cycle development time by 30% and deliver a payback within two years for high-volume users.
Complete Report Scope:
- By Modality
- Dryer Type
- Tray-style Freeze Dryers
- Manifold Freeze Dryers
- Rotary Freeze Dryers
- Vacuum Freeze Dryers
- Accessories
- Vacuum Systems
- CIP / SIP Systems
- Loading & Unloading Systems
- Control & Monitoring Modules
- Services
- Process & Cycle Development
- Contract Manufacturing / Bulk Lyophilization
- Maintenance & Validation
- Dryer Type
- By Application
- Pharmaceutical & Biotech Manufacturing
- Food Processing & Packaging
- Medical & Diagnostics
- Other Applications
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America generated 36.86% of global revenue in 2025, driven by over 2,000 industrial dryers operating under FDA regulations. PCI Pharma Services completed a USD 100 million expansion of its New Hampshire plant in 2024, adding 12 dryers. Expansion at Charleston brought four additional units online. Although high labor and electricity costs temper new purchases, frequent retrofits for PAT compliance keep accessories and services buoyant. Canada's smaller base and Mexico's early-stage biosimilar capacity add incremental volume, with Lonza studying a Monterrey site for near-shored manufacturing in 2025.
The Asia-Pacific region is the fastest-growing, projected to post a 13.19% CAGR through 2031. WuXi Biologics commissioned three new suites in 2024 to serve export clients, leveraging 40%-50% lower production costs. The Serum Institute and Biological E each expanded their lines to supply thermostable vaccines, underscoring the pull of vaccine manufacturing on the lyophilization equipment and services market. Tofflon boosted exports by 47% in 2025 by pricing tray dryers 25%-30% below those of its Western peers, although limited FDA penetration persists. Australia and South Korea contribute modestly, while operator-skill gaps across China and India constrain ramp-ups, underscoring the demand for validated, turnkey capacity.
Europe maintained roughly 28% of revenue in 2025, led by Germany, Italy, France, the United Kingdom, and Spain. Industrial electricity prices in Germany averaged EUR 0.22 per kWh in 2025, nearly triple the U.S. rates, eroding the economics for energy-intensive dryers. Compliance with the EU's F-gas cuts incurs retrofit costs, yet major CDMOs remain committed. For instance, Recipharm invested EUR 3.7 million in Italy in 2024, and Vetter spent EUR 150 million in Ravensburg the same year. Nonetheless, European equipment shipments slipped 6% in 2025 as some projects migrated to lower-cost Asia-Pacific hubs.
South America and Middle East & Africa together form a sub-scale share below 15%, driven by Brazil's pharmaceutical investments and South Africa's vaccine ambitions. Infrastructure gaps and import duties dampen growth, though Gavi-funded vaccine rollouts could spur incremental demand, extending the global footprint of the lyophilization equipment and services market.
- Azbil
- Biopharma Process Systems
- Buchi Labortechnik
- Cryotec FR
- Cuddon Freeze Dry
- GEA Group
- Harvest Right
- HOF Sonderanlagenbau
- IMA S.p.A.
- Labconco
- Lyophilization Technology Inc.
- Martin Christ Gefriertrocknungsanlagen
- Millrock Technology
- Optima Packaging Group Gmbh
- Scala Scientific
- SP Industries (ATS)
- Thermo Fisher Scientific
- Tofflon Science & Technology
- Vikumer Freeze Dry
- ZIRBUS Technology
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Demand for Lyophilized Biologics & Injectables
- 4.2.2 Expansion of Contract Lyophilization (CMO/CDMO) Capacity
- 4.2.3 Advances In High-Capacity Continuous & Microwave-Assisted Freeze-Drying
- 4.2.4 Cold-Chain-Independent Vaccine Distribution Initiatives
- 4.2.5 Sustainability Incentives for Energy-Efficient Lyophilizers
- 4.2.6 Personalised-Medicine Micro-Batch Requirements
- 4.3 Market Restraints
- 4.3.1 High Capital & Maintenance Costs of Freeze-Dryers
- 4.3.2 Adoption of Alternative Drying Methods
- 4.3.3 Tightening Fluorinated-Refrigerant Regulations
- 4.3.4 Shortage of PAT-Skilled Freeze-Drying Operators
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitutes
- 4.6.5 Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Modality
- 5.1.1 Dryer Type
- 5.1.1.1 Tray-style Freeze Dryers
- 5.1.1.2 Manifold Freeze Dryers
- 5.1.1.3 Rotary Freeze Dryers
- 5.1.1.4 Vacuum Freeze Dryers
- 5.1.2 Accessories
- 5.1.2.1 Vacuum Systems
- 5.1.2.2 CIP / SIP Systems
- 5.1.2.3 Loading & Unloading Systems
- 5.1.2.4 Control & Monitoring Modules
- 5.1.3 Services
- 5.1.3.1 Process & Cycle Development
- 5.1.3.2 Contract Manufacturing / Bulk Lyophilization
- 5.1.3.3 Maintenance & Validation
- 5.1.1 Dryer Type
- 5.2 By Application
- 5.2.1 Pharmaceutical & Biotech Manufacturing
- 5.2.2 Food Processing & Packaging
- 5.2.3 Medical & Diagnostics
- 5.2.4 Other Applications
- 5.3 By Geography
- 5.3.1 North America
- 5.3.1.1 United States
- 5.3.1.2 Canada
- 5.3.1.3 Mexico
- 5.3.2 Europe
- 5.3.2.1 Germany
- 5.3.2.2 United Kingdom
- 5.3.2.3 France
- 5.3.2.4 Italy
- 5.3.2.5 Spain
- 5.3.2.6 Rest of Europe
- 5.3.3 Asia-Pacific
- 5.3.3.1 China
- 5.3.3.2 Japan
- 5.3.3.3 India
- 5.3.3.4 Australia
- 5.3.3.5 South Korea
- 5.3.3.6 Rest of Asia-Pacific
- 5.3.4 Middle East & Africa
- 5.3.4.1 GCC
- 5.3.4.2 South Africa
- 5.3.4.3 Rest of Middle East & Africa
- 5.3.5 South America
- 5.3.5.1 Brazil
- 5.3.5.2 Argentina
- 5.3.5.3 Rest of South America
- 5.3.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market-level Overview, Core Segments, Financials, Strategic Information, Market Rank/Share, Products & Services, Recent Developments)
- 6.3.1 Azbil Corporation
- 6.3.2 Biopharma Process Systems
- 6.3.3 Buchi Labortechnik
- 6.3.4 Cryotec FR
- 6.3.5 Cuddon Freeze Dry
- 6.3.6 GEA Group Aktiengesellschaft
- 6.3.7 Harvest Right
- 6.3.8 HOF Sonderanlagenbau
- 6.3.9 IMA S.p.A.
- 6.3.10 Labconco Corporation
- 6.3.11 Lyophilization Technology Inc.
- 6.3.12 Martin Christ Gefriertrocknungsanlagen GmbH
- 6.3.13 Millrock Technology
- 6.3.14 Optima Packaging Group Gmbh
- 6.3.15 Scala Scientific
- 6.3.16 SP Industries (ATS)
- 6.3.17 Thermo Fisher Scientific
- 6.3.18 Tofflon Science & Technology
- 6.3.19 Vikumer Freeze Dry
- 6.3.20 ZIRBUS Technology
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment

