PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2121377

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2121377
General Surgical Devices - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the general surgical devices market size is projected to expand from USD 19.81 billion in 2025 and USD 21.32 billion in 2026 to USD 30.79 billion by 2031, registering a CAGR of 7.62% between 2026 to 2031.
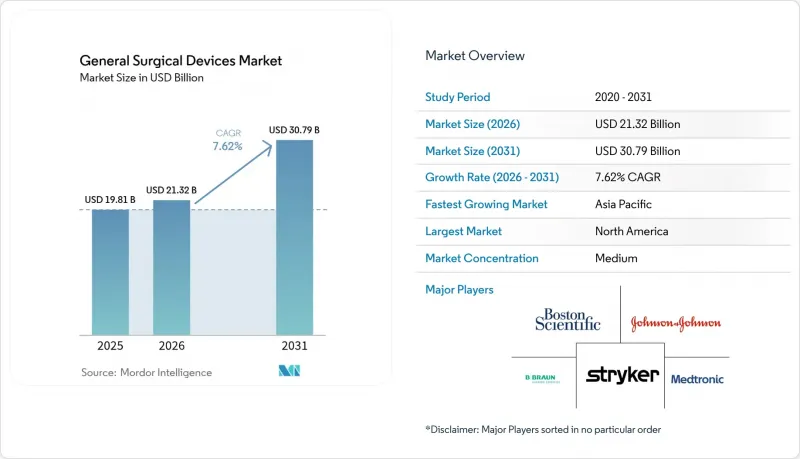
This report is Segmented by Product Type (Minimally Invasive, and More), Application (Orthopaedic, Cardiovascular, Gynaecology & Urology, Neurosurgery, and More), End User (Hospitals, Ascs, Specialty Clinics, and Academic & Research Institutes), and Geography (North America, Europe, Asia-Pacific, Middle East & Africa, and South America). Market Forecasts are Provided in Value (USD).
Global General Surgical Devices Market Trends and Insights
Rising Global Surgical Procedure Volumes
An aging world population, coupled with higher chronic-disease prevalence, is driving up the need for operative care, yet only 45 countries meet the World Health Organization's benchmark of 5,000 procedures per 100,000 people each year. In high-income settings, Intuitive Surgical recorded 2.68 million da Vinci procedures during 2024, a 17% year-over-year jump, with general surgery accounting for the lion's share. This momentum is forcing hospitals to broaden instrument portfolios and stretch capital budgets to maintain throughput. Manufacturers, in response, are rolling out multi-specialty trays and modular robotic arms that slot into existing infrastructure without a full operating-room overhaul. Larger case volumes, meanwhile, reinforce the economics of disposables, further anchoring the general surgical devices market in a growth posture.
Shift Toward Minimally Invasive and Robotic Surgeries
More surgeons are gravitating toward minimally invasive techniques to shorten patient recovery, reduce pain medication use, and enable same-day discharge. The arrival of force-feedback technology in the fifth-generation da Vinci platform-validated by preclinical data showing up to 43% less tissue pressure-lowers the barrier for those who previously hesitated over the loss of tactile sensation. Even so, capital intensity remains a gating factor, prompting leasing models and per-procedure billing that distribute costs across predictable caseloads. As deployment widens, the general surgical devices market sees a halo effect: ancillary ports, staplers, and energy instruments optimized for robotic articulation experience parallel growth in demand.
High Capital and Maintenance Costs of Advanced Systems
Acquiring a top-tier robotic suite can require USD 2.5 million up front, while annual service contracts range between USD 100,000 and USD 200,000. Even though leasing and per-click agreements ease the initial burden, finance committees still seek proof that improved throughput offsets the expense. For many community hospitals, table-mounted or single-port robots that tuck under the operating table represent an attractive alternative by trimming floor-space penalties and capital exposure. Nevertheless, the price tag remains a hurdle that tempers near-term growth in the general surgical devices market.
Other drivers and restraints analyzed in the detailed report include:
- Continuous Technological Advancements in Surgical Instruments
- Increasing Preference for Disposable and Single-Use Devices
- Stringent Regulatory and Compliance Requirements
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Disposable supplies accounted for 43.78% of 2025 revenue, underscoring a hospital's drive to eliminate reprocessing risk and secure sterility assurance. This dominance is reinforced each time accreditation surveys flag lapses in central sterile work-flows, pushing administrators toward single-use kits tailored for common procedures. Robotic instruments, while representing a smaller absolute slice today, are climbing at a 9.65% CAGR to 2031. Their growth depends on the expanding installed base of force-feedback-equipped systems, which makes the transition easier for mid-career surgeons. The general surgical devices market size for robotic consumables is projected to grow in tandem with each console shipped.
A second tier of growth lies in hybrid energy tools that merge ultrasonic cutting, bipolar sealing, and real-time thermal monitoring. Johnson & Johnson's modular generator reduces cart footprints by nearly half, a design win for crowded ambulatory suites. Smart staplers have joined the fray: Medtronic's circular model offers adaptive compression and onboard leak testing, signaling a future in which disposables become data nodes inside connected operating rooms. As premium functions move from capital equipment into single-use formats, value perception continues tilting the general surgical devices market toward advanced disposables.
Complete Report Scope:
- By Product Type
- Minimally Invasive Surgery Instruments
- Robotic-Assisted Surgery Instruments
- Energy-Based Surgery Instruments (RF, Ultrasonic, Laser)
- Open Surgery Instruments
- Disposable / Single-Use Surgical Supplies
- Smart / Sensor-Enabled Instruments
- Other Product Types
- By Application
- Orthopaedic
- Cardiovascular
- Gynaecology & Urology
- Neurosurgery
- Gastrointestinal / Colorectal
- Bariatric & Metabolic
- Thoracic
- Plastic & Reconstructive
- Other Applications
- By End User
- Hospitals
- Ambulatory Surgical Centers
- Specialty Clinics
- Academic & Research Institutes
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America generated 41.54% of 2025 revenue, supported by nearly 10,000 installed da Vinci consoles and reimbursement models that favor minimally invasive techniques. Capital pressure on midsize hospitals persists, but leasing programs and table-mounted robots soften the blow. Ambulatory centers are flourishing as same-day discharge gains payer support, reinforcing demand for disposable kits and anchoring the general surgical devices market in the region.
Europe follows with the mature adoption of robotic and hybrid-energy platforms. Regulatory strictness under EU MDR raised compliance costs, yet recent simplification proposals aim to cut EUR 3.3 billion a year and could reignite product launches. Sustainability imperatives add a new procurement filter, rewarding manufacturers that backtake used plastics or document lifecycle carbon savings.
Asia-Pacific is the fastest-growing region, with an 8.54% CAGR. Government-funded hospital expansion and a swelling middle class widen the customer base, while localized manufacturing initiatives help vendors strike the right price point. Premium data-enabled systems populate urban referral centers, but manual-hybrid instruments still dominate secondary hospitals where budgets remain tight. Emerging markets in Latin America and the Middle East echo similar dynamics on a smaller scale, collectively nudging the general surgical devices market into new territory.
- Applied Medical Resources
- Arthrex
- B. Braun
- Beckton Dickinson
- Boston Scientific
- CMR Surgical Ltd.
- Conmed
- Erbe Elektromedizin
- Integra LifeSciences
- Intuitive Surgical
- Johnson & Johnson (Ethicon, DePuy Synthes, J&J MedTech)
- Kangji Medical Holdings
- Karl Storz
- Medtronic
- Olympus
- Richard Wolf
- Smiths Group
- Solventum
- Stryker
- Teleflex
- Zimmer Biomet
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Global Surgical Procedure Volumes
- 4.2.2 Shift Toward Minimally Invasive and Robotic Surgeries
- 4.2.3 Continuous Technological Advancements in Surgical Instruments
- 4.2.4 Expansion of Healthcare Infrastructure in Emerging Markets
- 4.2.5 Increasing Preference for Disposable and Single-Use Devices
- 4.2.6 Growing Investments in Smart and Connected Operating Rooms
- 4.3 Market Restraints
- 4.3.1 High Capital and Maintenance Costs of Advanced Systems
- 4.3.2 Stringent Regulatory and Compliance Requirements
- 4.3.3 Cybersecurity Risks in Networked Surgical Equipment
- 4.3.4 Shortage of Skilled Surgeons for Next-Generation Technologies
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power Of Suppliers
- 4.7.2 Bargaining Power Of Buyers
- 4.7.3 Threat Of New Entrants
- 4.7.4 Threat Of Substitutes
- 4.7.5 Intensity Of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Product Type
- 5.1.1 Minimally Invasive Surgery Instruments
- 5.1.2 Robotic-Assisted Surgery Instruments
- 5.1.3 Energy-Based Surgery Instruments (RF, Ultrasonic, Laser)
- 5.1.4 Open Surgery Instruments
- 5.1.5 Disposable / Single-Use Surgical Supplies
- 5.1.6 Smart / Sensor-Enabled Instruments
- 5.1.7 Other Product Types
- 5.2 By Application
- 5.2.1 Orthopaedic
- 5.2.2 Cardiovascular
- 5.2.3 Gynaecology & Urology
- 5.2.4 Neurosurgery
- 5.2.5 Gastrointestinal / Colorectal
- 5.2.6 Bariatric & Metabolic
- 5.2.7 Thoracic
- 5.2.8 Plastic & Reconstructive
- 5.2.9 Other Applications
- 5.3 By End User
- 5.3.1 Hospitals
- 5.3.2 Ambulatory Surgical Centers
- 5.3.3 Specialty Clinics
- 5.3.4 Academic & Research Institutes
- 5.4 Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 Japan
- 5.4.3.3 India
- 5.4.3.4 Australia
- 5.4.3.5 South Korea
- 5.4.3.6 Rest of Asia-Pacific
- 5.4.4 Middle East & Africa
- 5.4.4.1 GCC
- 5.4.4.2 South Africa
- 5.4.4.3 Rest of Middle East & Africa
- 5.4.5 South America
- 5.4.5.1 Brazil
- 5.4.5.2 Argentina
- 5.4.5.3 Rest of South America
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (Includes Global-Level Overview, Market-Level Overview, Core Segments, Financials As Available, Strategic Information, Market Rank/Share For Key Companies, Products & Services, And Recent Developments)
- 6.3.1 Applied Medical Resources Corp.
- 6.3.2 Arthrex Inc.
- 6.3.3 B. Braun SE
- 6.3.4 Becton, Dickinson & Co.
- 6.3.5 Boston Scientific Corporation
- 6.3.6 CMR Surgical Ltd.
- 6.3.7 Conmed Corporation
- 6.3.8 Erbe Elektromedizin GmbH
- 6.3.9 Integra LifeSciences Corporation
- 6.3.10 Intuitive Surgical Inc.
- 6.3.11 Johnson & Johnson (Ethicon, DePuy Synthes, J&J MedTech)
- 6.3.12 Kangji Medical Holdings
- 6.3.13 Karl Storz SE & Co. KG
- 6.3.14 Medtronic plc
- 6.3.15 Olympus Corporation
- 6.3.16 Richard Wolf GmbH
- 6.3.17 Smith & Nephew plc
- 6.3.18 Solventum
- 6.3.19 Stryker Corporation
- 6.3.20 Teleflex Incorporated
- 6.3.21 Zimmer Biomet Holdings Inc.
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment

