PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2121405

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2121405
Waterproof Breathable Textiles - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the waterproof breathable textiles market size is expected to grow from USD 2.29 billion in 2025 to USD 2.41 billion in 2026 and is forecast to reach USD 3.10 billion by 2031 at 5.13% CAGR over 2026-2031.
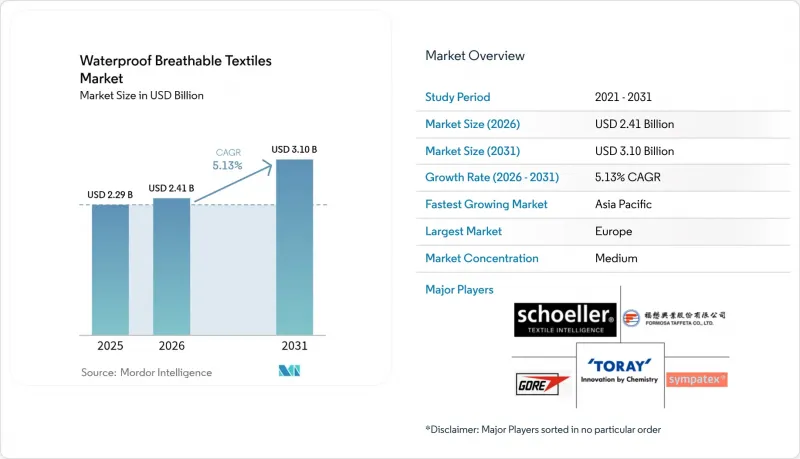
This report is Segmented by Raw Material (PTFE, Polyester, Polyurethane, and Other Raw Materials), Textile (Densely Woven, Membrane-Based, and Coated), Application (Sportswear and Activewear, Protective and Military, General Clothing and Home Textile, and Other Applications), and Geography (Asia-Pacific, North America, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Waterproof Breathable Textiles Market Trends and Insights
Rising Demand From Sports and Outdoor Apparel
In 2024, outdoor participation surged, welcoming U.S. consumers who now prefer breathable shells over traditional cotton blends. Urban trail networks have claimed a significant share of gear purchases, integrating waterproof jackets into daily wear. Columbia's OutDry Extreme Eco III showcases a membrane-free bonding technique, lightening the load for commuters balancing office hours and trailhead adventures. Patagonia has successfully maintained a high hydrostatic-head rating in its H2No 3-layer system, eliminating PFAS treatments and demonstrating the feasibility of fluorine-free products. With France set to enforce a PFAS ban in 2026 and Denmark imposing restrictions in 2025, late reformulators face potential shelf-space challenges. Brands that adapt swiftly not only ensure their presence in EU retail but also command premium prices in specialty outlets.
Expansion of Technical Protective Workwear and Military Tenders
In 2025, NATO and Indo-Pacific modernization efforts led to a procurement surge. Notably, the U.K. mandated an ISO 343 Level 3 breathable outer for its VIRTUS armor refresh. Industrial standards are evolving in tandem with military needs; for instance, EN 343 Class 3 now mandates a moisture transfer of at least 15 g/m2/h, sidelining older PVC-coated nylons. Furthermore, updated ANSI/ISEA guidelines tailored for humid offshore rigs have unlocked a market potential in the Gulf of Mexico and North Sea basins. In a similar vein, Malaysia's 2025 amendments to occupational safety laws now mandate breathable rain gear on construction sites, creating a ripple effect of opportunities across ASEAN.
Regulatory Phase-Out of PFAS Chemistries
In April 2026, ECHA imposed a restriction on PFHxA, a prevalent short-chain PFAS, impacting DWR treatments. France's 25 ppm threshold mandates testing costs, extending lead times. California's AB-1817 adds layers of complexity for brands operating across multiple regions. Silicone DWRs, needing an additional weight, incur extra costs. Gore invested significantly to retrofit its Elkton and Putzbrunn plants for ePE membrane lines, a feat beyond the reach of smaller competitors.
Other drivers and restraints analyzed in the detailed report include:
- Climate-Resilient Infrastructure Boosting Rain-Gear Sales
- Advancements in Bio-Based Polyurethane and Solvent-Free Lamination Technologies
- High Processing and Capital Costs Versus Conventional Fabrics
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Polyurethane accounted for 44.92% of raw-material demand in 2025 and is on course for a 5.80% CAGR, underpinning the waterproof breathable textiles market size gains in cost-sensitive and green-label segments. Its compatibility with waterborne dispersions and castor-oil polyols reduces VOCs and carbon intensity. Polyester supplies most coated-fabric substrates and is benefiting from recycled-content targets. PTFE retains relevance in alpine and defense niches despite feedstock volatility and regulatory scrutiny.
The "Other Raw Materials" bucket-polyamide, polypropylene, graphene-oxide coatings-remains small yet strategically important. Teijin's Nanofront 700-nm fibers create waterproofness via weave density alone, lowering material costs by 20 to 25 percent. Gore's ePE breakthrough illustrates how non-fluorinated resins can replace PTFE without losing performance, but scale-up remains capital-intensive. Brands locking long-term contracts for bio-based polyols secure margin insulation against petrochemical swings, as seen in Patagonia's 2025 agreement with Covestro for CO2-based PU.
Complete Report Scope:
- By Raw Material
- PTFE
- Polyester
- Polyurethane (PU)
- Other Raw Materials
- By Textile
- Densely Woven
- Membrane-based
- Coated
- By Application
- Sportswear and Activewear
- Protective and Military
- General Clothing and Home Textile
- Other Applications
- By Geography
- Asia-Pacific
- China
- Japan
- India
- South Korea
- ASEAN Countries
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Russia
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Europe retained 32.39% of 2025 revenue, buoyed by mature recreation habits and stringent chemical laws that pull PFAS-free innovation forward. German machinery makers, Monforts and Bruckner, facilitated rapid chemistry pivots, granting EU mills a first-mover advantage. France's 2026 PFAS ban hastened brand timelines, allowing contenders like Sympatex to seize shelf space while slower rivals awaited clarity. Following Brexit, U.K. brands, despite a domestic output dip in 2025, pivoted to Canadian and Australian markets, relocating fabrication to Portugal and Turkey.
Asia-Pacific is expanding at a 5.55% CAGR, driven by investments in membrane-lamination from India, Vietnam, and Bangladesh to cater to both export and domestic demands. Toray's collaboration with MAS Holdings in Odisha underscores India's ambitions in technical fabrics, bolstered by the PLI scheme. While China commands a significant share of the global PTFE membrane capacity, it experienced a decline in waterproof-textile exports in 2025, as brands began diversifying their sourcing. Mills in Southeast Asia are gaining momentum by producing PFAS-free coated fabrics that meet EU import standards.
North America's textile and protective gear outlook is closely linked to the FY 2026 defense budget, which allocates a portion to these sectors, and the nation's outdoor-recreation economy. In 2025, Mexico drew in substantial textile investments, focusing on near-shore coating lines to meet a swift 5-day lead-time demand. While South America and the Middle East-Africa regions remain relatively small players, they occasionally surge; for instance, Brazil's procurement post-2024 floods and Saudi Vision 2030's contracts for breathable workwear highlight these climate- and construction-driven spikes. Coated fabrics are favored in these regions, attributed to their cost-effectiveness and ease of maintenance in warmer climates.
- Columbia Sportswear India
- eVent Fabrics (Clarus Corp.)
- FORMOSA TAFFETA CO., LTD.
- HeiQ Materials AG
- Helly Hansen
- Henderson Textiles
- Huntsman Textile Effects
- Jack Wolfskin - Ausrustung For Draussen Gmbh & Co. Kgaa
- Marmot Mountain LLC
- Nisshinbo Textile Inc.
- Patagonia Inc.
- Pertex (Mitsui & Co.)
- Polartec
- Polartec (Milliken & Company)
- schoeller Switzerland
- Stotz & Co. AG (Ventile)
- Sympatex
- Teijin Limited
- The North Face, A VF Company
- TORAY INDUSTRIES, INC.
- W. L. Gore & Associates Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising demand from sports and outdoor apparel
- 4.2.2 Expansion of technical protective workwear and military tenders
- 4.2.3 Climate-resilient infrastructure boosting rain-gear sales in emerging economies
- 4.2.4 Advancements in bio-based Polyurethane and solvent-free lamination technologies
- 4.2.5 Micro-adventure urban outdoor trend spurring casual waterproof fashion
- 4.3 Market Restraints
- 4.3.1 Regulatory phase-out of PFAS chemistries
- 4.3.2 High processing and capital costs versus conventional fabrics
- 4.3.3 PTFE feedstock supply-chain disruptions amid geo-political tensions
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Intensity of Competitive Rivalry
5 Market Size and Growth Forecasts
- 5.1 By Raw Material
- 5.1.1 PTFE
- 5.1.2 Polyester
- 5.1.3 Polyurethane (PU)
- 5.1.4 Other Raw Materials
- 5.2 By Textile
- 5.2.1 Densely Woven
- 5.2.2 Membrane-based
- 5.2.3 Coated
- 5.3 By Application
- 5.3.1 Sportswear and Activewear
- 5.3.2 Protective and Military
- 5.3.3 General Clothing and Home Textile
- 5.3.4 Other Applications
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 Japan
- 5.4.1.3 India
- 5.4.1.4 South Korea
- 5.4.1.5 ASEAN Countries
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Russia
- 5.4.3.6 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle-East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle-East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)}
- 6.4.1 Columbia Sportswear India
- 6.4.2 eVent Fabrics (Clarus Corp.)
- 6.4.3 FORMOSA TAFFETA CO., LTD.
- 6.4.4 HeiQ Materials AG
- 6.4.5 Helly Hansen
- 6.4.6 Henderson Textiles
- 6.4.7 Huntsman Textile Effects
- 6.4.8 Jack Wolfskin - Ausrustung For Draussen Gmbh & Co. Kgaa
- 6.4.9 Marmot Mountain LLC
- 6.4.10 Nisshinbo Textile Inc.
- 6.4.11 Patagonia Inc.
- 6.4.12 Pertex (Mitsui & Co.)
- 6.4.13 Polartec
- 6.4.14 Polartec (Milliken & Company)
- 6.4.15 schoeller Switzerland
- 6.4.16 Stotz & Co. AG (Ventile)
- 6.4.17 Sympatex
- 6.4.18 Teijin Limited
- 6.4.19 The North Face, A VF Company
- 6.4.20 TORAY INDUSTRIES, INC.
- 6.4.21 W. L. Gore & Associates Inc.
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment

