PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2121440

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2121440
Middle East And Africa Polyurethane - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the Middle East and Africa polyurethane market size was valued at USD 2.64 billion in 2025 and estimated to grow from USD 2.76 billion in 2026 to reach USD 3.43 billion by 2031, at a CAGR of 4.46% during the forecast period (2026-2031).
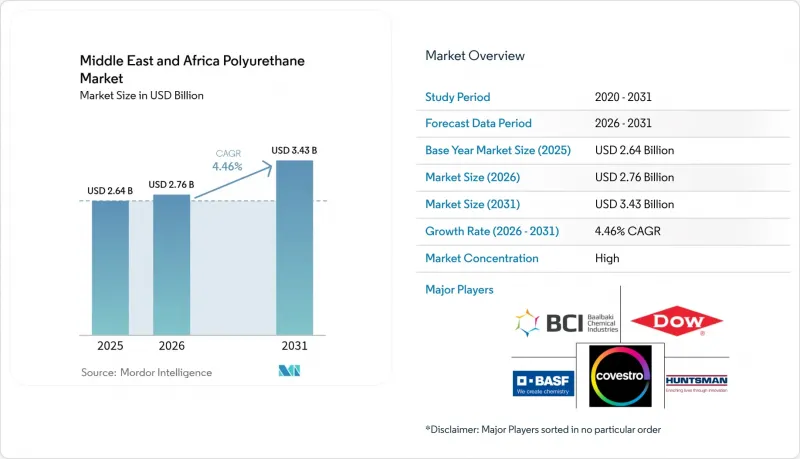
This report is Segmented by Application (Foams, Coatings, Adhesives and Sealants, Elastomers, Others), End-User Industry (Building and Construction, Furniture and Bedding, Automotive, Electronics and Appliances, and More), Raw Material (MDI, TDI, Polyether Polyols, Polyester Polyols, Others), and Geography (Saudi Arabia, United Arab Emirates, South Africa, Egypt, Kuwait, and More).
Middle East And Africa Polyurethane Market Trends and Insights
Infrastructure-Led Construction Boom in GCC
The Gulf's multibillion-dollar project pipeline is the single largest demand catalyst for rigid foams, sealants, and spray-applied insulation. Mega-developments such as NEOM, the Red Sea tourism corridor, and Dubai 2040 urban upgrades specify building-envelope solutions that cut operational emissions by at least 50%. Polyurethane panels and spray systems deliver the required thermal resistance and moisture control under prolonged desert exposure. Modular on-site worker housing and temporary logistics facilities add year-round volume for prefabricated panels containing rigid polyurethane cores. Mandatory local-content thresholds are already encouraging international formulators to build blending plants inside Saudi Arabia and the UAE, shortening lead times and lowering import tariffs. The Middle East and Africa polyurethane market therefore benefits directly from the region's determination to diversify beyond hydrocarbons.
Expansion of Cold-Chain Logistics and Insulation Demand
Rising food-security priorities and vaccine-distribution programs are accelerating investment in temperature-controlled warehouses, solar-powered refrigeration kiosks, and insulated shipping containers. Roughly half of produce losses in sub-Saharan Africa are linked to inadequate cooling infrastructure. Distributed cold rooms equipped with polyurethane-insulated panels and phase-change storage modules cut spoilage, enhance farmer incomes, and meet climate-adaptation funding criteria. African start-ups have deployed thousands of solar refrigeration units since 2020, illustrating the scalable addressable volume for rigid foams. International development banks routinely stipulate high-R-value insulation to maximize energy savings, locking polyurethane into project specifications. These trends reinforce long-run demand visibility for the Middle East and Africa polyurethane market.
Stricter VOC and Worker-Safety Limits on TDI/MDI
The American Conference of Governmental Industrial Hygienists has cut the 8-hour exposure limit for TDI to 1 ppb. Regional factories will need real-time monitoring, specialized ventilation, and biomonitoring programs to remain compliant. Capital upgrades weigh heaviest on small and mid-sized converters that lack scale economies, potentially accelerating consolidation. Multinationals are revising SDS documentation and offering lower-monomer alternatives, but pricing uplifts are unavoidable. Compliance spending is expected to temper near-term margins inside the Middle East and Africa polyurethane market.
Other drivers and restraints analyzed in the detailed report include:
- Automotive and EV Production Localization
- Growth in Regional Furniture and Mattress Manufacturing
- Reduced Energy Subsidies Inflating Processing Costs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Foams generated 59.28% of revenue in 2025, cementing their role as the backbone of insulation, seating, and packaging. Rigid foams benefit most from district-cooling lines and energy-efficient building codes, while flexible foams ride the wave of automotive and furniture expansion. Spray foam usage is climbing in roof retrofits where seamless coverage outperforms board products under thermal-cycling stress. The coatings subsector, though smaller, is growing at a robust 5.19% CAGR on the back of marine anti-corrosion contracts and industrial floor refurbishments. Formulators are introducing zero-VOC polyurethane dispersion technologies to meet tighter emission caps. Collectively, these dynamics reinforce the revenue resilience of the Middle East and Africa polyurethane market.
Advances in elastomer chemistry are opening niches in oil-field pipeline pigs, mining screens, and conveyor belts that demand abrasion resistance. Adhesives and sealants profit from modular construction practices, with moisture-cured grades enabling rapid on-site assembly. Vertical integration by ADNOC after acquiring Covestro is expected to yield cost-optimized foam systems for local converters, enhancing supply-chain agility inside the Middle East and Africa polyurethane market.
Complete Report Scope:
- By Application
- Foams
- Rigid Foam
- Flexible Foam
- Spray Foam
- Coatings
- Adhesives and Sealants
- Elastomers
- Others
- Foams
- By End-user Industry
- Building and Construction
- Furniture and Bedding
- Automotive
- Electronics and Appliances
- Footwear
- Packaging
- Oil and Gas and Mining
- Others
- By Raw Material
- MDI
- TDI
- Polyether Polyols
- Polyester Polyols
- Others (Bio-based Polyols)
- By Geography
- Saudi Arabia
- United Arab Emirates
- South Africa
- Egypt
- Kuwait
- Qatar
- Morocco
- Rest of Middle-East and Africa
List of Companies Covered in this Report:
- BASF
- BCI Holding SA
- Covestro AG
- Dow
- Foamhouse
- Huntsman International LLC
- Kuwait Polyurethane Industries W.L.L.
- LANXESS
- Mitsui Chemicals, Inc.
- Pearl Polyurethane
- Perfect Rubber
- Recticel NV
- Royal Foam Products Ltd.
- SABIC
- SAFIC ALCAN
- Saudi Industrial Resins Limited
- Sika AG
- Synthomer plc
- Vitafoam Nigeria PLC
- Wanhua Chemical Group Co., Ltd.
- Woodbridge
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Infrastructure-led construction boom in GCC
- 4.2.2 Expansion of cold-chain logistics and insulation demand
- 4.2.3 Automotive and EV production localisation
- 4.2.4 Growth in regional furniture and mattress manufacturing
- 4.2.5 District-cooling mandates driving high-R-value panels
- 4.3 Market Restraints
- 4.3.1 Volatile isocyanate and polyol prices
- 4.3.2 Stricter VOC and worker-safety limits on TDI/MDI
- 4.3.3 Reduced energy subsidies inflating PU processing costs
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Value)
- 5.1 By Application
- 5.1.1 Foams
- 5.1.1.1 Rigid Foam
- 5.1.1.2 Flexible Foam
- 5.1.1.3 Spray Foam
- 5.1.2 Coatings
- 5.1.3 Adhesives and Sealants
- 5.1.4 Elastomers
- 5.1.5 Others
- 5.1.1 Foams
- 5.2 By End-user Industry
- 5.2.1 Building and Construction
- 5.2.2 Furniture and Bedding
- 5.2.3 Automotive
- 5.2.4 Electronics and Appliances
- 5.2.5 Footwear
- 5.2.6 Packaging
- 5.2.7 Oil and Gas and Mining
- 5.2.8 Others
- 5.3 By Raw Material
- 5.3.1 MDI
- 5.3.2 TDI
- 5.3.3 Polyether Polyols
- 5.3.4 Polyester Polyols
- 5.3.5 Others (Bio-based Polyols)
- 5.4 By Geography
- 5.4.1 Saudi Arabia
- 5.4.2 United Arab Emirates
- 5.4.3 South Africa
- 5.4.4 Egypt
- 5.4.5 Kuwait
- 5.4.6 Qatar
- 5.4.7 Morocco
- 5.4.8 Rest of Middle-East and Africa
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share**/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 BASF
- 6.4.2 BCI Holding SA
- 6.4.3 Covestro AG
- 6.4.4 Dow
- 6.4.5 Foamhouse
- 6.4.6 Huntsman International LLC
- 6.4.7 Kuwait Polyurethane Industries W.L.L.
- 6.4.8 LANXESS
- 6.4.9 Mitsui Chemicals, Inc.
- 6.4.10 Pearl Polyurethane
- 6.4.11 Perfect Rubber
- 6.4.12 Recticel NV
- 6.4.13 Royal Foam Products Ltd.
- 6.4.14 SABIC
- 6.4.15 SAFIC ALCAN
- 6.4.16 Saudi Industrial Resins Limited
- 6.4.17 Sika AG
- 6.4.18 Synthomer plc
- 6.4.19 Vitafoam Nigeria PLC
- 6.4.20 Wanhua Chemical Group Co., Ltd.
- 6.4.21 Woodbridge
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment

