PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2121555

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2121555
Nanofiber - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the nanofiber market size was valued at USD 1.58 billion in 2025 and estimated to grow from USD 1.9 billion in 2026 to reach USD 4.74 billion by 2031, at a CAGR of 20.07% during the forecast period (2026-2031).
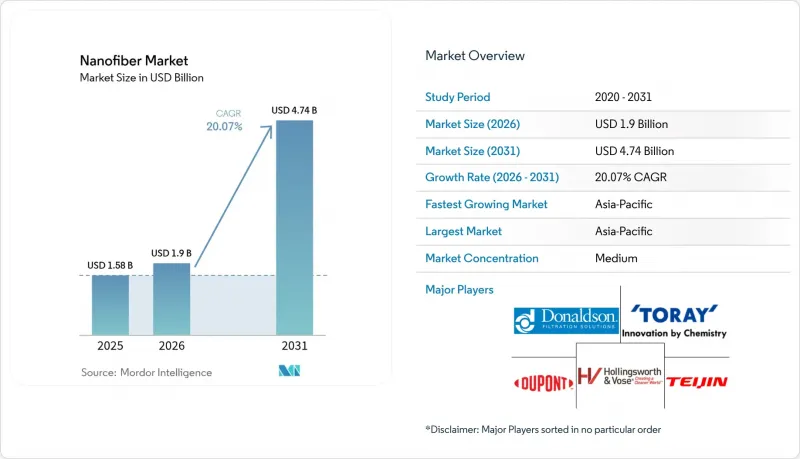
This report is Segmented by Product Type (Polymeric Nanofiber, Carbon Nanofiber, and More), Application (Water and Air Filtration, Medical, and More), Manufacturing Technology (Electrospinning (Needle-Based), Needle-Less Electrospinning, and More), and Geography (Asia-Pacific, North America, Europe, South America, and Middle East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Nanofiber Market Trends and Insights
Increasing Demand from Medical and Pharmaceutical Industries
Nanofiber-based drug delivery platforms now achieve 85%-plus drug loading and sustained release for up to 96 hours, sharply improving therapeutic adherence and lowering systemic toxicity. Their extracellular-matrix-like architecture supports superior cell attachment, enabling next-generation tissue scaffolds that cut healing time and minimize scarring. Hospitals adopting advanced wound dressings cite patient-turnover gains that translate to reduced care costs, strengthening procurement appetite. Regulatory pathways for nanofiber scaffolds in orthopedics continue to clarify, lowering time-to-market risk for developers. Collectively, these medical breakthroughs elevate reimbursement prospects and reinforce recurring demand across high-value healthcare channels.
Demand for High-Surface-Area Battery Separators in EV Gigafactories
Electrospun nanofiber separators now withstand 150 °C thermal excursions without dimensional loss, addressing critical EV safety standards. Enhancements in ion conductivity are extending fast-charge capability by up to 40% while preserving cycle life, a gain attracting procurement from Asian and US gigafactories. Automated roll-to-roll lines scale output beyond 3 million m2 annually, narrowing cost gaps with conventional polyolefin films. Capital deployment by major cell producers is locking in multiyear supply contracts, providing predictable volume visibility for nanofiber vendors. National clean-mobility incentives in China and the United States further amplify separator adoption in new cell chemistries.
Volatile PAN Feedstock Prices
PAN constitutes about 90% of carbon nanofiber precursors, and its spot price fluctuates by up to 20% annually, eroding margin stability for downstream suppliers. Supply disruptions linked to acrylonitrile feed shortages intensify inventory risk, prompting producers to pursue petroleum-asphaltene or lignin alternatives that can cut raw-material cost below USD 9 per kg while raising sustainability credentials. Transition timeframes remain lengthy due to impurity management and variable mechanical performance, prolonging exposure to PAN volatility. Buyers hedge through index-linked contracts, but long-term pricing visibility is still limited, dampening aggressive capacity expansion.
Other drivers and restraints analyzed in the detailed report include:
- Demand for High-Efficiency Filtration Materials
- Growth in the Automotive Industry
- Difficulty in Shifting Carbon Nanofibers from Lab to Plant Scale
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The polymeric category anchors 41.20% of 2025 revenue, driven by well-established electrospinning lines and broad chemical versatility across packaging, filtration and biomedical devices. Carbohydrate-based grades, while smaller in volume, accelerate at a 26.2% CAGR as end-users pursue biodegradable, bio-sourced alternatives aligned with global circular-economy mandates. Cellulose nanofibers rival aramid tensile strength yet biodegrade under ambient conditions, compelling packaging suppliers to adopt them in single-use applications. Chitin nanofibers attract wound-care producers due to inherent antimicrobial traits, spurring investment in shellfish-waste valorization. Carbon nanofibers find significant use in specialty energy and electronics applications; however, production scale and cost challenges are restraining immediate growth.
Momentum for carbohydrate-based products is amplified by brand-owner commitments to cut fossil plastic use. Legislative bans on single-use synthetic fibers in several EU states compound this pull. Composite nanofibers, which blend polymer and ceramic phases, play a significant role in high-temperature filtration niches. Metal and metal-oxide grades serve catalytic and sensing applications where elevated conductivity or photocatalytic activity is critical. Ceramic nanofibers retain demand for thermal insulation in aerospace and furnace linings. As raw-material R&D migrates toward forestry and agricultural waste streams, cost curves are expected to converge, bolstering the broader nanofiber market.
Complete Report Scope:
- By Product Type
- Polymeric Nanofiber
- Carbon Nanofiber
- Composite Nanofiber
- Metal and Metal Oxide Nanofiber
- Ceramic Nanofiber
- Carbohydrate-based Nanofiber
- By Application
- Water and Air Filtration
- Medical
- Energy Storage
- Automotive and Transportation
- Electronics
- Textiles
- Other Applications
- By Manufacturing Technology
- Electrospinning (Needle-Based)
- Needle-less Electrospinning
- Solution Blow Spinning
- ForceSpinning/Rotary Jet Spinning
- Melt Blowing
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific commands 37.60% of 2025 revenue, with China, Japan and South Korea benefitting from deep electronic supply chains and government-backed nanotech initiatives. Robust EV production bases in China elevate local demand for nanofiber separators, while strict environmental guidelines accelerate uptake in air-filtration retrofits. Regional stimulus funds earmarked for sustainable materials further de-risk investment in lignin-derived nanofiber plants. This ecosystem underpins a 21.4% regional CAGR, ensuring Asia-Pacific continues to anchor global volume growth.
North America, driven by the U.S. with its USD 2.2 billion FY-25 National Nanotechnology Initiative budget, which allocates grants to medical, defense, and energy sectors, plays a significant role in global revenue generation. High-value healthcare projects dominate demand; clinical trials for nanofiber-based regenerative implants secure FDA fast-track status, accelerating commercialization. Defense agencies sponsor filtration and protective-wear R&D, fortifying domestic supply chains. Canada's clean-technology incentives and proximity to automotive hubs kindle cross-border collaboration in battery materials. Europe, driven by Germany and France's stringent sustainability frameworks, leads in the market for biodegradable nanofiber packaging and HVAC solutions. Horizon Europe grants foster university-industry clusters that fast-track scale-up and standardization, while REACH compliance guidelines supply regulatory certainty. Although growth rates trail Asia-Pacific, EU directives banning select single-use plastics are opening replacement opportunities in food-service and personal-care products. In South America, the Middle East, and Africa, where programs addressing potable-water scarcity and enhancing agricultural efficiency are gaining traction, revenue is driven by the early adoption of nanofiber membranes in desalination and controlled-release fertilizers.
- Applied Sciences Inc.
- Argonide Corporation
- Asahi Kasei Corporation
- Chuetsu Pulp & Paper Co. Ltd.
- Donaldson Company Inc.
- DuPont
- Esfil Tehno AS
- eSpin Technologies Inc.
- FibeRio Technology Corp.
- Hollingsworth & Vose
- IREMA-Filter GmbH
- Japan Vilene Company Ltd.
- NanoLayr Ltd
- Nanoval GmbH & Co. KG
- NIPPON PAPER INDUSTRIES CO., LTD.
- Pardam SRO
- Rengo Co., Ltd.
- Sappi Ltd.
- SNC Fiber
- Spur AS
- Teijin Limited
- Toray Industries Inc.
- US Global Nanospace Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increasing Demand from the Medical and Pharmaceutical Industries
- 4.2.2 Demand for High-Surface-Area Battery Separators in EV Gigafactories
- 4.2.3 Demand for High-Efficiency Filtration Materials
- 4.2.4 Growth in the Automotive Industry
- 4.2.5 Expansion in the Textile Industry
- 4.3 Market Restraints
- 4.3.1 Volatile PAN Feedstock Prices
- 4.3.2 Difficulty in Shift of Carbon Nanofibers from Lab Scale to Plant Scale due to Small Size and Complexity
- 4.3.3 Health and Safety Concerns
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
- 4.6 Technology Snapshot
- 4.7 Patent Analysis
5 Market Size and Growth Forecasts (Value)
- 5.1 By Product Type
- 5.1.1 Polymeric Nanofiber
- 5.1.2 Carbon Nanofiber
- 5.1.3 Composite Nanofiber
- 5.1.4 Metal and Metal Oxide Nanofiber
- 5.1.5 Ceramic Nanofiber
- 5.1.6 Carbohydrate-based Nanofiber
- 5.2 By Application
- 5.2.1 Water and Air Filtration
- 5.2.2 Medical
- 5.2.3 Energy Storage
- 5.2.4 Automotive and Transportation
- 5.2.5 Electronics
- 5.2.6 Textiles
- 5.2.7 Other Applications
- 5.3 By Manufacturing Technology
- 5.3.1 Electrospinning (Needle-Based)
- 5.3.2 Needle-less Electrospinning
- 5.3.3 Solution Blow Spinning
- 5.3.4 ForceSpinning/Rotary Jet Spinning
- 5.3.5 Melt Blowing
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 India
- 5.4.1.3 Japan
- 5.4.1.4 South Korea
- 5.4.1.5 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global-Level Overview, Market-Level Overview, Core Segments, Financials, Strategic Info, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Applied Sciences Inc.
- 6.4.2 Argonide Corporation
- 6.4.3 Asahi Kasei Corporation
- 6.4.4 Chuetsu Pulp & Paper Co. Ltd.
- 6.4.5 Donaldson Company Inc.
- 6.4.6 DuPont
- 6.4.7 Esfil Tehno AS
- 6.4.8 eSpin Technologies Inc.
- 6.4.9 FibeRio Technology Corp.
- 6.4.10 Hollingsworth & Vose
- 6.4.11 IREMA-Filter GmbH
- 6.4.12 Japan Vilene Company Ltd.
- 6.4.13 NanoLayr Ltd
- 6.4.14 Nanoval GmbH & Co. KG
- 6.4.15 NIPPON PAPER INDUSTRIES CO., LTD.
- 6.4.16 Pardam SRO
- 6.4.17 Rengo Co., Ltd.
- 6.4.18 Sappi Ltd.
- 6.4.19 SNC Fiber
- 6.4.20 Spur AS
- 6.4.21 Teijin Limited
- 6.4.22 Toray Industries Inc.
- 6.4.23 US Global Nanospace Inc.
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment
- 7.2 Increasing R&D and High-potential Market for Cellulosic Nanofibers

