PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2121730

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2121730
Anticoccidial Drugs - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the anticoccidial drugs market size was valued at USD 1.66 billion in 2025 and is estimated to grow from USD 1.74 billion in 2026 to reach USD 2.25 billion by 2031, at a CAGR of 5.28% during the forecast period (2026-2031).
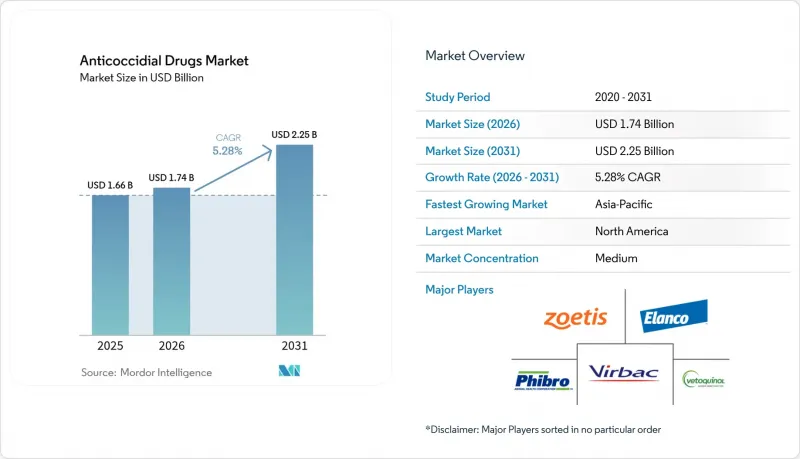
This report is Segmented by Product (Ionophore Anticoccidials, Synthetic Chemical Anticoccidials, and More), Animal Type (Poultry, Cattle, Swine, and More), Drug Action (Coccidiostatic, Coccidiocidal), Distribution Channel (Veterinary Hospitals, and More), and Geography (North America, Europe, Asia-Pacific, Middle East & Africa, South America). Market Forecasts are Provided in Terms of Value (USD).
Global Anticoccidial Drugs Market Trends and Insights
Surge in Integrated Poultry Production in Emerging Economies
Vertically integrated producers in China, India, and the Gulf states continue to consolidate disease-control protocols, mandating standardized anticoccidial regimens that cut mortality and improve feed efficiency. Expanded contract-grower networks embed ionophore rotation rules into supply agreements, compressing purchasing cycles and favoring volume-discount negotiations with top manufacturers.
Rising Prevalence and Economic Burden of Coccidiosis on Intensive Livestock
Global economic losses exceed USD 10 billion, driven by suboptimal weight gain and elevated feed-conversion ratios in high-density systems. Cage-free mandates in the EU and North America inadvertently raise litter contact, lifting incidence by 15-20%. Ionophore-based prevention remains economically justified whenever mortality tops 2% in broilers.
Antimicrobial Resistance & Rotation Fatigue Among Existing Drug Classes
WHO surveillance in 15 countries logged monensin-resistant Eimeria in more than 40% of Asian broiler flocks, shortening effective rotation windows from 12 to 6 months.Adding drug classes increases feed costs by up to USD 0.02 per bird, nudging integrators toward vaccines despite higher unit prices.
Other drivers and restraints analyzed in the detailed report include:
- Regulatory Preference for Non-Medically Important Antimicrobials
- Industry Shift Toward Preventive Feed Additives to Improve Feed Efficiency
- Stringent Residue Limits & Prophylactic Bans in Key Export Markets
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Ionophore anticoccidials held 54.22% of the anticoccidial market share in 2025, led by monensin's wide species label and USD 300 million-plus annual sales. Regionally, Asia-Pacific buyers favor salinomycin and narasin for pelleting stability, while combination products target breeder flocks with extended cycles.
Botanical alternatives are growing at a 5.86% CAGR, leveraging organic certification pull-through. Rabar's Cox-Free reduced mortality by 63% in Brazil and India, while dsm-firmenich's AccuGut C.1 delivered feed-conversion parity within 2% of monensin in field trials. Ceva's Hungary facility, due to end-2026, will add 8 billion vaccine doses per year to serve the NAE tier.
Cattle accounted for 58.07% of the anticoccidial market in 2025, riding on feedlot adoption of monensin, which lifts feed efficiency by 5-8% and trims methane by up to 15%. Poultry remains secondary in value yet primary in volume, with broiler shuttle programs rotating ionophores and triazines.
Companion-animal revenue is expanding at a 7.99% CAGR as telemedicine platforms normalize coccidiosis diagnosis in puppies and kittens. Ponazuril courses retail at USD 30-50, yielding higher per-dose margins than livestock tonnage.
Complete Report Scope:
- By Product
- Ionophore Anticoccidials
- Synthetic Chemical Anticoccidials
- Botanical & Phytogenic Alternatives
- Combination Products
- Live Attenuated & Recombinant Vaccines
- By Animal Type
- Poultry
- Broilers
- Layers
- Breeders
- Cattle
- Swine
- Sheep & Goats
- Aquaculture
- Companion Animals
- Poultry
- By Drug Action
- Coccidiostatic
- Coccidiocidal
- By Distribution Channel
- Veterinary Hospitals
- Veterinary Clinics
- Online Pharmacies
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America accounted for 40.91% of revenue in 2025, underpinned by 9.5 billion U.S. broilers and 95 million cattle that incorporate monensin into feed protocols. Canada's premium egg sector accelerated vaccine uptake, while Mexico's peso volatility widened API import costs.
Asia-Pacific is projected to expand at a 9.35% CAGR, propelled by China's 25.1 million-tonne poultry output and India's contract-grower ascent. Resistance hotspots in southern China are driving up diclazuril demand despite pricing 30-40% higher.
Europe's stringent MRLs and welfare rules prioritize vaccines, whereas Latin America balances ionophore economics with EU residue compliance. Middle East & Africa rely on imported APIs; Bimeda's Dubai hub now supplies South African integrators following its acquisition of Afrivet.
- Abbott Laboratories
- Bayer
- Bimeda Animal Health Ltd.
- BioProperties Pty Ltd.
- Boehringer Ingelheim
- Cargill Incorporated
- Ceva Sante Animale
- Elanco
- Hipra Scientific, S.L.U.
- Huvepharma EOOD
- Impextraco
- Kemin Industries
- Novus International, Inc.
- Phibro Animal Health
- Qilu Animal Health Products Co., Ltd.
- Vetoquinol
- Virbac S.A.
- Zoetis
- Zydus Animal Health
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surge In Integrated Poultry Production In Emerging Economies
- 4.2.2 Rising Prevalence and Economic Burden of Coccidiosis on Intensive Livestock
- 4.2.3 Regulatory Preference for Non-Medically Important Antimicrobials
- 4.2.4 Industry Shift Toward Preventive Feed Additives to Improve Feed Efficiency
- 4.2.5 Adoption of Precision-Dosing Micro-Encapsulated Anticoccidials Via IoT Monitoring
- 4.2.6 Tariff-Driven Localization of Ionophore API Manufacturing
- 4.3 Market Restraints
- 4.3.1 Antimicrobial Resistance & Rotation Fatigue Among Existing Drug Classes
- 4.3.2 Stringent Residue Limits & Prophylactic Bans in Key Export Markets
- 4.3.3 Rapid Uptake of Multi-Valent Eimeria Vaccines in NAE Poultry Segments
- 4.3.4 Volatile Ionophore-Precursor Prices from Supply-Chain Shocks
- 4.4 Regulatory Landscape
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitute Products
- 4.6.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Product
- 5.1.1 Ionophore Anticoccidials
- 5.1.2 Synthetic Chemical Anticoccidials
- 5.1.3 Botanical & Phytogenic Alternatives
- 5.1.4 Combination Products
- 5.1.5 Live Attenuated & Recombinant Vaccines
- 5.2 By Animal Type
- 5.2.1 Poultry
- 5.2.1.1 Broilers
- 5.2.1.2 Layers
- 5.2.1.3 Breeders
- 5.2.2 Cattle
- 5.2.3 Swine
- 5.2.4 Sheep & Goats
- 5.2.5 Aquaculture
- 5.2.6 Companion Animals
- 5.2.1 Poultry
- 5.3 By Drug Action
- 5.3.1 Coccidiostatic
- 5.3.2 Coccidiocidal
- 5.4 By Distribution Channel
- 5.4.1 Veterinary Hospitals
- 5.4.2 Veterinary Clinics
- 5.4.3 Online Pharmacies
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East & Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East & Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products & Services, and Recent Developments)
- 6.3.1 Abbott Laboratories
- 6.3.2 Bayer AG
- 6.3.3 Bimeda Animal Health Ltd.
- 6.3.4 BioProperties Pty Ltd.
- 6.3.5 Boehringer Ingelheim International GmbH
- 6.3.6 Cargill Incorporated
- 6.3.7 Ceva Sante Animale
- 6.3.8 Elanco Animal Health Incorporated
- 6.3.9 Hipra Scientific, S.L.U.
- 6.3.10 Huvepharma EOOD
- 6.3.11 Impextraco NV
- 6.3.12 Kemin Industries, Inc.
- 6.3.13 Novus International, Inc.
- 6.3.14 Phibro Animal Health Corporation
- 6.3.15 Qilu Animal Health Products Co., Ltd.
- 6.3.16 Vetoquinol S.A.
- 6.3.17 Virbac S.A.
- 6.3.18 Zoetis Inc.
- 6.3.19 Zydus Animal Health
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment

