PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2121874

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2121874
Acetaldehyde - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the acetaldehyde market size is projected to expand from 1.21 million tons in 2025 and 1.25 million tons in 2026 to 1.44 million tons by 2031, registering a CAGR of 2.91% between 2026 to 2031.
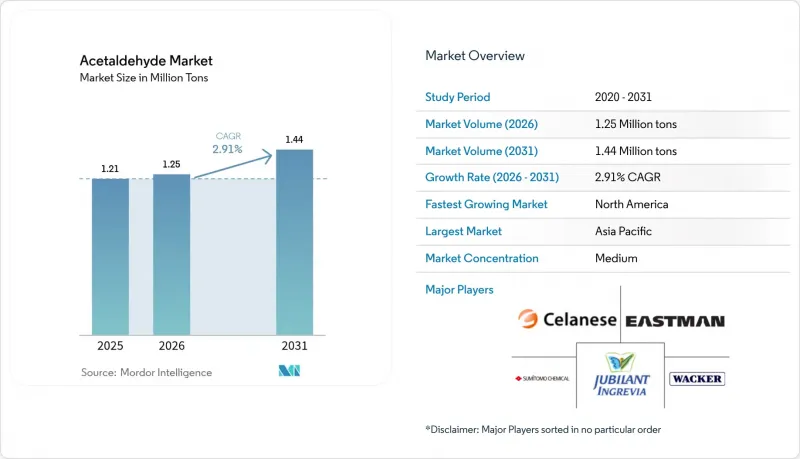
This report is Segmented by Derivative (Pyridine and Pyridine Bases, Pentaerythritol, Acetic Acid, Acetate Esters, and More), End-User Industry (Adhesives, Food and Beverage, Paints and Coatings, Pharmaceuticals, and Other End-User Industries), and Geography (Asia-Pacific, North America, Europe, South America, and Middle East and Africa). Market Forecasts are Provided in Terms of Volume (Tons).
Global Acetaldehyde Market Trends and Insights
Expanding Pentaerythritol Use in Alkyd and UV-Curable Resins
Coatings makers are shifting toward alkyd and UV-curable systems that rely on pentaerythritol produced from acetaldehyde. These resins meet volatile-organic-compound limits below 50 g per liter in the European Union. UV-curable finishes cure without solvent loss, so demand rises in automotive and electronics. Bio-based pentaerythritol can cut lifecycle emissions by up to 30% and earns pricing premiums in sustainability-focused brands. Asia-Pacific leads consumption because of ongoing construction activity, while Europe's REACH rules encourage lower-emission feedstocks. As a result, pentaerythritol growth secures additional pull for the acetaldehyde market.
Growing Acetate-Ester Demand in Low-VOC Solvent Blends
Ethyl, butyl, and propyl acetates come from acetaldehyde via acetic acid and serve as safer solvents in paints, inks, and adhesives. Regulatory frameworks such as the EU Solvent Emissions Directive and California Rule 1113 push formulators to replace aromatics with acetate esters. Flexographic printers are adopting ethyl acetate because it evaporates cleanly and has low toxicity. China keeps adding acetic-acid capacity earmarked for esterification, supporting intra-regional supply. North American demand rebounded in 2025 despite higher ethanol feed costs, showing the resilience of downstream value. Forward-integrated producers capture higher margins than merchants who only sell commodity acetaldehyde.
Carcinogenic Re-Classification and Tighter Workplace Exposure Limits
The International Agency for Research on Cancer lists acetaldehyde as Group 2B, prompting regulators to lower exposure limits. ACGIH set a ceiling value of 25 ppm in 2024, and several U.S. states consider stricter thresholds. Formulators in flavors and preservatives are reformulating or substituting to avoid compliance costs. Industrial users invest in closed-loop systems and vapor recovery, increasing fixed costs and pressuring smaller firms.
Other drivers and restraints analyzed in the detailed report include:
- Breakthrough Ethane-to-Acetaldehyde PdO Catalysis
- Circular PET De-Aldehyde Upgrades Raising Bottle-Grade Quality Bar
- Ethylene Price Volatility Squeezing Wacker-Process Margins
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Acetic acid captured 28.12% of the 2025 volume, confirming its position as the largest single outlet within the acetaldehyde market share. The acetaldehyde market size linked to pyridine and pyridine bases is projected to widen at a 3.78% CAGR through 2031 as agrochemical and pharmaceutical producers scale demand for acetaldehyde-ammonia trimer intermediates.
Pentaerythritol ranks second and mirrors coatings growth, while acetate esters rise on the pull from low-VOC solvents. Butylene glycol stays niche, serving cosmetics where bio-based fermentation routes compete. Peracetic acid grows in food sanitation, benefiting from a favorable regulatory status relative to chlorine.
Complete Report Scope:
- By Derivative
- Pyridine and Pyridine Bases
- Pentaerythritol
- Acetic Acid
- Acetate Esters
- Butylene Glycol
- Other Derivatives (Chloral, Peracetic Acid, etc.)
- By End-User Industry
- Adhesives
- Food and Beverage
- Paints and Coatings
- Pharmaceuticals
- Other End-user Industries (Water Treatment, Plastics, Rubber, Fuel Additives, etc.)
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- NORDIC
- Turkey
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific accounted for 57.25% of global volume in 2025, anchored by China's 10.81 million-ton annual acetic-acid capacity. New units scheduled for 2026 indicate continuing scale additions despite thinner margins. India's acetaldehyde demand is rising due to pharmaceutical and agrochemical investments, and mergers such as Laxmi Organic with Yellowstone Fine Chemicals highlight consolidation aimed at feedstock security.
North America is forecast to register the fastest regional pace at 3.13% CAGR from 2026-2031. Ethane-rich feedstock and policy support, including clean-energy tax credits, underpin several expansion projects. Celanese started a 1.3 million-ton acetic acid addition in March 2024 and positions it as the lowest-carbon unit globally, courtesy of co-located ethylene crackers.
Europe remains challenged by high naphtha-based ethylene costs but pursues competitiveness through renewable routes. Sekab's wood-cellulose acetaldehyde line, certified in 2024, exemplifies the pivot. South America leverages sugarcane ethanol yet continues to export raw feedstock rather than investing heavily in downstream acetaldehyde capacity. Middle East producers monitor PdO catalysis because abundant ethane could unlock a cost advantage once the technology scales.
- Arkema S.A
- Celanese Corporation
- Daicel Corporation
- Eastman Chemical Company
- INEOS Group Ltd.
- Jubilant Ingrevia Limited
- Laxmi Organic Industries Ltd.
- LCY
- Lonza
- Merck KGaA
- Resonac Corporation
- Sekab
- Sumitomo Chemical Co., Ltd.
- Wacker Chemie AG
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Expanding pentaerythritol use in alkyd and UV-curable resins
- 4.2.2 Growing acetate-ester demand in low-VOC solvent blends
- 4.2.3 Breakthrough ethane-to-acetaldehyde PdO catalysis
- 4.2.4 Circular PET de-aldehyde upgrades raising bottle-grade quality bar
- 4.2.5 Bio-ethanol derived acetaldehyde for low-carbon supply chains
- 4.3 Market Restraints
- 4.3.1 Carcinogenic re-classification and tighter workplace exposure limits
- 4.3.2 Ethylene price volatility squeezing Wacker-process margins
- 4.3.3 On-site formaldehyde generation replacing acetaldehyde in disinfectants
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Suppliers
- 4.5.3 Bargaining Power of Buyers
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Volume)
- 5.1 By Derivative
- 5.1.1 Pyridine and Pyridine Bases
- 5.1.2 Pentaerythritol
- 5.1.3 Acetic Acid
- 5.1.4 Acetate Esters
- 5.1.5 Butylene Glycol
- 5.1.6 Other Derivatives (Chloral, Peracetic Acid, etc.)
- 5.2 By End-User Industry
- 5.2.1 Adhesives
- 5.2.2 Food and Beverage
- 5.2.3 Paints and Coatings
- 5.2.4 Pharmaceuticals
- 5.2.5 Other End-user Industries (Water Treatment, Plastics, Rubber, Fuel Additives, etc.)
- 5.3 By Geography
- 5.3.1 Asia-Pacific
- 5.3.1.1 China
- 5.3.1.2 India
- 5.3.1.3 Japan
- 5.3.1.4 South Korea
- 5.3.1.5 Rest of Asia-Pacific
- 5.3.2 North America
- 5.3.2.1 United States
- 5.3.2.2 Canada
- 5.3.2.3 Mexico
- 5.3.3 Europe
- 5.3.3.1 Germany
- 5.3.3.2 United Kingdom
- 5.3.3.3 France
- 5.3.3.4 Italy
- 5.3.3.5 Spain
- 5.3.3.6 Russia
- 5.3.3.7 NORDIC
- 5.3.3.8 Turkey
- 5.3.3.9 Rest of Europe
- 5.3.4 South America
- 5.3.4.1 Brazil
- 5.3.4.2 Argentina
- 5.3.4.3 Rest of South America
- 5.3.5 Middle-East and Africa
- 5.3.5.1 Saudi Arabia
- 5.3.5.2 South Africa
- 5.3.5.3 Rest of Middle-East and Africa
- 5.3.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials, Strategic Information, Products and Services, Recent Developments)
- 6.4.1 Arkema S.A
- 6.4.2 Celanese Corporation
- 6.4.3 Daicel Corporation
- 6.4.4 Eastman Chemical Company
- 6.4.5 INEOS Group Ltd.
- 6.4.6 Jubilant Ingrevia Limited
- 6.4.7 Laxmi Organic Industries Ltd.
- 6.4.8 LCY
- 6.4.9 Lonza
- 6.4.10 Merck KGaA
- 6.4.11 Resonac Corporation
- 6.4.12 Sekab
- 6.4.13 Sumitomo Chemical Co., Ltd.
- 6.4.14 Wacker Chemie AG
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment

