PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2121888

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2121888
Paraxylene (PX) - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the paraxylene market size is projected to be 64.48 million tons in 2025, 67.79 million tons in 2026, and reach 87.14 million tons by 2031, growing at a CAGR of 5.15% from 2026 to 2031.
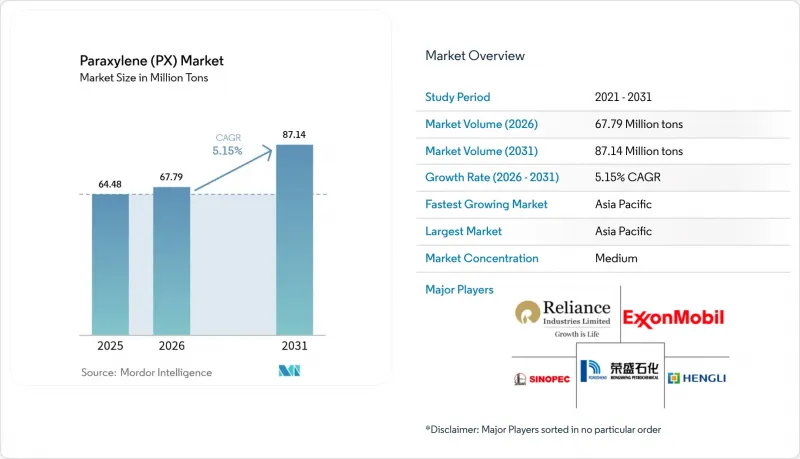
This report is Segmented by Application (Purified Terephthalic Acid, Dimethyl Terephthalate, and Other Applications), End-Use Industry (Textile, Plastics, and Others), and Geography (Asia-Pacific, North America, Europe, South America, and Middle-East and Africa). Market Forecasts are Provided in Terms of Volume (Tons).
Global Paraxylene (PX) Market Trends and Insights
Surging Demand for PET Packaging
Brand-owner commitments, urban expansion, and a swift rise in cold-chain logistics are driving up the demand for PET bottles, even as recycling targets become more stringent. The European Union's Regulation 2025/40 mandates a recycled-content threshold by 2030. Yet, in 2023, only a portion of PET bottles collected in Europe were recycled, resulting in a reliance on virgin PTA to bridge the gap. Meanwhile, collection rates in India, Indonesia, and Vietnam remain low. Consequently, new PTA plants in these nations continue to be centered around prime PX feed. Global PTA nameplate capacity is set to rise significantly in the coming years, signaling robust confidence in packaging demand. Petrochemical feedstock demand is projected to grow between 2023 and 2030, highlighting the sector's resilience. While beverage producers are exploring bio-PX pathways, their commercial availability is still confined to pilot volumes, ensuring virgin material's dominance for the remainder of the decade.
Polyester-Fiber Expansion in Asia
Forecasts indicate a surge in global polyester staple fiber consumption, projected to rise significantly by 2030. This uptick is largely driven by increasing disposable incomes and the rapid pace of fast-fashion supply chains. In 2023, China achieved a notable milestone, reaching high self-sufficiency in paraxylene (PX). However, downstream yarn producers, Hengyi and Tongkun, are aggressively expanding their operations to capitalize on these cost advantages. Meanwhile, India's ambitious refining-petrochemical integration strategy is set to introduce substantial crude capacity by FY 2029-30. This move not only reroutes naphtha streams into aromatics but also amplifies the nation's domestic PX production. To put this into perspective, every significant diversion of naphtha translates to an augmentation in PX capacity. Thus, adjustments in Asian refinery configurations have a direct ripple effect on upstream supply. Furthermore, this vertical integration acts as a buffer against spot-price fluctuations. Captive PTA users, by securing feed through long-term contracts, further solidify Asia's position as the dominant hub of the Paraxylene market.
Single-Use-Plastic Legislation Tightening
By 2030, the European Union has set a target of mandating recycled content in PET bottles, with an ambitious increase by 2040. In the U.S., California's SB-54 enforces a similar mandate. Europe's mechanical recycling capacity currently falls short of the required levels to meet the 2030 target. This gap suggests a significant reduction in the use of virgin resin, should the supply align with targets. Brand owners are also navigating design-for-recycling mandates and bans on PFAS, potentially leading to a decrease in PET usage per package. While enforcement timelines differ, the overarching policy direction limits growth in developed markets, steering producers towards chemical recycling or bio-PX alternatives. Currently, while demand in OECD economies lags, it's buoyed by consumption in Asia and Africa. Nonetheless, the legislative trend poses a consistent challenge for the Paraxylene market.
Other drivers and restraints analyzed in the detailed report include:
- Commercialization of High-Yield CCR/PRT Aromatics Units
- Government-Backed Paraxylene Self-Sufficiency Programs in India
- Crude-Oil-Led Feedstock Price Volatility
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
PTA consumed 94.37% of global PX volume in 2025 and is forecast to grow at a 5.37% CAGR through 2031. This heavy concentration ties the Paraxylene market closely to polyester dynamics, making producer economics heavily reliant on trends in textiles and packaging. Between 2021 and 2026, Asia bolstered its PTA capacity significantly, with China leading the charge across multiple projects. A testament to the industry's scale requirements, Tongkun unveiled a large-scale plant in Quanzhou. As integrated sites like Hengli Dalian increasingly feed their captive downstream lines, the Paraxylene market's appetite for PTA continues to swell. This trend is further accentuated by a diminishing merchant trade volume, making spot prices more susceptible to any unforeseen outages.
While Dimethyl Terephthalate and select specialty outlets command a modest share of the demand, their growth trajectory closely mirrors that of GDP. PTA's cost-effectiveness and superior polymerization kinetics have made it the dominant choice for commodity resins. In contrast, DMT finds its niche, primarily in specialized films and niche polyesters, where flexibility in processing takes precedence over feedstock pricing. Other applications, including plasticizers, isophthalic acid, and a handful of minor chemicals, exert minimal influence on the broader Paraxylene market. Regulatory oversight tends to emphasize the sustainability of downstream polymers over the purity of PX or PTA. Consequently, compliance for feedstocks leans more towards ISO 9001 standards and moisture specifications, sidelining environmental considerations.
Complete Report Scope:
- By Application
- Purified Terephthalic Acid (PTA)
- Dimethyl Terephthalate (DMT)
- Other Applications
- By End-use Industry
- Textile
- Plastics
- Others End-user Industries
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Thailand
- Indonesia
- Malaysia
- Vietnam
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- South America
- Brazil
- Argentina
- Colombia
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- United Arab Emirates
- Qatar
- Nigeria
- Egypt
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific captured 82.21% of PX volume in 2025 and is set to expand at a 5.49% CAGR through 2031. In a significant move, China introduced new xylene capacity in the latter half of 2025, elevating its national xylene capacity. The region's momentum is further underscored by projects like the Sinopec-Aramco Fujian complex, targeting PX by 2030, and the Tahe refinery's expansion, set to add PX by 2028. Echoing this trend, India aims for self-sufficiency, planning to add PX by 2030. Meanwhile, producers in South Korea and Japan are either downsizing or retrofitting to stay competitive in exports.
While North America holds a modest share of the Paraxylene market, it enjoys protective tariff shields against Chinese PTA imports. The U.S. Gulf Coast, with Beaumont as its largest unit, houses the bulk of this capacity. Europe, however, faces a structural decline: as refineries pivot to biofuels, the output of aromatics diminishes. This shift leaves the remaining PTA plants reliant on imports. In the Middle East, Saudi Aramco's Jazan and the planned Yanbu expansions are capitalizing on low-cost feedstock and their strategic closeness to Asia, positioning the region as a swing exporter. Conversely, South America remains tethered as an import-dependent market, sourcing both PX and PTA from the Gulf Coast and Asia, a reliance that's projected to persist throughout the decade.
- China Petrochemical Corporation
- CNPC
- Eneos Corporation
- Exxon Mobil Corporation
- FCFC
- GS Caltex Corporation
- Hengli Petrochemical Co., Ltd.
- Idemitsu Kosan Co.,Ltd.
- Ineos
- LOTTE CHEMICAL CORPORATION
- PTT Global Chemical Public Company Limited
- Reliance Industries Limited
- Rongsheng Petrochemical Co., Ltd.
- S-oil Corporation
- TotalEnergies
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surging demand for PET packaging
- 4.2.2 Polyester-fiber expansion in Asia
- 4.2.3 Commercialisation of high-yield CCR/PRT aromatics units
- 4.2.4 Government-backed Paraxylene self-sufficiency programs in India
- 4.2.5 Simulated-Moving-Bed (SMB) revamp boosting Paraxylene yield
- 4.3 Market Restraints
- 4.3.1 Single-use-plastic legislation tightening
- 4.3.2 Crude-oil led feedstock price volatility
- 4.3.3 US-China tariff risk disrupting PX/PTA trade flows
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Volume and Value)
- 5.1 By Application
- 5.1.1 Purified Terephthalic Acid (PTA)
- 5.1.2 Dimethyl Terephthalate (DMT)
- 5.1.3 Other Applications
- 5.2 By End-use Industry
- 5.2.1 Textile
- 5.2.2 Plastics
- 5.2.3 Others End-user Industries
- 5.3 By Geography
- 5.3.1 Asia-Pacific
- 5.3.1.1 China
- 5.3.1.2 India
- 5.3.1.3 Japan
- 5.3.1.4 South Korea
- 5.3.1.5 Thailand
- 5.3.1.6 Indonesia
- 5.3.1.7 Malaysia
- 5.3.1.8 Vietnam
- 5.3.1.9 Rest of Asia-Pacific
- 5.3.2 North America
- 5.3.2.1 United States
- 5.3.2.2 Canada
- 5.3.2.3 Mexico
- 5.3.3 Europe
- 5.3.3.1 Germany
- 5.3.3.2 United Kingdom
- 5.3.3.3 France
- 5.3.3.4 Italy
- 5.3.3.5 Spain
- 5.3.3.6 Russia
- 5.3.3.7 Rest of Europe
- 5.3.4 South America
- 5.3.4.1 Brazil
- 5.3.4.2 Argentina
- 5.3.4.3 Colombia
- 5.3.4.4 Rest of South America
- 5.3.5 Middle-East and Africa
- 5.3.5.1 Saudi Arabia
- 5.3.5.2 United Arab Emirates
- 5.3.5.3 Qatar
- 5.3.5.4 Nigeria
- 5.3.5.5 Egypt
- 5.3.5.6 South Africa
- 5.3.5.7 Rest of Middle-East and Africa
- 5.3.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 China Petrochemical Corporation
- 6.4.2 CNPC
- 6.4.3 Eneos Corporation
- 6.4.4 Exxon Mobil Corporation
- 6.4.5 FCFC
- 6.4.6 GS Caltex Corporation
- 6.4.7 Hengli Petrochemical Co., Ltd.
- 6.4.8 Idemitsu Kosan Co.,Ltd.
- 6.4.9 Ineos
- 6.4.10 LOTTE CHEMICAL CORPORATION
- 6.4.11 PTT Global Chemical Public Company Limited
- 6.4.12 Reliance Industries Limited
- 6.4.13 Rongsheng Petrochemical Co., Ltd.
- 6.4.14 S-oil Corporation
- 6.4.15 TotalEnergies
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment

