PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2122185

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2122185
Behavioral Rehabilitation - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the behavioral rehabilitation market size in 2026 is estimated at USD 621.93 billion, growing from 2025 value of USD 584.3 billion with 2031 projections showing USD 848.47 billion, growing at 6.44% CAGR over 2026-2031.
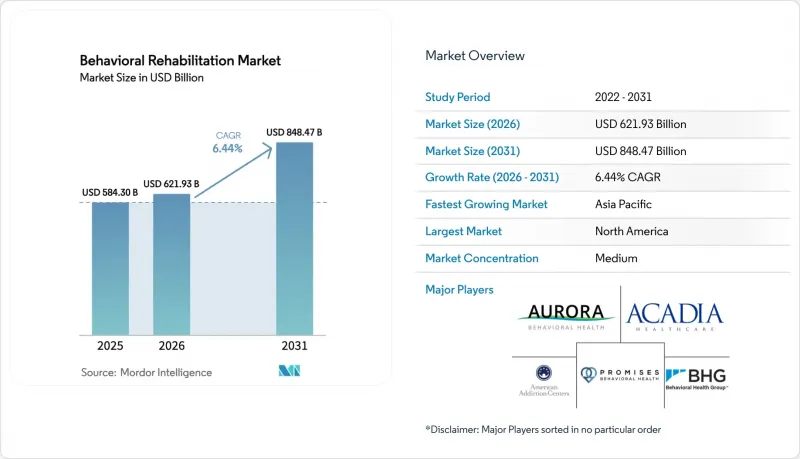
This report is Segmented by Type of Behavioral Disorder (Anxiety Disorder, and More), Healthcare Setting (Outpatient Programs, and More), Treatment Method (Counselling, and More), by Age Group (Adults, and More), Delivery Mode (In-Person Facility-Based, and More), Geography (North America, Europe, Asia-Pacific, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Behavioral Rehabilitation Market Trends and Insights
Escalating Global Mental-Health Disease Burden Accelerating Demand
The worldwide rise in mental-health disorders is stretching existing treatment capacity. One-third of the U.S. population lives in designated Mental Health Professional Shortage Areas, demonstrating the gap between service need and availability. Drug-overdose deaths exceeded 107,000 in 2021, and untreated behavioral conditions cost the U.S. economy USD 280 billion annually in lost productivity and medical expenses. These figures underscore the imperative for capacity expansion across all treatment modalities.
Government Policy Shifts Toward Coverage Parity
Final rules under the Mental Health Parity and Addiction Equity Act take effect on January 1, 2025, prohibiting health plans from applying stricter limits to behavioral health than to medical benefits. Plans must analyze network adequacy and utilization management, which is expected to widen coverage for millions of Americans. CMS's 2025 physician fee schedule also adds new codes for FDA-cleared digital therapeutics and safety-planning services, unlocking fresh reimbursement pathways for providers.
Persistent Stigma & Cultural Barriers Limiting Service Uptake
Only 58.5% of U.S. teenagers reported adequate emotional and social support in 2024, and 91% of Hispanic Americans with substance-use disorders did not receive needed treatment. Cultural norms, language gaps, and mistrust of formal systems hamper engagement even when services exist. Community-based outreach, bilingual workforce development, and culturally relevant peer-support models are essential to close this divide.
Other drivers and restraints analyzed in the detailed report include:
- Rapid Adoption of Telehealth & Digital Platforms
- Integration of Behavioral Health into Primary-Care Pathways
- Shortage of Licensed Behavioral-Health Professionals Restricting Scalability
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Anxiety disorders contributed 30.86% to the behavioral rehabilitation market size in 2025, cementing their status as the dominant segment. Rising diagnosis rates and broader insurance coverage promote early intervention, while AI-based monitoring tools have lifted adherence by 45%. Digital therapeutics that deliver cognitive-behavioral content via mobile apps reinforce therapist-led protocols and extend reach beyond clinic walls. Immersive VR exposure therapy, for instance, helps recalibrate maladaptive fear responses and shortens course duration.
Substance-abuse disorders are projected to log a 7.63% CAGR between 2026 and 2031. Policy priority reflects the ongoing opioid crisis, with USD 1.6 billion earmarked for the State Opioid Response program in 2025. Medication-assisted treatment expansion and 988 crisis-line funding support earlier identification and referral. Managed-care penetration is steering providers toward value-based contracts that reward sustained abstinence, nudging facilities to adopt data-driven outcome tracking and wraparound social-support services.
Outpatient services accounted for 36.68% behavioral rehabilitation market share in 2025 as payers favor lower-intensity, community-anchored care. CMS has designated new facility-specialty provider types for outpatient behavioral health beginning 2025, enabling direct billing by licensed counselors and marriage-and-family therapists. These shifts bolster financial sustainability for clinics and accelerate geographic spread into underserved zones.
Inpatient centers still attract significant percentage of revenue, primarily managing acute crises and dual-diagnosis complexity. Updated SAMHSA crisis-care guidelines stress a coordinated system comprising 988 call centers, mobile crisis teams, and stabilization units. Residential programs face heightened scrutiny over youth outcomes and cost-effectiveness, prompting operators to standardize evidence-based protocols and publish routine performance dashboards.
Complete Report Scope:
- By Type of Behavioral Disorder
- Anxiety Disorder
- Mood Disorder
- Substance Abuse Disorder
- Personality Disorder
- Attention Deficit Disorder
- Autism Spectrum Disorder
- By Healthcare Setting
- Outpatient Programs
- Inpatient Programs
- Residential Programs
- By Treatment Method
- Counselling
- Medication
- Support Services
- Other Treatment Methods
- By Delivery Mode
- In-Person Facility-based
- Virtual / Tele-rehabilitation
- Hybrid
- By Age Group
- Children & Adolescents (<=17 yrs)
- Adults (18-64 yrs)
- Geriatric (>=65 yrs)
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America topped the behavioral rehabilitation market with a 41.72% share in 2025 on the strength of comprehensive insurance coverage and mature provider networks. Implementation of parity regulations and USD 602 million federal funding for the 988 crisis-line in 2025 reinforce service access. Consolidation is brisk as private equity funds buy multi-state platforms, standardize electronic medical records, and elevate outcome reporting. Rising unionization among clinical staff, however, is lifting wage costs and nudging operators toward tele-supervision efficiencies.
Asia-Pacific is the fastest-growing region, registering a 6.88% CAGR between 2026 and 2031. Government campaigns in Japan, China, and India are destigmatizing mental-health consultations and embedding coverage into national insurance schemes. Task-shifting programs that certify bachelor-level counselors are rapidly scaling capacity. The region's med-tech sector is investing in language-agnostic chatbots to surmount clinician shortages and extend behavioral rehab services into rural districts.
Europe maintained 27.00% revenue in 2025, supported by universal health coverage and robust social-protection mechanisms. Countries such as the United Kingdom and Germany have introduced digital-therapeutics formularies that allow physicians to prescribe app-based cognitive behavioral programs reimbursed under statutory funds. Workforce demographics, however, signal impending retirements; several EU nations now offer expedited licensure pathways for migrants with psychiatric credentials.
The Middle East & Africa, while smaller in base, is experiencing consistent growth as governments integrate mental-health targets into national vision plans. Telehealth platforms circumvent clinician scarcity and cultural stigma, particularly in Gulf Cooperation Council member states. International NGOs are partnering with local ministries to build community-based rehab centers and train peer support workers, fueling nascent demand for evidence-based interventions.
- Acadia Healthcare Co. Inc.
- Universal Health Services
- Magellan Health
- Springstone
- American Addiction Centers Holdings Inc.
- Aurora Behavioral Health System
- Behavioral Health Group LLC
- Haven Behavioral Healthcare
- Promises Behavioral Health
- Niznik Behavioral Health
- Teladoc Health
- Lyra Health
- Ginger
- Brightline Inc.
- Talkspace Inc.
- MindPath Health
- Cigna Behavioral Health
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Escalating Global Mental-Health Disease Burden Accelerating Demand for Rehabilitation Services
- 4.2.2 Government Policy Shifts Toward Coverage Parity for Behavioral Care
- 4.2.3 Rapid Adoption of Telehealth & Digital Platforms Expanding Access
- 4.2.4 Private-Equity & Strategic Investment Boosting Capacity & Standardization
- 4.2.5 Integration of Behavioral Health into Primary-Care Pathways Increasing Referrals
- 4.2.6 Workforce Innovation (Peer Support, AI Triage) Enhancing Service Efficiency
- 4.3 Market Restraints
- 4.3.1 Persistent Stigma & Cultural Barriers Limiting Service Uptake
- 4.3.2 Shortage of Licensed Behavioral-Health Professionals Restricting Scalability
- 4.3.3 Fragmented Reimbursement Models Creating Provider Financial Uncertainty
- 4.3.4 Data-Privacy & Cross-Border Regulation Slowing Tele-rehab Expansion
- 4.4 Porter's Five Forces Analysis
- 4.4.1 Threat of New Entrants
- 4.4.2 Bargaining Power of Buyers
- 4.4.3 Bargaining Power of Suppliers
- 4.4.4 Threat of Substitutes
- 4.4.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Type of Behavioral Disorder
- 5.1.1 Anxiety Disorder
- 5.1.2 Mood Disorder
- 5.1.3 Substance Abuse Disorder
- 5.1.4 Personality Disorder
- 5.1.5 Attention Deficit Disorder
- 5.1.6 Autism Spectrum Disorder
- 5.2 By Healthcare Setting
- 5.2.1 Outpatient Programs
- 5.2.2 Inpatient Programs
- 5.2.3 Residential Programs
- 5.3 By Treatment Method
- 5.3.1 Counselling
- 5.3.2 Medication
- 5.3.3 Support Services
- 5.3.4 Other Treatment Methods
- 5.4 By Delivery Mode
- 5.4.1 In-Person Facility-based
- 5.4.2 Virtual / Tele-rehabilitation
- 5.4.3 Hybrid
- 5.5 By Age Group
- 5.5.1 Children & Adolescents (<=17 yrs)
- 5.5.2 Adults (18-64 yrs)
- 5.5.3 Geriatric (>=65 yrs)
- 5.6 Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 India
- 5.6.3.4 Australia
- 5.6.3.5 South Korea
- 5.6.3.6 Rest of Asia-Pacific
- 5.6.4 Middle East & Africa
- 5.6.4.1 GCC
- 5.6.4.2 South Africa
- 5.6.4.3 Rest of Middle East & Africa
- 5.6.5 South America
- 5.6.5.1 Brazil
- 5.6.5.2 Argentina
- 5.6.5.3 Rest of South America
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Business Segments, Financials, Headcount, Key Information, Market Rank, Market Share, Products and Services, and analysis of Recent Developments)
- 6.3.1 Acadia Healthcare Co. Inc.
- 6.3.2 Universal Health Services Inc.
- 6.3.3 Magellan Health Inc.
- 6.3.4 Springstone Inc.
- 6.3.5 American Addiction Centers Holdings Inc.
- 6.3.6 Aurora Behavioral Health System
- 6.3.7 Behavioral Health Group LLC
- 6.3.8 Haven Behavioral Healthcare Inc.
- 6.3.9 Promises Behavioral Health
- 6.3.10 Niznik Behavioral Health
- 6.3.11 Teladoc Health Inc.
- 6.3.12 Lyra Health Inc.
- 6.3.13 Ginger
- 6.3.14 Brightline Inc.
- 6.3.15 Talkspace Inc.
- 6.3.16 MindPath Health
- 6.3.17 Cigna Behavioral Health
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment

