PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2122188

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2122188
Nurse Call Systems - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
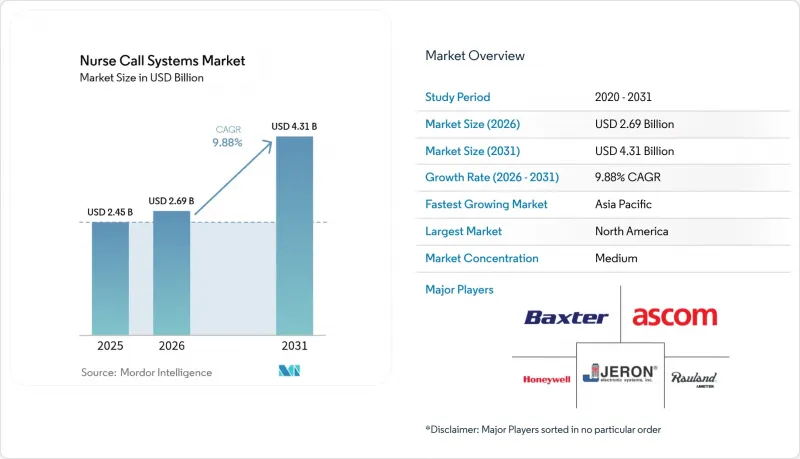
According to Mordor Intelligence, the nurse call systems market size is expected to grow from USD 2.45 billion in 2025 to USD 2.69 billion in 2026 and is forecast to reach USD 4.31 billion by 2031 at 9.88% CAGR over 2026-2031.
This report is Segmented by Product (Nurse Call Buttons, and More), Modality (Wired and Wireless), Application (Emergency Alarms, Workflow Optimization, Fall Detection, and Wanderer Control), End User (Hospitals, Long-Term Care, Nursing Homes, and Home Healthcare), and Geography (North America, Europe, Asia-Pacific, MEA, and South America). Market Forecasts are Provided in Terms of Value (USD).
Global Nurse Call Systems Market Trends and Insights
Growing Geriatric Population and Rising Chronic Disease Burden
The number of people aged 60 and above will double to 2.1 billion by 2050, with 80% living in low- and middle-income countries where bed capacity remains low. Japan already faces a projected nursing shortfall of 270,000 by 2025 despite wage increases, driving hospitals to deploy sensor-based call systems that automatically triage alerts. Multimorbidity further strains legacy hardware: patients with three or more chronic conditions trigger 4.2-times more call-button activations than general med-surg wards. Medicare now penalizes hospitals in the worst quartile for falls, intensifying demand for predictive fall-detection modules. Vendors integrating accelerometer data from wearable pendants can issue pre-emptive alerts up to 30 seconds before an incident, protecting margins tied to value-based purchasing.
Accelerating Hospital Digitalization and Smart Infrastructure Spending
U.S. hospital IT budgets expanded 18.3% per year from 2019-2023, doubling connected-infrastructure outlays to USD 12.8 billion in 2024. EHR vendors now require FHIR-compliant alarm routing, pulling forward refresh cycles by two to three years. A 400-bed site that unified nurse call with RTLS shaved average response times from 4.2 to 1.8 minutes, translating into 12,000 recaptured nurse-hours and USD 1.4 million in avoided overtime. Yet capital for full IP backbones still ranges from USD 500,000 to USD 2 million, pushing many rural hospitals toward wireless overlays or five-year subscription contracts priced at USD 8-15 per bed per month.
High Capital Expenditure for IP Conversions in Legacy Facilities
Retrofitting a 300-bed hospital costs USD 1.2-1.8 million and may disrupt wards for up to nine months. Margins at rural U.S. hospitals average below 2%, rendering full migrations unrealistic without grants or bond financing. European public facilities face budget levels still 8-12% below pre-pandemic baselines, extending the life of 1990s wired systems. Battery-powered wireless overlays cut headline costs to USD 300,000-500,000 for a 200-bed site but sacrifice deep EHR and RTLS integration. Subscription pricing eases cap-ex yet meets resistance from finance teams that prefer depreciable assets.
Other drivers and restraints analyzed in the detailed report include:
- Regulatory Push for Patient Safety and Rapid Response Metrics
- Convergence of Nurse Call with Unified Clinical Communication Platforms
- Interoperability and Data Integration Challenges Across Vendor Systems
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Cloud-enabled suites are advancing at a 11.54% CAGR and are on track to eclipse USD 1.6 billion in the nurse call systems market by 2031. IP-based systems still accounted for 34.65% of revenue in 2025 because they embed alerts into RTLS badges and EHR workflows, but adoption remains concentrated in academic medical centers. Basic audio-visual hardware persists in long-term care where Medicaid rates lag private pay. Intercom products serve behavioral units that restrict mobile devices.
Hospitals balancing cap-ex limits and integration demands are shifting toward hybrid models: on-premise servers manage real-time routing while analytics reside in the cloud. Ascom's Telligence 7 represents this middle path, whereas TekTone's Tek-CARE300III overlays wireless buttons on existing wires at one-third the cost of full IP migration. Subscription penetration, still below 20%, should accelerate as finance teams acclimate to operating expense treatment and vendors demonstrate lower churn.
Wireless platforms accounted for 62.65% revenue in 2025 and will climb at 11.67% CAGR. Retrofit speed and network-rewiring avoidance make them the default for aging facilities and ambulatory surgery centers. Yet battery logistics add USD 18,000 and 600 nursing hours per year for a typical 300-bed hospital, a cost that wired PoE installations avoid.
Cybersecurity has risen in the decision matrix: the 2024 Change Healthcare event illustrated how unsecured IoT nodes can escalate risk exposure. Vendors now tout AES-256 encryption and SOC 2 Type II attestations as table stakes, increasing development costs that smaller entrants struggle to absorb. Wireless also enables at-home monitoring reimbursed by Medicare Advantage at USD 50-65 per patient monthly, opening an adjacent revenue stream.
Complete Report Scope:
- By Product
- Nurse Call Buttons
- Intercom Nurse Call Systems
- Basic Audio/Visual Systems
- IP-Based Nurse Call Systems
- Mobile & Cloud-Enabled Platforms
- By Modality
- Wired Systems
- Wireless Systems
- By Application
- Emergency Medical Alarms
- Workflow & Staff Optimisation
- Fall Detection & Prevention
- Wanderer Control & Dementia Care
- By End User
- Hospitals & Specialty Clinics
- Long-Term Care Facilities
- Nursing Homes
- Home-Healthcare Settings
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America delivered 41.43% of 2025 revenue, buoyed by Joint Commission mandates and CMS penalties. Ongoing digitization grants the region an early-adopter edge, yet replacement cycles slow absolute growth. Asia-Pacific will record a 10.43% CAGR, the fastest worldwide, as China's 2025 health spend reached USD 1.2 trillion and Japan's seniors now constitute 29% of its population. Nurse shortages exceeding 270,000 have pushed Japan toward acuity-based triage, benefiting advanced call suites.
India's Ayushman Bharat insurance program stipulates the installation of functional nurse call systems in empaneled hospitals, creating a steady baseline demand. Australia's 2025 EQuIP update, which mandates queue-depth visibility, has translated into RTLS-linked upgrades across public hospitals.
Europe's expansion lags because public budgets remain 8-12% below pre-pandemic levels. The Middle East shows a two-speed pattern: Gulf states fund smart hospitals as part of diversification plans, whereas sub-Saharan Africa struggles with limited capital. South America is similarly split; Brazil mandated call coverage for SUS-accredited sites, but Argentina's 200% inflation in 2024 froze most capital spending.
- Accutech Healthcare
- Alpha Communications
- Ascom
- Austco Healthcare
- Baxter
- BEC Integrated Solutions LLC
- Caretronic
- Cornell Communications
- Critical Alert
- Fujian Huanyutong Technology Co.
- Honeywell International
- IndigoCare
- Intercall Systems
- Jeron Electronic Systems Inc.
- Momentum Healthcare
- Rauland-Borg Corporation
- Siemens Healthineers
- Systems Technologies
- TekTone Sound & Signal Mfg. Inc.
- Tunstall Healthcare Group
- Vigil Health Solutions Inc.
- West-Com Nurse Call Systems Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope Of The Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing Geriatric Population and Rising Chronic Disease Burden
- 4.2.2 Accelerating Hospital Digitalization and Smart Infrastructure Spending
- 4.2.3 Regulatory Push for Patient Safety and Rapid Response Metrics
- 4.2.4 Convergence of Nurse Call With Unified Clinical Communication Platforms
- 4.2.5 Expansion of Home Health and Remote Patient Monitoring Ecosystems
- 4.2.6 Transition From Capex To Subscription-Based "Nurse Call As A Service" Models
- 4.3 Market Restraints
- 4.3.1 High Capital Expenditure for IP Conversions In Legacy Facilities
- 4.3.2 Interoperability and Data Integration Challenges Across Vendor Systems
- 4.3.3 Escalating Cybersecurity and Privacy Compliance Costs
- 4.3.4 Workforce Shortages Limiting Effective Utilization of Advanced Features
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat Of New Entrants
- 4.7.2 Bargaining Power Of Buyers
- 4.7.3 Bargaining Power Of Suppliers
- 4.7.4 Threat Of Substitutes
- 4.7.5 Intensity Of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Product
- 5.1.1 Nurse Call Buttons
- 5.1.2 Intercom Nurse Call Systems
- 5.1.3 Basic Audio/Visual Systems
- 5.1.4 IP-Based Nurse Call Systems
- 5.1.5 Mobile & Cloud-Enabled Platforms
- 5.2 By Modality
- 5.2.1 Wired Systems
- 5.2.2 Wireless Systems
- 5.3 By Application
- 5.3.1 Emergency Medical Alarms
- 5.3.2 Workflow & Staff Optimisation
- 5.3.3 Fall Detection & Prevention
- 5.3.4 Wanderer Control & Dementia Care
- 5.4 By End User
- 5.4.1 Hospitals & Specialty Clinics
- 5.4.2 Long-Term Care Facilities
- 5.4.3 Nursing Homes
- 5.4.4 Home-Healthcare Settings
- 5.5 Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East & Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East & Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles {(Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products & Services, and Recent Developments)}
- 6.3.1 Accutech Healthcare
- 6.3.2 Alpha Communications
- 6.3.3 Ascom Holding AG
- 6.3.4 Austco Healthcare
- 6.3.5 Baxter International (Hillrom)
- 6.3.6 BEC Integrated Solutions LLC
- 6.3.7 Caretronic
- 6.3.8 Cornell Communications
- 6.3.9 Critical Alert
- 6.3.10 Fujian Huanyutong Technology Co.
- 6.3.11 Honeywell International Inc.
- 6.3.12 IndigoCare
- 6.3.13 Intercall Systems
- 6.3.14 Jeron Electronic Systems Inc.
- 6.3.15 Momentum Healthware
- 6.3.16 Rauland-Borg Corporation
- 6.3.17 Siemens Healthineers
- 6.3.18 Systems Technologies
- 6.3.19 TekTone Sound & Signal Mfg. Inc.
- 6.3.20 Tunstall Healthcare Group
- 6.3.21 Vigil Health Solutions Inc.
- 6.3.22 West-Com Nurse Call Systems Inc.
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment

