PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2122210

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2122210
Nickel Alloys - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the nickel alloys market size is expected to increase from 471.13 kilotons in 2025 to 500.07 kilotons in 2026 and reach 646.51 kilotons by 2031, growing at a CAGR of 5.27% over 2026-2031.
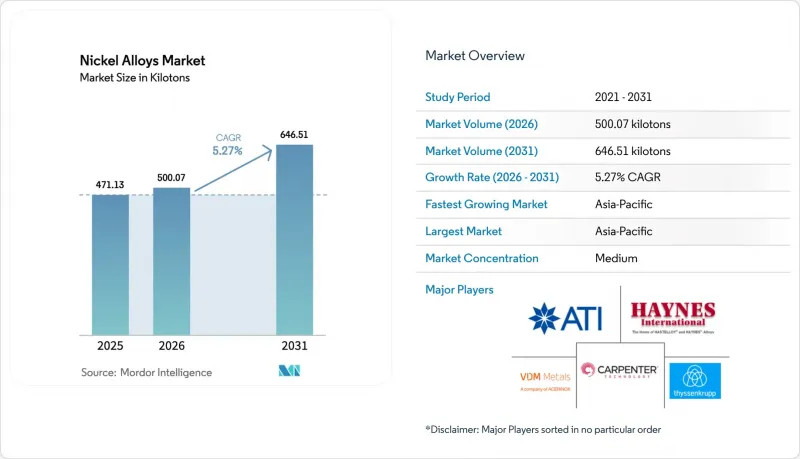
This report is Segmented by Alloy Type (Heat-Resistant, Corrosion-Resistant, Electrical-Resistance, and More), Nickel Type (Nickel-Chromium-Iron, Nickel-Copper, Nickel-Iron, and More), End-Use Industry (Aerospace, Electrical and Electronics, Oil and Gas, and More), and Geography (Asia-Pacific, North America, Europe, and More). The Market Forecasts are Provided in Terms of Volume (Tons).
Global Nickel Alloys Market Trends and Insights
Aerospace Super-Alloys Demand Surge
Commercial backlogs exceeded 14,000 aircraft in 2024, translating to an estimated 280,000 metric tons of nickel-based super-alloy demand over the next decade. Engine makers are adopting higher-pressure-ratio architectures that operate beyond 1,650 °C, a regime that mandates single-crystal Rene and Inconel castings with exceptionally tight chemistry windows. Defense programs such as the U.S. Air Force Next Generation Air Dominance fighter require alloys that cycle between -55 °C and 1,200 °C within milliseconds. Additive manufacturing is reducing weight by up to 25% on turbine components although powder feedstock remains three to four times costlier than wrought bar. These aerospace dynamics ensure sustained, high-value pull on the nickel alloys market for at least another decade.
Battery-Grade Nickel Shift in EV Cathodes
High-nickel NMC 811 and NMC 9-5-5 chemistries now deliver energy densities above 250 Wh kg-1, displacing earlier 532 formulations. Automakers outside China are signing multi-year offtake contracts to secure low-carbon Class 1 supply; General Motors committed to 75,000 metric tons from 2026-2030, subject to carbon thresholds below 10 tons CO2 per ton nickel. The European Union Battery Regulation will impose mandatory carbon-footprint ceilings from 2030, reinforcing demand for responsibly sourced feedstock. While China's LFP surge diluted nickel intensity in 2025, global battery-grade nickel tonnage still rose on aggregate, locking in a pivotal growth vector for the nickel alloys market.
Nickel Supply-Chain Geopolitical Risk
Indonesia's ore-export ban and downstream mandates have routed 68% of incoming FDI to Chinese-controlled joint ventures, centralizing supply but elevating Western security concerns. The United States invoked the Defense Production Act to fast-track the Tamarack project, yet permitting challenges persist. Jakarta's WTO appeal against an unfavorable November 2024 ruling prolongs uncertainty, compelling aerospace primes to requalify alternative feedstocks, a process costing up to USD 5 million per grade. This uncertainty tempers near-term volume expansion in the nickel alloys market.
Other drivers and restraints analyzed in the detailed report include:
- Small-Modular Nuclear Reactors Build-Out
- Hydrogen Turbine Retrofits
- Volatile LME Pricing and Hedging Costs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
In 2025, Heat-Resistant Nickel Alloys, including superalloys, dominated the nickel alloys market with a 47.76% share. Their leadership stems from their indispensable role in high-temperature, high-stress environments. Advanced precipitation-hardened superalloys and directionally solidified variants are preferred for critical applications such as aero-engine hot sections, industrial gas turbines, and hydrogen-fueled power plants operating above 1,000 °C. The expansion of commercial aviation fleets, increasing maintenance cycles, and the development of LNG and hydrogen infrastructures drive consistent demand for forged disks, turbine blades, and combustors. Additionally, retrofitting power generation systems for improved thermal efficiency is boosting the use of higher-creep-strength alloys, supporting long-term consumption.
Heat-Resistant Nickel Alloys (including superalloys) is also the fastest-growing segment, with a projected 6.26% CAGR from 2026 to 2031, driven by additive manufacturing and next-generation propulsion programs. Laser and electron-beam powder-bed fusion enable intricate cooling channels and lighter components, increasing superalloy powder demand and improving material utilization across aerospace supply chains. Thermal-barrier-coated superalloys are gaining traction in small modular reactors and concentrated solar power receivers, while advanced coatings extend service intervals in heavy-duty turbines. Although design optimizations are improving material efficiency per engine, rising engine production, overhaul cycles, and demand for high-temperature industrial equipment offset these gains. As electrification shifts metal demand from traditional alloys, heat-resistant nickel superalloys remain structurally essential, ensuring stable, performance-driven growth in the nickel alloys market.
Complete Report Scope:
- By Alloy Type
- Heat-Resistant Nickel Alloys
- Corrosion-Resistant Nickel Alloys
- Electrical-Resistance Nickel Alloys
- Low-Expansion Nickel Alloys
- Shape-Memory and High-Strength Alloys
- By Nickel Type
- Nickel-Chromium-Iron Alloys
- Nickel-Copper Alloys
- Nickel-Iron Alloys
- Nickel-Chromium-Molybdenum Alloys
- Other Types
- By End-use Industry
- Aerospace
- Electrical and Electronics
- Oil and Gas
- Chemical Processing
- Automotive
- Other End-user Industries
- By Geography
- Asia-Pacific
- China
- Japan
- India
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Russia
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific commanded 49.62% of 2025 revenue and is forecast to advance 7.56% annually to 2031, the fastest among all regions. Indonesia produced 1.8 million tons of nickel ore in 2024 and operates 23 HPAL and RKEF facilities that feed both battery-grade matte and stainless pig iron. China remains the largest stainless producer at 33 million tons in 2024, consuming roughly 1.5 million tons of nickel though the shift toward 200-series grades is lowering intensity per ton. India's defense build-out lifted domestic orders for Inconel forgings awarded by Hindustan Aeronautics in 2024.
North America benefits from the Inflation Reduction Act's 30% tax credits for battery components and the CHIPS Act's USD 52 billion outlay for semiconductor fabs that rely on ultra-low-expansion alloys. ATI's USD 140 million Pennsylvania expansion targets aerospace super-alloy demand and advanced electrical steels. Europe faces embedded-carbon tariffs under the Carbon Border Adjustment Mechanism that could exceed EUR 2,000 per ton for Indonesian nickel, redirecting buyers to Canadian or Finnish suppliers with lower footprints.
South America remains niche, driven by Brazilian offshore pre-salt fields requiring corrosion-resistant subsea hardware rated to 200 MPa at 2,000 m depths. The Middle East and Africa show project-driven demand, epitomized by Saudi Arabia's USD 7 billion NEOM industrial cluster and South Africa's platinum processing upgrades that specify nickel-based alloys for sulfuric-acid leaching circuits. Collectively, these geographic vectors give the nickel alloys market a balanced demand base and mitigate over-reliance on any single consuming region.
- ATI
- Haynes International
- VDM Metals
- thyssenkrupp Materials NA, Inc.
- CRS Holdings, LLC.
- Precision Castparts Corp.
- NeoNickel
- Sandvik AB
- voestalpine Specialty Metals
- SANYO SPECIAL STEEL Co., Ltd.
- Nippon Yakin Kogyo
- JLC Electromet Pvt. Ltd.
- Berkshire Hathaway Inc.
- Kennametal Inc.
- Proterial, Ltd.
- Alloys International, Inc.
- Eramet
- Arconic
- Outokumpu
- GLENCORE
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Aerospace super-alloys demand surge
- 4.2.2 Battery-grade nickel shift in EV cathodes
- 4.2.3 Small-modular nuclear reactors build-out
- 4.2.4 Hydrogen turbine retrofits
- 4.2.5 Defense hypersonics and space launch vehicles
- 4.3 Market Restraints
- 4.3.1 Nickel supply-chain geopolitical risk
- 4.3.2 Volatile LME nickel pricing and hedging costs
- 4.3.3 High lifecycle CO2 footprint vs. green-steel options
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Volume)
- 5.1 By Alloy Type
- 5.1.1 Heat-Resistant Nickel Alloys
- 5.1.2 Corrosion-Resistant Nickel Alloys
- 5.1.3 Electrical-Resistance Nickel Alloys
- 5.1.4 Low-Expansion Nickel Alloys
- 5.1.5 Shape-Memory and High-Strength Alloys
- 5.2 By Nickel Type
- 5.2.1 Nickel-Chromium-Iron Alloys
- 5.2.2 Nickel-Copper Alloys
- 5.2.3 Nickel-Iron Alloys
- 5.2.4 Nickel-Chromium-Molybdenum Alloys
- 5.2.5 Other Types
- 5.3 By End-use Industry
- 5.3.1 Aerospace
- 5.3.2 Electrical and Electronics
- 5.3.3 Oil and Gas
- 5.3.4 Chemical Processing
- 5.3.5 Automotive
- 5.3.6 Other End-user Industries
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 Japan
- 5.4.1.3 India
- 5.4.1.4 South Korea
- 5.4.1.5 ASEAN Countries
- 5.4.1.6 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Russia
- 5.4.3.6 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle-East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 ATI
- 6.4.2 Haynes International
- 6.4.3 VDM Metals
- 6.4.4 thyssenkrupp Materials NA, Inc.
- 6.4.5 CRS Holdings, LLC.
- 6.4.6 Precision Castparts Corp.
- 6.4.7 NeoNickel
- 6.4.8 Sandvik AB
- 6.4.9 voestalpine Specialty Metals
- 6.4.10 SANYO SPECIAL STEEL Co., Ltd.
- 6.4.11 Nippon Yakin Kogyo
- 6.4.12 JLC Electromet Pvt. Ltd.
- 6.4.13 Berkshire Hathaway Inc.
- 6.4.14 Kennametal Inc.
- 6.4.15 Proterial, Ltd.
- 6.4.16 Alloys International, Inc.
- 6.4.17 Eramet
- 6.4.18 Arconic
- 6.4.19 Outokumpu
- 6.4.20 GLENCORE
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment

