PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2122248

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2122248
Honeycomb Core Materials - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the honeycomb core materials market size is expected to grow from USD 4.35 billion in 2025 to USD 4.73 billion in 2026 and is forecast to reach USD 7.30 billion by 2031 at 9.06% CAGR over 2026-2031.
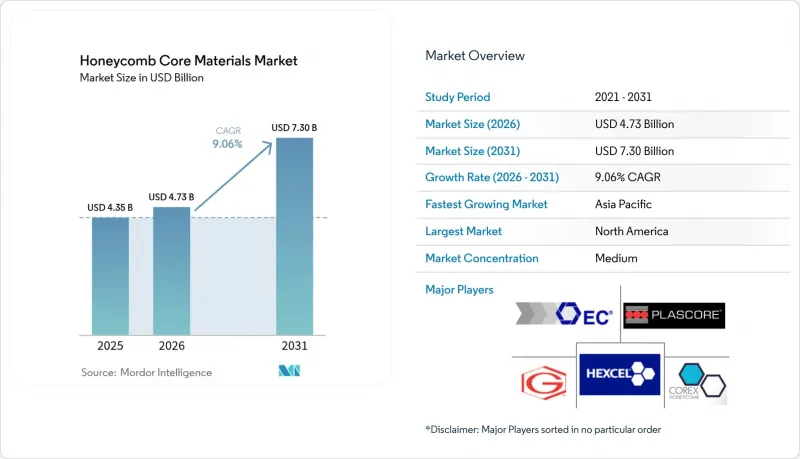
This report is Segmented by Product Type (Nomex, Aluminum, Thermoplastic, and Other Product Types), End-User Industry (Aerospace, Defense, and More), Manufacturing Technology (Expansion, Corrugation, and More), Application (Composite Sandwich Panels and Non-Composite Inserts and Spacers), and Geography (Asia-Pacific, North America, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Honeycomb Core Materials Market Trends and Insights
Growing Demand for Lightweighting in Next-Gen Single-Aisle Aircraft
In 2025, A320neo production hit record monthly rates, driving up demand for aluminum and Nomex cores used in floor panels and interior partitions. Boeing's adoption of generative-design partitions slashed panel weight, boosting the value of each installed core without adding mass. Japanese suppliers dominate the scene, providing the world's carbon fiber and solidifying their role in the feedstock chain for composite-heavy airframes. Hexcel's decision to double its Moroccan capacity, positioning it closer to Airbus's final assembly lines, underscores the industry's emphasis on localization to mitigate logistics risks. These developments collectively suggest a stable demand for honeycomb core materials in the single-aisle segment over the next few years.
Shift to Composite Sandwich Panels in Airframes
OEMs are shifting sandwich construction from secondary fairings to load-bearing ribs and frames, raising the bar for core compression strength. Hexcel's HRH-302 mid-temperature core, now qualified for the MQ-25 program, opens up nacelle and hot-zone applications that aluminum cannot fulfill. Toray's new 400 °C press enables simultaneous co-curing of PEEK organosheets and honeycomb, reducing both scrap and labor. To counter intensified thermal gradients from quicker cure cycles, suppliers are now providing graded-density cores that prevent crushing during autoclave ramps. In the Honeycomb core materials market, price premiums on mid-temperature grades are balancing out the increased costs of resin and energy, thus safeguarding profit margins.
Moisture Ingress and Out-of-Plane Strength Loss
High humidity exposure can significantly reduce core energy absorption and instigate corrosion at bond lines. While barrier films and closed-cell coatings mitigate these risks, they also inflate costs and decelerate throughput. Marine panels, despite enduring the harshest conditions, are still mandated by IMO rules to use honeycomb, incurring additional protection expenses. Hygric testing can prolong certification, immobilizing capital for both OEMs and suppliers. The Honeycomb core materials market grapples with the challenge of balancing durability and speed to market.
Other drivers and restraints analyzed in the detailed report include:
- Weight-Reduction Mandates in Inter-City High-Speed Rail Coaches
- Adoption of Polypropylene Cores in EV Battery Enclosures
- Persistent Price Volatility in Aramid-Paper Supply Chain
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Aluminum cores held a 38.28% Honeycomb core materials market share in 2025, firmly establishing their dominance in aerospace interiors and control surfaces. Meanwhile, thermoplastic polypropylene cores are forecast to post a 10.98% CAGR, thanks to their moisture uptake and recyclability benefits. Super-alloy cores carve out a specialized niche for hypersonic applications, while paper cores cater to the demand for cost-effective packaging.
Polypropylene's unique property allows it to fuse in situ with PEKK face sheets, eliminating adhesive lines that can trap moisture. EconCore's ThermHex line has achieved scale economies that compete with traditional expansion methods, particularly for automotive volumes. In Colorado, Toray's expansion of thermoplastic tape paves the way for co-consolidated rail panels, designed for recyclability at the end of their lifecycle. With OEMs increasingly emphasizing circularity, the penetration of thermoplastics is on the rise, signaling a gradual reduction in aluminum's lead in the honeycomb core materials market.
Aerospace contributed 62.89% of the 2025 demand, anchoring the Honeycomb core materials market size, yet other industries are set to expand 11.27% annually as cost curves fall. Rail coaches, marine bulkheads, and EV battery enclosures now justify sandwich panels on total-cost savings alone.
Both the packaging and construction sectors are eyeing paper and thermoplastic cores, seeking cost-effective options. In China and Europe, rail mandates are pushing for floor and roof substitutions, achieving energy paybacks in just two years. Marine builders, prioritizing IMO fire compliance, are opting for higher densities and accepting margin premiums. Meanwhile, defense programs, though sporadic, are offering lucrative contracts for super-alloy cores. Collectively, these trends are reducing the industry's reliance on aerospace, diversifying the revenue streams of the Honeycomb core materials market.
Complete Report Scope:
- By Product Type
- Nomen
- Aluminum
- Thermoplastic
- Other Product Types (Paper, Super-alloy)
- By End-user Industry
- Aerospace
- Defense
- Marine
- Other End-user Industries (Transportation, Packaging, etc.)
- By Manufacturing Technology
- Expansion
- Corrugation
- Extrusion/Lamination
- 3-D Printing/Additive Core Building
- By Application
- Composite Sandwich Panels
- Non-Composite Inserts and Spacers
- By Geography
- Asia-Pacific
- China
- Japan
- India
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
North America controlled 35.21% of revenue in 2025 due to deep aerospace supply chains and classified hypersonic funding. Hexcel's Moroccan plant, supplying Airbus, will staff workers by late 2026. The U.S. FY 2023 budget earmarked significant amounts for hypersonic research and development, underpinning demand for super-alloy cores. Canada and Mexico add incremental growth through automotive and industrial assemblies.
Asia-Pacific is forecast to expand at an 11.10% CAGR, the quickest regional pace. China's high-speed rail weight rules drove floor mass cuts in CRH5 coaches, sharply boosting core consumption. Japan supplies the majority of global carbon fiber, cementing its role in composite supply. South Korea, India, and ASEAN nations are localizing honeycomb fabrication for fighter and rail programs. Domestic Chinese suppliers are reverse-engineering Inconel cores, but certification lags imported grades by several years.
Europe maintains a substantial share of Airbus output and EN 45545 rail standards that favor phenolic and aramid cores. However, higher energy and compliance costs trim competitiveness. German automakers test polypropylene cores in EV packs to reach 25% recycled content by 2028. Nordic shipyards buy moisture-resistant cores for cold-water yachts. South America and the Middle East remain small today, yet projects like Saudi Arabia's NEOM and Embraer's supply chain could open localized Honeycomb core materials market pockets.
- Alucoil
- Argosy International Inc.
- Axiom Materials.
- Corex Honeycomb
- Corint Group
- EconCore
- Euro-Composites
- Grigeo Group AB
- Hangzhou Holycore Composite Material Co.,Ltd
- Hexcel Corporation
- Plascore
- Schutz GmbH & Co. KGaA.
- The Gill Corporation
- TORAY INDUSTRIES, INC.
- Tubus Bauer GmbH
- Yamaton Honicore B.V.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing demand for lightweighting in next-gen single-aisle aircraft
- 4.2.2 Shift to composite sandwich panels in airframes
- 4.2.3 Weight-reduction mandates in inter-city high-speed rail coaches
- 4.2.4 Adoption of polypropylene cores in EV battery enclosures
- 4.2.5 Defense push for high-temperature super-alloy honeycomb in hypersonics
- 4.3 Market Restraints
- 4.3.1 Moisture ingress and out-of-plane strength loss
- 4.3.2 Persistent price volatility in the aramid-paper supply chain
- 4.3.3 Limited large-format 3-D-printing capacity for complex cores
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size and Growth Forecasts (Value)
- 5.1 By Product Type
- 5.1.1 Nomen
- 5.1.2 Aluminum
- 5.1.3 Thermoplastic
- 5.1.4 Other Product Types (Paper, Super-alloy)
- 5.2 By End-user Industry
- 5.2.1 Aerospace
- 5.2.2 Defense
- 5.2.3 Marine
- 5.2.4 Other End-user Industries (Transportation, Packaging, etc.)
- 5.3 By Manufacturing Technology
- 5.3.1 Expansion
- 5.3.2 Corrugation
- 5.3.3 Extrusion/Lamination
- 5.3.4 3-D Printing/Additive Core Building
- 5.4 By Application
- 5.4.1 Composite Sandwich Panels
- 5.4.2 Non-Composite Inserts and Spacers
- 5.5 By Geography
- 5.5.1 Asia-Pacific
- 5.5.1.1 China
- 5.5.1.2 Japan
- 5.5.1.3 India
- 5.5.1.4 South Korea
- 5.5.1.5 ASEAN Countries
- 5.5.1.6 Rest of Asia-Pacific
- 5.5.2 North America
- 5.5.2.1 United States
- 5.5.2.2 Canada
- 5.5.2.3 Mexico
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Russia
- 5.5.3.7 NORDIC Countries
- 5.5.3.8 Rest of Europe
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle-East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 South Africa
- 5.5.5.3 Rest of Middle-East and Africa
- 5.5.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products and Services, Recent Developments)
- 6.4.1 Alucoil
- 6.4.2 Argosy International Inc.
- 6.4.3 Axiom Materials.
- 6.4.4 Corex Honeycomb
- 6.4.5 Corint Group
- 6.4.6 EconCore
- 6.4.7 Euro-Composites
- 6.4.8 Grigeo Group AB
- 6.4.9 Hangzhou Holycore Composite Material Co.,Ltd
- 6.4.10 Hexcel Corporation
- 6.4.11 Plascore
- 6.4.12 Schutz GmbH & Co. KGaA.
- 6.4.13 The Gill Corporation
- 6.4.14 TORAY INDUSTRIES, INC.
- 6.4.15 Tubus Bauer GmbH
- 6.4.16 Yamaton Honicore B.V.
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment
- 7.2 Bio-based and Fully Recyclable Thermoplastic Cores

