PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2122316

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2122316
Leather Chemicals - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the leather chemicals market size was valued at USD 11.02 billion in 2025 and is estimated to grow from USD 12.62 billion in 2026 to reach USD 17.03 billion by 2031, at a CAGR of 6.18% during the forecast period (2026-2031).
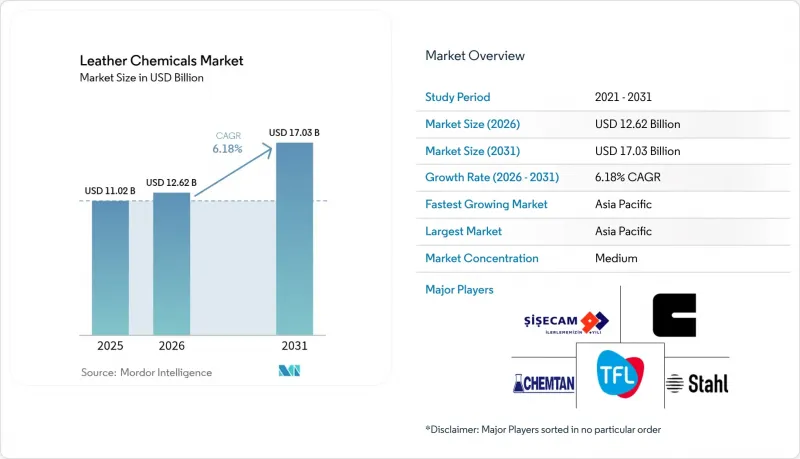
This report is Segmented by Product Type (Tanning and Dyeing Chemicals, Beam-House Chemicals, and More), Chemical Function (Chrome-Based, and More), End-User Industry (Footwear, Furniture, Automotive, Textile and Fashion, and Other End-User Industries), and Geography (Asia-Pacific, North America, Europe, South America, and Middle East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Leather Chemicals Market Trends and Insights
Surge in Chrome-Free & Metal-Free Tanning Technologies
Luxury brands and OEMs require Cr-VI below 3 ppm to comply with EU REACH Annex XVII and state regulations, prompting rapid migration to wet-white systems that combine glutaraldehyde, titanium salts, and synthetic retanning polymers. Solutions such as CLARIANT Leva and Stahl EasyWhite Tan-E eliminate chromium sludge, cut hazardous disposal costs by 40%, and shorten processing cycles by 15%. In China, the GB 30585-2014 standard spurred upgrades across Zhejiang and Guangdong hubs, while Indian and Bangladeshi SMEs face higher raw-material costs and tighter pH controls that add 12-18% to inputs.
Rapid Growth of Footwear & Textile Industries
Asia produced 5.4 billion pairs of shoes in 2024, and India's footwear output rose 9.2% in 2025, sustaining baseline demand for cost-efficient syntans and fatliquors. Vietnam and Indonesia expand capacity as China's coastal wages climb, and their tanneries adopt chrome-free lines to meet multinational supplier codes. Fashion labels increasingly specify vegetable-tanned or recycled hides, reinforcing dual demand for economical metal-free agents and premium bio-syntans.
Strict Cr-VI Emission & Wastewater Norms
EU and Chinese standards cap Cr-VI at 3-10 mg/kg, forcing chrome-based tanneries to install expensive recycling loops or pivot toward trivalent salts. India's revised effluent rules in 2025 cut TDS and BOD limits, requiring membrane bioreactors that can cost USD 1.5-3 million for mid-sized plants. Enforcement closures, such as 23 Dhaka tanneries in 2024, highlight compliance risk for fragmented clusters.
Other drivers and restraints analyzed in the detailed report include:
- Increasing Demand for Automotive & Aviation Upholstery
- Rising Preference for Bio-Based Fatliquors & Syntans
- High Energy & Effluent-Treatment Costs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Finishing chemicals delivered the fastest growth at 6.98% CAGR, even as tanning and dyeing agents retained 45.22% of the leather chemicals market share in 2025. Water-based acrylic and polyurethane topcoats now hold 62% of sales in Europe, meeting VOC caps of 50 g/m2. Digital inkjet compatibility drives incremental demand for silicone-modified top layers, enabling on-demand graphics without screen change downtime. Beam-house enzymes account for 18% of revenues, supported by protease blends that lower water use by 30% and lime 40%, vital for drought-prone clusters.
Chrome-based systems lose momentum as aldehyde-syntan packages now match shrinkage temperatures above 80°C at similar cost. Enzyme adoption accelerates in China's Zhejiang province, where a 2025 tariff hike raised municipal water charges 18%, tipping the cost-benefit scale toward biochemical processes.
Complete Report Scope:
- By Product Type
- Tanning and Dyeing Chemicals
- Beam-house Chemicals
- Finishing Chemicals
- By Chemical Function
- Chrome-based
- Chrome-free Mineral
- Synthetic Organic
- By End-user Industry
- Footwear
- Furniture
- Automotive
- Textile and Fashion
- Other End-user Industries (Heavy Leather and Saddlery, etc.)
- By Geography
- Asia-Pacific
- China
- Japan
- India
- South Korea
- ASEAN Countries
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- NORDIC Countries
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific dominated with 48.79% revenue in 2025 and will expand at 6.87% through 2031. China's GB 30585-2014 enforcement and India's subsidy scheme boost wet-white adoption, while Vietnam's 1.55 billion-pair export base draws chrome-free investments. Indonesia leverages lower wages to attract mid-tier brands, and Japan's chrome-free running-shoe policy deepens specialty demand.
In Europe and North America, Germany's Bavarian automotive cluster sources chrome-free interiors, lifting water-based finishing penetration to 78%. Tuscany's vegetable-tanning niche commands 40% price premiums, benefitting from established chestnut-extract supply chains. The United States imported 1.2 billion ft2 of finished leather in 2024, reflecting near-shoring trends to Mexico and Latin America.
In South America and the Middle East, and Africa, Brazil's 44 million hides per year feed Italian and US customers. Argentina capitalizes on low-cost bovine supply for automotive and furniture leather. Saudi Arabia invests USD 150 million to build a chrome-free cluster in Jeddah, targeting luxury autos and aviation. South Africa shifts toward enzyme-assisted processes to align with national water standards.
- AMIT
- Balmer Lawrie & Co. Ltd.
- Buckman
- Chemtan Company, Inc.
- CLARIANT
- Dyna Glycols
- DyStar Singapore Pte Ltd
- Fashion Chemicals GmbH & Co. KG
- Indofil Industries Limited.
- SCHILL+SEILACHER GMBH
- Sisecam
- Stahl Holdings B.V.
- Syn-Bios S.p.A.
- TEXAPEL S.A.
- TFL
- YILDIRIM Group Of Companies
- Zschimmer & Schwarz Chemie GmbH
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surge in chrome-free & metal-free tanning tech
- 4.2.2 Rapid growth of footwear & textile industries
- 4.2.3 Increasing demand for automotive & aviation upholstery
- 4.2.4 Rising preference for bio-based fatliquors & syntans
- 4.2.5 Enzyme-driven beam-house processes cut water 30%
- 4.3 Market Restraints
- 4.3.1 Strict Cr-VI emission & wastewater norms
- 4.3.2 High energy & effluent-treatment costs
- 4.3.3 Shift to mycelium/lab-grown leathers cuts chemical demand
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Value)
- 5.1 By Product Type
- 5.1.1 Tanning and Dyeing Chemicals
- 5.1.2 Beam-house Chemicals
- 5.1.3 Finishing Chemicals
- 5.2 By Chemical Function
- 5.2.1 Chrome-based
- 5.2.2 Chrome-free Mineral
- 5.2.3 Synthetic Organic
- 5.3 By End-user Industry
- 5.3.1 Footwear
- 5.3.2 Furniture
- 5.3.3 Automotive
- 5.3.4 Textile and Fashion
- 5.3.5 Other End-user Industries (Heavy Leather and Saddlery, etc.)
- 5.4 By Geography
- 5.4.1 Asia-Pacific
- 5.4.1.1 China
- 5.4.1.2 Japan
- 5.4.1.3 India
- 5.4.1.4 South Korea
- 5.4.1.5 ASEAN Countries
- 5.4.1.6 Rest of Asia-Pacific
- 5.4.2 North America
- 5.4.2.1 United States
- 5.4.2.2 Canada
- 5.4.2.3 Mexico
- 5.4.3 Europe
- 5.4.3.1 Germany
- 5.4.3.2 United Kingdom
- 5.4.3.3 France
- 5.4.3.4 Italy
- 5.4.3.5 Spain
- 5.4.3.6 Russia
- 5.4.3.7 NORDIC Countries
- 5.4.3.8 Rest of Europe
- 5.4.4 South America
- 5.4.4.1 Brazil
- 5.4.4.2 Argentina
- 5.4.4.3 Rest of South America
- 5.4.5 Middle East and Africa
- 5.4.5.1 Saudi Arabia
- 5.4.5.2 South Africa
- 5.4.5.3 Rest of Middle East and Africa
- 5.4.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products and Services, and Recent Developments)
- 6.4.1 AMIT
- 6.4.2 Balmer Lawrie & Co. Ltd.
- 6.4.3 Buckman
- 6.4.4 Chemtan Company, Inc.
- 6.4.5 CLARIANT
- 6.4.6 Dyna Glycols
- 6.4.7 DyStar Singapore Pte Ltd
- 6.4.8 Fashion Chemicals GmbH & Co. KG
- 6.4.9 Indofil Industries Limited.
- 6.4.10 SCHILL+SEILACHER GMBH
- 6.4.11 Sisecam
- 6.4.12 Stahl Holdings B.V.
- 6.4.13 Syn-Bios S.p.A.
- 6.4.14 TEXAPEL S.A.
- 6.4.15 TFL
- 6.4.16 YILDIRIM Group Of Companies
- 6.4.17 Zschimmer & Schwarz Chemie GmbH
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment
- 7.2 Digital leather-printing chemicals for mass-custom

