PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2122319

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2122319
Intumescent Coatings - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the intumescent coatings market size is projected to be USD 1.37 billion in 2025, USD 1.42 billion in 2026, and reach USD 1.74 billion by 2031, growing at a CAGR of 4.14% from 2026 to 2031.
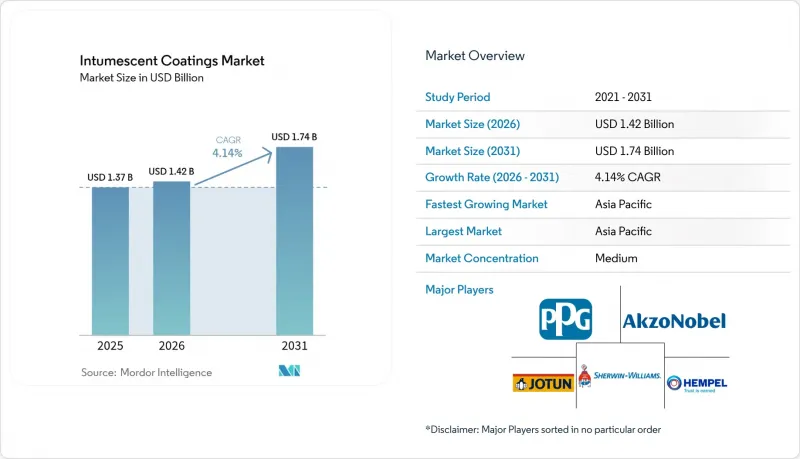
This report is Segmented by Application (Cellulosic and Hydrocarbon), Technology (Solvent-Based, Water-Based, and Epoxy-Based), Resin Type (Epoxy, Acrylic, and More), End-User Industry (Construction, Oil and Gas, Automotive and Transportation, and More), Geography (Asia-Pacific, North America, Europe, South America, and Middle East and Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Intumescent Coatings Market Trends and Insights
Accelerated High-Rise Fire Codes in Asia-Pacific
China and India now require intumescent protection for structural steel above 15 meters, a rule that covers most new urban towers and many retrofits. Singaporean and Australian standards have followed, so developers pre-qualify only suppliers that hold EN 13381 or AS 1530 approvals, raising entry barriers for smaller regional formulators. Large multinationals, therefore, consolidate shares by combining global certificates with local technical service. Market volumes also benefit when maintenance codes extend obligations to existing buildings under renovation, doubling retrofit demand without new construction.
Growth in Oil & Gas Exploration Activities
Liquefied-natural-gas terminals and petrochemical complexes across Saudi Arabia and Southeast Asia specify four-hour hydrocarbon ratings that only epoxy-based systems can meet. Capital expenditure in energy and utilities is rising, so formulators keep dual product lines for both hydrocarbon and cellulosic needs. This two-speed pattern locks high margins in upstream installations even as water-borne products gain share elsewhere. Specifiers accept higher volatile-organic-compound levels because safety codes override green-building priorities in process plants.
Epoxy Resin Price Volatility
Spot prices for bisphenol-A and epichlorohydrin moved in opposite directions during 2025, unsettling cost forecasts and complicating fixed-price bids. European anti-dumping duties on Chinese epoxy raise local procurement costs further, so only large producers with supply contracts or partial backward integration can defend margins. Smaller formulators delay R&D spending, which widens the technology gap and hastens consolidation.
Other drivers and restraints analyzed in the detailed report include:
- EU Low-VOC Mandate Boosting Water-Borne Formulations
- Modular Off-Site Steel Fabrication in North America
- Competition from Alternative Fire-Protection Methods
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Cellulosic application had a share of 53.27% in 2025, and cellulosic products compete on aesthetics and low volatile-organic-compound profiles inside commercial buildings. Suppliers that maintain dual certification for UL 1709 and EN 13381 win contracts in mixed-use industrial campuses, securing bundled warranties and simplifying procurement. Hydrocarbon systems grew faster at 5.18% CAGR because liquefied-natural-gas terminals and petrochemical plants demand four-hour protection that cellulosic coatings cannot deliver. The intumescent coatings market size for hydrocarbon projects is projected to expand steadily through 2031 as Saudi Arabia's energy construction alone reaches USD 46.5 billion.
Second-order effects reinforce divergence. Hydrocarbon coatings command higher margins because specialized resins and additives raise formulation cost, but procurement volumes are lumpy and tied to capital-expenditure cycles. Cellulosic volumes flow more consistently with residential and office construction, yet price pressure is intense. Together, these dynamics create balanced portfolio exposure for diversified producers, cushioning downturns in either sector.
Water-based coatings already control 40.36% revenue and are on a 5.44% CAGR trajectory as low-solvent mandates spread beyond Europe. The intumescent coatings market share for solvent-free epoxies increases when owners pursue green-building credits, although ambient-temperature limits still favor solvent products in cold or humid climates. Single-coat solvent-free epoxies that reach 4 millimeters dry film in one pass now reduce application steps, a key advantage in off-site fabrication. Technology choice thus hinges less on fire performance and more on job-site logistics, climate, and sustainability scoring.
Suppliers hedge by offering all three chemistries, water, solvent, and solvent-free, backed by digital tools that calculate optimal film build under project-specific heat-transfer models. Contractors then select formulations that balance schedule, environmental targets, and life-cycle cost, an approach that limits technology lock-in and keeps cross-segment competition healthy.
Complete Report Scope:
- By Application
- Cellulosic
- Hydrocarbon
- By Technology
- Solvent-Based
- Water-Based
- Epoxy Based
- By Resin Type
- Epoxy
- Acrylic
- Polyurethane
- Alkyd
- Other Resins
- By End-user Industry
- Construction
- Oil & Gas
- Automotive & Transportation
- Other End-user Industries
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Russia
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific generated 35.55% of global revenue in 2025 and leads growth at 5.86% CAGR through 2031 because tighter building codes now mandate intumescent protection in most high-rise projects. Factory-applied coatings in China's modular construction exports add a new demand stream independent of domestic housing cycles. India's retrofit obligation under SP 73:2023 further enlarges the addressable base for water-based cellulosic products.
North America's 2025 sales were lifted by a 34% surge in data-center construction and steady 5-6% gains in power-sector capital spending. Fabricators have grown into dominant buyers who expect bulk discounts and integrated digital documentation, prompting suppliers to invest in plant-floor technical teams and Building Information Modeling plugins.
Europe, the Middle East, and South America share the remaining market value. European sales favor water-borne and solvent-free epoxies because of PFAS restrictions and volatile-organic-compound caps, while anti-dumping tariffs on Asian epoxy intensify local cost inflation. Middle Eastern megaprojects valued at more than USD 1 trillion require ultra-low-solvent systems that cure in 40°C desert environments, restricting qualified suppliers to a handful of multinationals. South America remains smaller and cyclical, but Brazilian offshore investments keep a niche hydrocarbon segment intact.
- Akzo Nobel N.V.
- Albi Protective Coatings
- BASF
- Contego International Inc.
- Etex Group
- Flame-Stop Inc.
- Hempel A/S
- Hexion Inc.
- Isolatek International
- Jotun
- No-Burn, Inc.
- PPG Industries, Inc.
- RPM International Inc.
- Teknos Group
- The Sherwin-Williams Co.
- Tremco Incorporated
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Accelerated High-Rise Fire Codes in Asia-Pacific
- 4.2.2 Growth in Oil & Gas Exploration Activities
- 4.2.3 EU Low-VOC Mandate Boosting Water-Borne Formulations
- 4.2.4 Modular Off-Site Steel Fabrication in North America
- 4.2.5 Advent of Nano-Engineered Char-Formers for Ultra-Thin Films
- 4.3 Market Restraints
- 4.3.1 Epoxy Resin Price Volatility
- 4.3.2 Competition from Alternative Fire-Protection Methods
- 4.3.3 Skilled-Applicator Shortage in Emerging Markets
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Rivalry
5 Market Size & Growth Forecasts (Value)
- 5.1 By Application
- 5.1.1 Cellulosic
- 5.1.2 Hydrocarbon
- 5.2 By Technology
- 5.2.1 Solvent-Based
- 5.2.2 Water-Based
- 5.2.3 Epoxy Based
- 5.3 By Resin Type
- 5.3.1 Epoxy
- 5.3.2 Acrylic
- 5.3.3 Polyurethane
- 5.3.4 Alkyd
- 5.3.5 Other Resins
- 5.4 By End-user Industry
- 5.4.1 Construction
- 5.4.2 Oil & Gas
- 5.4.3 Automotive & Transportation
- 5.4.4 Other End-user Industries
- 5.5 By Geography
- 5.5.1 Asia-Pacific
- 5.5.1.1 China
- 5.5.1.2 India
- 5.5.1.3 Japan
- 5.5.1.4 South Korea
- 5.5.1.5 Rest of Asia-Pacific
- 5.5.2 North America
- 5.5.2.1 United States
- 5.5.2.2 Canada
- 5.5.2.3 Mexico
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Russia
- 5.5.3.6 Rest of Europe
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 South Africa
- 5.5.5.3 Rest of Middle East and Africa
- 5.5.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, Recent Developments)
- 6.4.1 Akzo Nobel N.V.
- 6.4.2 Albi Protective Coatings
- 6.4.3 BASF
- 6.4.4 Contego International Inc.
- 6.4.5 Etex Group
- 6.4.6 Flame-Stop Inc.
- 6.4.7 Hempel A/S
- 6.4.8 Hexion Inc.
- 6.4.9 Isolatek International
- 6.4.10 Jotun
- 6.4.11 No-Burn, Inc.
- 6.4.12 PPG Industries, Inc.
- 6.4.13 RPM International Inc.
- 6.4.14 Teknos Group
- 6.4.15 The Sherwin-Williams Co.
- 6.4.16 Tremco Incorporated
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment

