PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2122514

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2122514
Customer Self-Service Software - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, customer self-Service software market size in 2026 is estimated at USD 26.48 billion, growing from 2025 value of USD 22.08 billion with 2031 projections showing USD 65.66 billion, growing at 19.93% CAGR over 2026-2031.
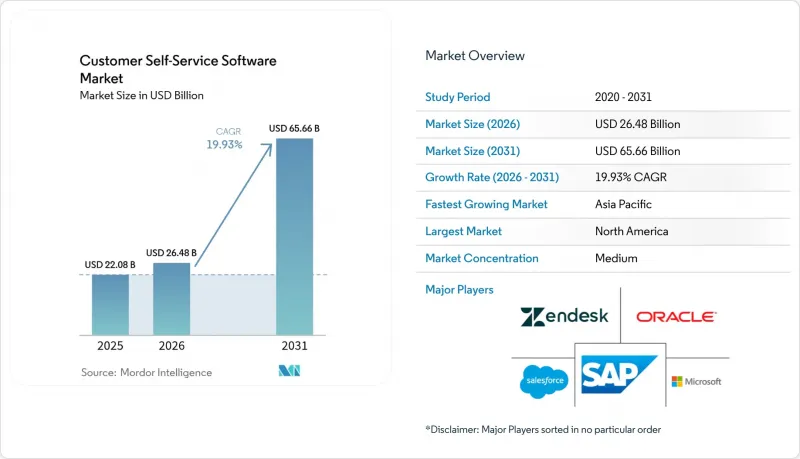
This report is Segmented by Deployment (Cloud, On-Premise, and Hybrid), Offering (Solution and Service), Channel (Web Portal, Mobile App, and More), Enterprise Size (Large Enterprises and Small and Mid-Sized Enterprises), End-User Industry (BFSI, Healthcare, Retail and E-Commerce, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Customer Self-Service Software Market Trends and Insights
Cloud-first CX Transformation Wave
Enterprises migrating to cloud-native customer experience stacks report 40-60% cost reductions and round-the-clock availability, results that encourage further investment in the customer self-service software market. Near-instant data synchronisation across touchpoints lets agents and bots access complete history, which raises first-contact resolution rates. SMEs gain the most because subscription models avoid up-front capital requirements. Nevertheless, multi-region data residency rules complicate rollouts and reward vendors with strong migration support.
AI-powered Self-service Maturity Curves
Generative AI now interprets intent, retrieves records, and executes multi-step workflows, letting automated portals resolve up to 80% of common queries. Companies that embed large language models inside ticketing flows register higher net-promoter scores and free staff to handle exceptions. As accuracy improves, the customer self-service software market will transition from handling routine FAQs to completing high-value, regulated transactions.
Fragmented API Security Standards
Mismatched token protocols and inconsistent encryption raise integration costs, slowing deployments in the customer self-service software market. Highly regulated verticals must align CRM, ERP, and knowledge-base connections under one security model, and gaps expose new vulnerability surfaces. Vendors answering this pain point with pre-certified connectors gain traction.
Other drivers and restraints analyzed in the detailed report include:
- Hyper-personalisation via Customer Data Platforms
- Rising Self-service Adoption by Gen-Z Consumers
- Data Residency Constraints in Sovereign Clouds
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The cloud segment commanded 58.20% customer self-service software market share in 2025 and is forecast to maintain a 21.68% CAGR through 2031. Its rise adds scale elasticity, enabling global releases without data-centre expansion. Subscription pricing trims up-front investment and lets finance teams recognise expenses as operating outlays. Vendors continue to enrich offerings with built-in analytics that surface deflection rates and user sentiment.
Hybrid frameworks persist where sovereignty rules block SaaS in sensitive jurisdictions, while fully on-premise stacks remain concentrated in government agencies. Firms migrating from on-premises commonly adopt phased rollouts that preserve legacy ticket records yet shift new traffic to the cloud. Lower maintenance burdens and instant patching further cement the appeal, reinforcing the customer self-service software market trajectory.
End-to-end suites held 61.65% of revenue in 2025, revealing buyer desire for unified hubs that blend knowledge bases, chatbots, and analytics. The services category will grow at 21.05% CAGR as enterprises need configuration, training, and periodic optimisation. Implementation partners craft industry playbooks that map workflows and govern role-based access, guiding firms through change-management hurdles.
Vendors extend value with packaged accelerators, pre-built templates that align to ITIL processes or retail order-status flows. Continuous-improvement engagements keep modules tuned, avoiding drift between evolving business rules and bot intents. These professional-service layers deepen platform stickiness and enlarge the customer self-service software market size attached to each deployment.
Complete Report Scope:
- By Deployment
- Cloud
- On-premise
- Hybrid
- By Offering
- Solution
- Service
- By Channel
- Web Portal
- Mobile App
- Conversational Chatbot/API
- Voice/IVR
- By Enterprise Size
- Large Enterprises
- Small and Mid-Sized Enterprises (SMEs)
- By End-user Industry
- BFSI
- Healthcare
- Retail and E-commerce
- Government
- IT and Telecommunication
- Education
- Other End-user Industries
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Chile
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Singapore
- Malaysia
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- United Arab Emirates
- Saudi Arabia
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Egypt
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America generated 33.85% of 2025 revenue, supported by high cloud penetration, mature omnichannel strategies, and a tech workforce skilled in AI model tuning. Many enterprises completed first-wave deployments and now focus on fine-tuning journeys using deeper analytics. Federal-level attention to cybersecurity nudges agencies and contractors toward platforms meeting zero-trust mandates, sustaining replacement cycles.
Asia-Pacific represents the fastest expansion vector with a projected 21.20% CAGR through 2031. Its mobile-first consumer base, dominated by Gen-Z cohorts, demands chatbots that understand local dialects and karaoke-style transliteration. Governments sponsor SME digitalisation grants, indirectly enlarging demand for the customer self-service software market across retail, travel, and banking. Vendors with multilingual NLP pipelines differentiate in these environments.
Europe advances steadily despite stringent privacy statutes. The emergence of sovereign-cloud frameworks spurs regional data-centre builds, ensuring compliance. Enterprise buyers scrutinise audit capabilities and consent management before green-lighting rollouts, effectively raising the competitive bar. Although regulatory overhead tempers speed, once solutions prove compliant, adoption spreads quickly across adjacent departments, securing long-run stability.
- Oracle Corporation
- Salesforce Inc.
- SAP SE
- Microsoft Corporation
- Zendesk Inc.
- Verint Systems Inc.
- NICE Ltd.
- Genesys Telecommunications Laboratories Inc.
- Freshworks Inc.
- ServiceNow Inc.
- Atlassian Corporation (Jira Service Management)
- HubSpot Inc.
- Intercom Inc.
- Pega Systems Inc.
- Zoho Corporation Pvt. Ltd.
- Zappix Inc.
- Ada Support Inc.
- LivePerson Inc.
- Richpanel Technologies Pvt. Ltd.
- Help Scout PBC
- Drift.com Inc.
- WalkMe Ltd.
- Kustomer LLC
- RingCentral Inc.
- Avaya Inc.
- BMC Software Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Cloud-first CX transformation wave
- 4.2.2 AI-powered self-service maturity curves
- 4.2.3 Hyper-personalisation via customer data platforms
- 4.2.4 Rising self-service adoption by Gen-Z consumers
- 4.2.5 Embedded self-service in vertical SaaS "layer-cake"
- 4.2.6 Cyber-insurance premium incentives for self-service
- 4.3 Market Restraints
- 4.3.1 Fragmented API security standards
- 4.3.2 "Quiet quit" of support agents lowering training data
- 4.3.3 Data residency constraints in sovereign clouds
- 4.3.4 Rising CX tool sprawl cost for SMEs
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Industry Attractiveness - Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUES)
- 5.1 By Deployment
- 5.1.1 Cloud
- 5.1.2 On-premise
- 5.1.3 Hybrid
- 5.2 By Offering
- 5.2.1 Solution
- 5.2.2 Service
- 5.3 By Channel
- 5.3.1 Web Portal
- 5.3.2 Mobile App
- 5.3.3 Conversational Chatbot/API
- 5.3.4 Voice/IVR
- 5.4 By Enterprise Size
- 5.4.1 Large Enterprises
- 5.4.2 Small and Mid-Sized Enterprises (SMEs)
- 5.5 By End-user Industry
- 5.5.1 BFSI
- 5.5.2 Healthcare
- 5.5.3 Retail and E-commerce
- 5.5.4 Government
- 5.5.5 IT and Telecommunication
- 5.5.6 Education
- 5.5.7 Other End-user Industries
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Chile
- 5.6.2.4 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Russia
- 5.6.3.7 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 India
- 5.6.4.3 Japan
- 5.6.4.4 South Korea
- 5.6.4.5 Singapore
- 5.6.4.6 Malaysia
- 5.6.4.7 Australia
- 5.6.4.8 Rest of Asia-Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 Middle East
- 5.6.5.1.1 United Arab Emirates
- 5.6.5.1.2 Saudi Arabia
- 5.6.5.1.3 Turkey
- 5.6.5.1.4 Rest of Middle East
- 5.6.5.2 Africa
- 5.6.5.2.1 South Africa
- 5.6.5.2.2 Nigeria
- 5.6.5.2.3 Egypt
- 5.6.5.2.4 Rest of Africa
- 5.6.5.1 Middle East
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Oracle Corporation
- 6.4.2 Salesforce Inc.
- 6.4.3 SAP SE
- 6.4.4 Microsoft Corporation
- 6.4.5 Zendesk Inc.
- 6.4.6 Verint Systems Inc.
- 6.4.7 NICE Ltd.
- 6.4.8 Genesys Telecommunications Laboratories Inc.
- 6.4.9 Freshworks Inc.
- 6.4.10 ServiceNow Inc.
- 6.4.11 Atlassian Corporation (Jira Service Management)
- 6.4.12 HubSpot Inc.
- 6.4.13 Intercom Inc.
- 6.4.14 Pega Systems Inc.
- 6.4.15 Zoho Corporation Pvt. Ltd.
- 6.4.16 Zappix Inc.
- 6.4.17 Ada Support Inc.
- 6.4.18 LivePerson Inc.
- 6.4.19 Richpanel Technologies Pvt. Ltd.
- 6.4.20 Help Scout PBC
- 6.4.21 Drift.com Inc.
- 6.4.22 WalkMe Ltd.
- 6.4.23 Kustomer LLC
- 6.4.24 RingCentral Inc.
- 6.4.25 Avaya Inc.
- 6.4.26 BMC Software Inc.
7 MARKET OPPORTUNITIES AND FUTURE TRENDS
- 7.1 White-Space and Unmet-Need Assessment

