PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2122557

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2122557
Sandwich Panels - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the sandwich panels market size is projected to be USD 15.72 billion in 2025, USD 16.52 billion in 2026, and reach USD 21.21 billion by 2031, growing at a CAGR of 5.12% from 2026 to 2031.
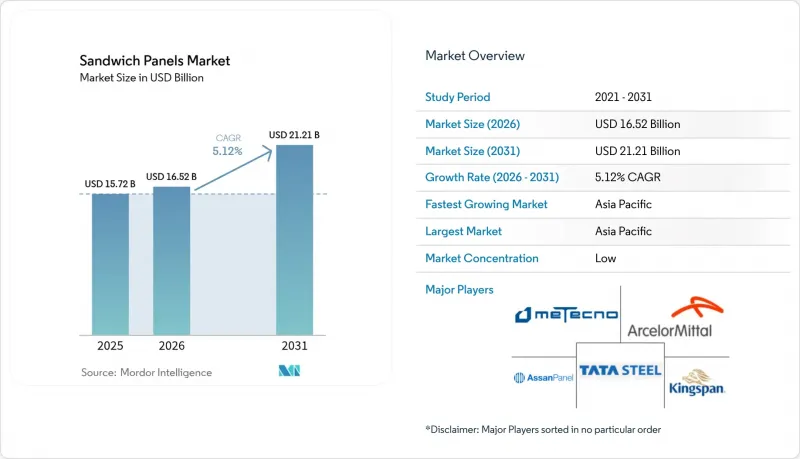
This report is Segmented by Core Material (Polyurethane, and More), Skin Material (CFRT, FRP, Aluminum, Steel, and Other Skin Materials), Technology (Continuous and Discontinuous), Application (Wall Panels, Roof Panels, Insulated Panels, and Other Applications), End-Use Sector (Residential, Commercial, and More), and Geography (Asia-Pacific, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Sandwich Panels Market Trends and Insights
Increasing Demand for PVDF-Based Aluminum Composite Panels
Designers benefit from PVDF coatings, which promise long-term color retention and enable a reduction in cladding weight, subsequently lessening seismic loads in towering structures. In Jakarta and Manila, developers achieved a reduction in structural steel by opting for PVDF-clad sandwich panels over precast concrete, all while meeting wind-load standards. Meanwhile, in the Gulf, a high solar-reflectance index for PVDF translates to cooling bill savings during peak heat. Marine locations value the resin's resistance to salt spray, boosting facade lifespans and enhancing net present value for property owners. Due to resin shortages causing a price surge for PVDF, architects now reserve its use for sunlit facades, opting for more affordable finishes on shaded sides, a strategy that maintains thermal advantages at a reduced initial expense.
Rapid Growth of Prefabricated and Modular Construction
Volumetric units, when factory-assembled, can reduce schedules and offer cost savings compared to traditional stick-built methods. Additionally, the use of modular components reduces site waste, a move that resonates well with ESG scorecards. Prefabrication is expected to grow significantly by 2026, driven primarily by labor shortages that have heightened the value of factory work. Sandwich panels, achieving tight tolerances, eliminate the need for on-site shimming and ensure air leakage remains below Passive House limits. Thanks to incentive schemes in India, modular factories are increasingly opting for R-30 cores tailored for cleanroom spaces. In China, developers are incentivized with floor-area bonuses to push beyond 50% prefabrication, leading to a surge in demand for sandwich panels, especially in tier-2 cities. With cycle times reduced, owners of data centers and cold storage facilities can sidestep revenue losses from scheduling delays, even when sandwich panels come at a premium over basic cladding.
Oriented-Strand-Board VOC Emissions
In 2025, OSB bonded with urea-formaldehyde neared CARB Phase 2's formaldehyde limit. This led to a shift towards phenolic or zero-VOC adhesives, increasing panel costs. The EU has set a stricter indoor formaldehyde cap. This effectively sidelines conventional OSB in the EU unless manufacturers undertake a reformulation and recertification process, which can extend up to 18 months. In North America, producers tackled the emissions challenge by substituting urea resins with MDI binders. However, this switch resulted in a hike in raw material costs, putting pressure on gross margins. South Korea, implementing real-time VOC monitoring and imposing hefty fines, has hastened the transition to low-emission cores. Meanwhile, Southeast Asian fabricators, primarily export-oriented, encounter fresh hurdles as multinational developers enforce CARB standards on a global scale.
Other drivers and restraints analyzed in the detailed report include:
- Energy-Efficiency Regulations for Building Envelopes
- Data-Center Boom Requiring High-Performance Envelopes
- Moisture Ingress and Long-Term Degradation in PUR/PIR Cores
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Polyurethane delivered 41.36% of 2025 revenue and is forecast to expand at 5.38%, illustrating how the sandwich panels market balances performance with first cost. PUR's lower mass helps brownfield warehouses avoid expensive foundation upgrades, and its thermal efficiency keeps panel thickness to 100 mm or less in moderate climates, saving interior space. Polyisocyanurate enjoys a better R-value per inch and resists rooftop temperatures, making it popular in the Middle-East, where roof surfaces reach high temperatures. Code changes after high-profile facade fires push schools and hospitals toward mineral wool even when budgets are tight.
Mineral-wool cores are expanding due to their A1 fire rating and acoustic attenuation. The sandwich panels market size for mineral wool in data centers and production halls is rising as insurers tighten rules around combustible cores. EPS remains critical for farm buildings because the price premium of PUR cannot be recovered in low-margin agriculture. Niche materials such as phenolic foam and vacuum-insulated panels suggest slow but steady penetration where extremely low smoke or extraordinary R-values are mandatory.
In 2025, aluminum commanded a 45.31% market share, lauded for its corrosion resistance, workability, and lightweight nature. Steel, favored for cost-sensitive applications like sheds and barns, also held a notable share. While CFRT accounted for a modest portion of the 2025 revenue, it boasted a 5.27% CAGR, the market's fastest growth rate. This surge is attributed to lifecycle assessments highlighting CFRT's lower embodied carbon compared to aluminum. Even with a higher price tag than coated steel, clients pursuing net-zero certifications are increasingly opting for CFRT.
Fiberglass skins play a crucial role in the food and pharmaceutical sectors, where their non-porous surface simplifies sanitation. Meanwhile, exotic metals like copper and zinc cater to luxury facades and environments with extreme chemical exposure due to their heightened corrosion resistance. With the updated EU CSRD mandating Scope 3 disclosures starting in 2025, developers are turning to CFRT to potentially slash reported emissions. This strategic move is anticipated to dent aluminum's market share in the coming years.
Complete Report Scope:
- By Core Material
- Polyurethane (PUR)
- Polyisocyanurate (PIR)
- Mineral Wool
- Expanded Polystyrene (EPS)
- Other Core Materials
- By Skin Material
- Continuous Fiber Reinforced Thermoplastics (CFRT)
- Fiberglass Reinforced Panel (FRP)
- Aluminum
- Steel
- Other Skin Materials
- By Technology
- Continuous
- Discontinuous
- By Application
- Wall Panels
- Roof Panels
- Insulated Panels
- Other Applications
- By End-use Sector
- Residential
- Commercial
- Industrial
- Institutional and Infrastructure
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- Italy
- France
- Spain
- Poland
- NORDIC Countries
- Hungary
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific delivered 49.90% of global revenue in 2025 and will climb at a 5.81% CAGR. This growth is largely driven by China's goal to prefabricate a portion of its new constructions by 2030 and India's push for electronics factories. In 2025, a notable percentage of the new industrial floor area in Chinese provinces utilized sandwich panels, indicating swift policy adoption. India constructed a substantial amount of Grade A warehouses in 2025, with a significant portion featuring insulated boxes that align with Global Cold Chain Alliance standards. Japan and South Korea made up a considerable share of the region's revenue, while aging workforces in these nations are pushing for more labor-saving solutions. Southeast Asia experienced growth as manufacturers shifted operations from China, though ASEAN's import tariffs on steel and aluminum have extended lead times.
North America accounted for a notable share of global sales in 2025, with steady growth. U.S. e-commerce warehouses expanded significantly, and a considerable percentage of high bay facilities over a certain size opted for panels in their construction. In Canada, a stricter code in 2025 has hastened the adoption of these panels in prairie cold rooms. Mexico's growth can be attributed to USMCA regulations promoting nearshoring, with new automotive plants opting for LEED-eligible designs.
Europe, contributing a significant share to global sales, is on a steady rise. Volatility in natural gas prices has led factories to retrofit with thicker panels, achieving a notable reduction in heating loads. Germany and Poland, bolstered by battery cell plants currently under construction, cater to a considerable portion of Europe's demand. The Nordic states, witnessing growth, are seeing a surge in hydrogen projects that necessitate airtightness due to extreme cold.
South America, with a notable share of global revenue, is growing steadily. Brazil established numerous cold storage facilities for protein exports, with a significant portion utilizing 180 mm PIR cores. Meanwhile, Argentina's mining surge is prompting rapid constructions that prioritize quick-install envelopes. The Middle-East and Africa, holding a notable share, are experiencing significant growth, spearheaded by Saudi NEOM and the UAE's industrial zones, both aiming for LEED Gold standards in arid conditions.
- Alubel
- ArcelorMittal
- Areco
- Assan Panel A.S.
- Building Component Solutions LLC
- Cornerstone Building Brands, Inc.
- DANA Group of Companies
- EPACK Prefab
- Isopan
- Jiangsu Jingxue Energy Saving Technology Co., Ltd.
- Kingspan Group
- Lattonedil
- Marcegaglia Steel S.p.A.
- Metecno Group
- NAV SYSTEM
- Rautaruukki Corporation
- Romakowski GmbH and Co. KG
- Sintex
- Structural Panels
- Tata Steel
- Teknopanel
- Tonmat Group
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Increasing demand for PVDF-based aluminium composite panels
- 4.2.2 Rapid growth of prefabricated and modular construction
- 4.2.3 Energy-efficiency regulations for building envelopes
- 4.2.4 Data-centre boom requiring high-performance envelopes
- 4.2.5 Green-hydrogen gigafactories driving demand for climate-controlled production halls
- 4.3 Market Restraints
- 4.3.1 Oriented-strand-board VOC emissions
- 4.3.2 Moisture ingress and long-term degradation in PUR/PIR cores
- 4.3.3 Volatility in MDI, steel and aluminium prices squeezing panel margins
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Bargaining Power of Suppliers
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Threat of New Entrants
- 4.5.4 Threat of Substitute Products and Services
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Value)
- 5.1 By Core Material
- 5.1.1 Polyurethane (PUR)
- 5.1.2 Polyisocyanurate (PIR)
- 5.1.3 Mineral Wool
- 5.1.4 Expanded Polystyrene (EPS)
- 5.1.5 Other Core Materials
- 5.2 By Skin Material
- 5.2.1 Continuous Fiber Reinforced Thermoplastics (CFRT)
- 5.2.2 Fiberglass Reinforced Panel (FRP)
- 5.2.3 Aluminum
- 5.2.4 Steel
- 5.2.5 Other Skin Materials
- 5.3 By Technology
- 5.3.1 Continuous
- 5.3.2 Discontinuous
- 5.4 By Application
- 5.4.1 Wall Panels
- 5.4.2 Roof Panels
- 5.4.3 Insulated Panels
- 5.4.4 Other Applications
- 5.5 By End-use Sector
- 5.5.1 Residential
- 5.5.2 Commercial
- 5.5.3 Industrial
- 5.5.4 Institutional and Infrastructure
- 5.6 By Geography
- 5.6.1 Asia-Pacific
- 5.6.1.1 China
- 5.6.1.2 India
- 5.6.1.3 Japan
- 5.6.1.4 South Korea
- 5.6.1.5 Rest of Asia-Pacific
- 5.6.2 North America
- 5.6.2.1 United States
- 5.6.2.2 Canada
- 5.6.2.3 Mexico
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 Italy
- 5.6.3.4 France
- 5.6.3.5 Spain
- 5.6.3.6 Poland
- 5.6.3.7 NORDIC Countries
- 5.6.3.8 Hungary
- 5.6.3.9 Rest of Europe
- 5.6.4 South America
- 5.6.4.1 Brazil
- 5.6.4.2 Argentina
- 5.6.4.3 Rest of South America
- 5.6.5 Middle-East and Africa
- 5.6.5.1 Saudi Arabia
- 5.6.5.2 South Africa
- 5.6.5.3 Rest of Middle-East and Africa
- 5.6.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global Overview, Market Overview, Core Segments, Financials, Strategic Information, Products and Services, Recent Developments)
- 6.4.1 Alubel
- 6.4.2 ArcelorMittal
- 6.4.3 Areco
- 6.4.4 Assan Panel A.S.
- 6.4.5 Building Component Solutions LLC
- 6.4.6 Cornerstone Building Brands, Inc.
- 6.4.7 DANA Group of Companies
- 6.4.8 EPACK Prefab
- 6.4.9 Isopan
- 6.4.10 Jiangsu Jingxue Energy Saving Technology Co., Ltd.
- 6.4.11 Kingspan Group
- 6.4.12 Lattonedil
- 6.4.13 Marcegaglia Steel S.p.A.
- 6.4.14 Metecno Group
- 6.4.15 NAV SYSTEM
- 6.4.16 Rautaruukki Corporation
- 6.4.17 Romakowski GmbH and Co. KG
- 6.4.18 Sintex
- 6.4.19 Structural Panels
- 6.4.20 Tata Steel
- 6.4.21 Teknopanel
- 6.4.22 Tonmat Group
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-Need Assessment

