PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2122758

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2122758
Pharmacy Management System - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, pharmacy management system market size in 2026 is estimated at USD 116.45 billion, growing from 2025 value of USD 101.07 billion with 2031 projections showing USD 236.28 billion, growing at 15.22% CAGR over 2026-2031.
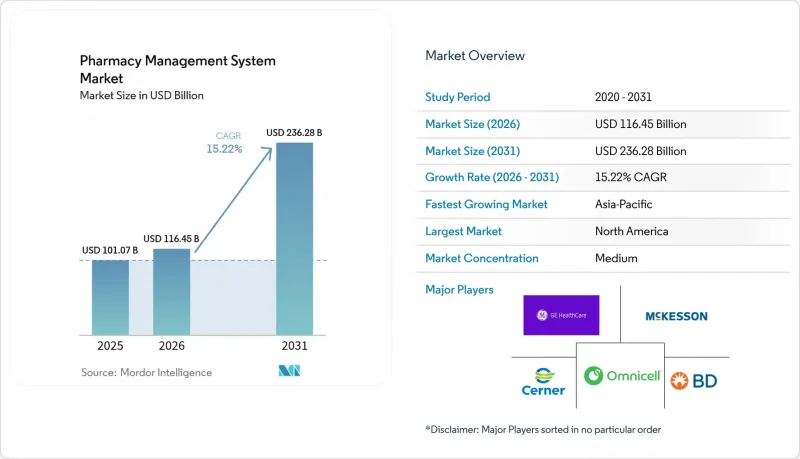
This report is Segmented by Component (Solutions, Services), Deployment (Cloud-Based, On-Premise), Organisation Size (Independent Pharmacies, Chained Pharmacies), End-User Industries (Hospital Pharmacies, Retail/Community Pharmacies, and More), and Geography (North America, South America, Europe, APAC, Middle East, Africa). The Market Forecasts are Provided in Terms of Value (USD).
Global Pharmacy Management System Market Trends and Insights
Rising Prescription Volumes Burdening Pharmacists
Prescription drug spend in the United States rose at 10-12% during 2024, with GLP-1 anti-obesity agents responsible for more than 80% of incremental revenue, intensifying daily dispensing pressure. Surveys show 61% of Americans now consider pharmacies appropriate sites for primary care, stretching pharmacist duties into counseling and vaccination. Independent outlets feel the strain most, with one closing each day in 2023 because reimbursement cuts and manual workflows eroded profits. Automated dispensing and clinical documentation modules inside the pharmacy management system market remove repetitive tasks, letting pharmacists focus on higher-value services. Providers that adopt advanced workflow engines report fewer errors and shorter wait times, improving patient loyalty.
Rapid Shift Toward Cloud-Hosted Pharmacy Platforms
Eighty-three percent of pharmaceutical organizations already keep core workloads in the cloud, and the sector's cloud spending is forecast to climb to USD 59.37 billion by 2030. Cloud architectures support real-time data synchronization across chains with thousands of branches, a feat that on-premise servers struggle to match. Demand intensified during the COVID-19 pandemic when remote log-ons and elastic capacity became operational necessities, not optional perks. Modern cloud vendors also certify against regional privacy frameworks, lowering concerns over data sovereignty that once delayed adoption. As subscription pricing aligns IT cost with prescription volume, even single-site independents enter the pharmacy management system market to access enterprise-grade analytics without capital outlays.
Vendor Lock-in with Legacy Vendors
Large health systems often rely on bespoke builds that weave dispensing, billing, and formulary data into proprietary formats; switching vendors can cost millions and demand months of retraining . Independent outlets face different barriers, such as limited IT staff and fear of downtime that threaten fragile cash flows. Consolidation can deepen lock-in when an acquirer phases out open APIs, as observers noted after BD paid USD 1.548 billion for Parata Systems in 2024. Cloud newcomers gradually erode these obstacles by offering migration utilities and pay-as-you-grow terms, yet full transition remains protracted while legacy contracts run their course.
Other drivers and restraints analyzed in the detailed report include:
- Stringent Global Medication-Safety Regulations
- Cost-Savings from AI-Led Inventory Optimisation
- Escalating Cyber-Security and Privacy Concerns
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Solutions products generated 66.90% of the pharmacy management system market size in 2025, reflecting the non-negotiable need for e-prescription processing, inventory control, and compliance tracking. The segment's built-in clinical checks and automated financial reconciliation guard against errors that can spark regulatory fines. Hospitals and chains deploy multi-module suites so pharmacists practice at the top of license while systems handle repetitive inputs. Growth in services, expected at 16.05% CAGR to 2031, shows users increasingly seek configuration, staff training, and managed hosting once the base software is live.
The services wave signals a maturing marketplace in which optimization extends long after go-live. Pharmacies demand analytics tuning, security patching, and workflow redesign as new reimbursement rules arrive. Consultants embed benchmark dashboards that compare fill rates, wait times, and payer mix across branches, helping operators defend margin. Vendors that blend software and advisory support position themselves for stickier revenue streams, deepening share within the pharmacy management system market.
Cloud installations owned 62.85% share in 2025 and will post the fastest 17.18% CAGR through 2031, underscoring how elasticity, lower upfront cost, and seamless updates outweigh the comfort of on-premise hardware. Chains favor cloud to standardize data across hundreds of outlets, while independents welcome subscription models that convert capital expenditure into operating cost.
On-premise footprints shrink as cyber-risk mitigation, redundancy, and maintenance demand skills that small IT teams cannot supply. Compliance auditors now rate cloud systems higher because vendors maintain hardened environments certified under multiple frameworks. The pivot enhances real-time collaboration among prescribers, payers, and pharmacists, deepening adoption of the pharmacy management system market across geographies.
Complete Report Scope:
- By Component
- Solutions
- Inventory Management
- Purchase Order Management
- Supply-Chain Management
- Regulatory and Compliance Information
- Clinical and Administrative Performance
- Other Solutions
- Services
- Solutions
- By Deployment
- Cloud-based
- On-premise
- By Organisation Size
- Independent Pharmacies
- Chained Pharmacies
- By End-User Industries
- Hospital Pharmacies
- Retail/Community Pharmacies
- Long-term-care and Specialty Pharmacies
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- United Kingdom
- Germany
- France
- Italy
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia-Pacific
- Middle East
- Israel
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America's dominance rests on mature insurance markets, sizable chain footprints, and regulators that mandate electronic checks at every dispense. U.S. initiatives to combat opioid misuse spur uptake of real-time prescription monitoring, while Canada's universal coverage highlights the need for cost-efficient refill coordination. Recent DEA alerts about EHR fraud accelerate investments in audit trails and multifactor authentication. Venture funding also flows into AI start-ups that promise workflow relief, widening the technology gap between modern and legacy stores.
Asia-Pacific records the fastest trajectory as China, India, and Indonesia upgrade primary-care delivery and digitize supply chains. National e-health blueprints channel subsidies into cloud-ready software so rural clinics share records with urban hospitals. Japan's rapidly aging population sharpens focus on medication adherence apps that integrate with dispensing platforms. Multinational chains entering Southeast Asia insist on enterprise systems that mirror their Western operations, fueling demand within the pharmacy management system market.
Europe sits between these extremes. Harmonized EMA guidelines push pharmacies to track serial numbers and report adverse events uniformly across borders. Brexit introduces extra customs documentation, encouraging British outlets to automate replenishment and regulatory filings. Scandinavian markets, long early adopters of e-prescription, now upgrade to AI-enabled forecasting that offsets higher labor costs. Throughout the continent, privacy regulations such as GDPR favor vendors that offer fine-grained consent management.
- McKesson Corporation
- Omnicell, Inc.
- Cerner Corporation
- Becton, Dickinson and Company
- GE HealthCare Technologies Inc.
- Talyst Systems, LLC
- Epicor Software Corporation
- Allscripts Healthcare Solutions, Inc.
- ACG Infotech Ltd.
- Clanwilliam Health Ltd.
- DATASCAN (DCS Pharmacy, Inc.)
- GlobeMed Ltd.
- Health Business Systems, Inc.
- Idhasoft Ltd.
- MedHOK, Inc.
- PioneerRx, LLC
- QS/1 Data Systems, LLC (RedSail Technologies)
- ScriptPro LLC
- Liberty Software, Inc.
- Computer-Rx, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising prescription volumes burdening pharmacists
- 4.2.2 Rapid shift toward cloud-hosted pharmacy platforms
- 4.2.3 Stringent global medication-safety regulations
- 4.2.4 Cost-savings from AI-led inventory optimisation
- 4.2.5 Integration of pharmacogenomics modules
- 4.2.6 Expansion of tele-pharmacy services
- 4.3 Market Restraints
- 4.3.1 Vendor lock-in with legacy vendors
- 4.3.2 Escalating cyber-security and privacy concerns
- 4.3.3 High upfront automation capital cost
- 4.3.4 FHIR interoperability gaps with next-gen EHRs
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors
- 4.9 Investment Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUE, USD)
- 5.1 By Component
- 5.1.1 Solutions
- 5.1.1.1 Inventory Management
- 5.1.1.2 Purchase Order Management
- 5.1.1.3 Supply-Chain Management
- 5.1.1.4 Regulatory and Compliance Information
- 5.1.1.5 Clinical and Administrative Performance
- 5.1.1.6 Other Solutions
- 5.1.2 Services
- 5.1.1 Solutions
- 5.2 By Deployment
- 5.2.1 Cloud-based
- 5.2.2 On-premise
- 5.3 By Organisation Size
- 5.3.1 Independent Pharmacies
- 5.3.2 Chained Pharmacies
- 5.4 By End-User Industries
- 5.4.1 Hospital Pharmacies
- 5.4.2 Retail/Community Pharmacies
- 5.4.3 Long-term-care and Specialty Pharmacies
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 United Kingdom
- 5.5.2.2 Germany
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 South Korea
- 5.5.3.5 Rest of Asia-Pacific
- 5.5.4 Middle East
- 5.5.4.1 Israel
- 5.5.4.2 Saudi Arabia
- 5.5.4.3 United Arab Emirates
- 5.5.4.4 Turkey
- 5.5.4.5 Rest of Middle East
- 5.5.5 Africa
- 5.5.5.1 South Africa
- 5.5.5.2 Egypt
- 5.5.5.3 Rest of Africa
- 5.5.6 South America
- 5.5.6.1 Brazil
- 5.5.6.2 Argentina
- 5.5.6.3 Rest of South America
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 McKesson Corporation
- 6.4.2 Omnicell, Inc.
- 6.4.3 Cerner Corporation
- 6.4.4 Becton, Dickinson and Company
- 6.4.5 GE HealthCare Technologies Inc.
- 6.4.6 Talyst Systems, LLC
- 6.4.7 Epicor Software Corporation
- 6.4.8 Allscripts Healthcare Solutions, Inc.
- 6.4.9 ACG Infotech Ltd.
- 6.4.10 Clanwilliam Health Ltd.
- 6.4.11 DATASCAN (DCS Pharmacy, Inc.)
- 6.4.12 GlobeMed Ltd.
- 6.4.13 Health Business Systems, Inc.
- 6.4.14 Idhasoft Ltd.
- 6.4.15 MedHOK, Inc.
- 6.4.16 PioneerRx, LLC
- 6.4.17 QS/1 Data Systems, LLC (RedSail Technologies)
- 6.4.18 ScriptPro LLC
- 6.4.19 Liberty Software, Inc.
- 6.4.20 Computer-Rx, Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment

