PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2122759

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2122759
Metrology Software - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the metrology software market size in 2026 is estimated at USD 1.74 billion, growing from 2025 value of USD 1.58 billion with 2031 projections showing USD 2.86 billion, growing at 10.38% CAGR over 2026-2031.
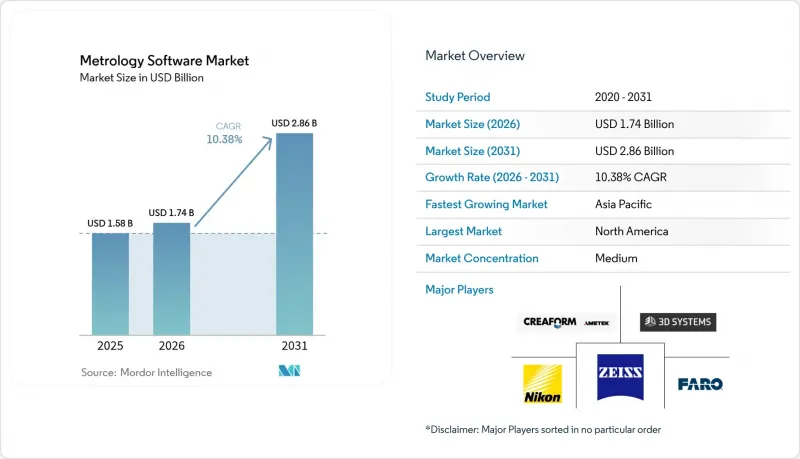
This report is Segmented by End-User Vertical (Automotive, Aerospace, and More), Deployment Model (On-Premise, and Cloud-Based), Application (Reverse Engineering, Tool and Die Manufacturing, and More), Measurement Device Type (Optical Digitizers and Scanners, Portable Arms, Laser Trackers, Structured Light Scanners, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Metrology Software Market Trends and Insights
Rising Automation in Discrete and Process Manufacturing
Manufacturers invest in automated inspection cells that merge programmable logic controllers with metrology software, creating closed-loop quality control that cuts scrap by up to 25% in automotive body panels. Coordinate measuring machines, optical scanners, and industrial robots communicate through standardized protocols, enabling round-the-clock operations. Electronics assemblers transition to lights-out production, relying on automated deviation alerts to correct tool offsets before defects propagate. Semiconductor producers embed dimensional data into advanced process control, driving continuous parametric tuning. Software vendors respond with modular application programming interfaces that simplify hardware integration and shorten installation timelines.
Demand for High Quality and Zero-Defect Products
Medical device and aerospace suppliers embed statistical process control within metrology platforms to detect micrometer-level drift before components enter final assembly, averting costly recalls. Electric vehicle battery plants trace every electrode dimension back to the cell barcode, ensuring compliance with functional safety rules while minimizing rework budgets. The adoption of Six Sigma disciplines elevates measurement data analytics from an optional add-on to a core manufacturing requirement. Tier-one automotive suppliers report warranty cost reductions when software-driven inspections replace manual gauges. Strict supplier scorecards encourage downstream adoption, spreading metrology software into stamping, casting, and molding sub-tiers.
High Initial Cost and Integration Complexity
Bundling licenses, calibration fixtures, and project engineering quickly escalates budgets for small manufacturers, deterring adoption despite productivity gains. Integration projects often exceed original timelines when legacy gauges require custom drivers. Consultants bill additional hours to harmonize data formats, elevating the total cost of ownership. Companies also incur indirect costs associated with training operators during the ramp-up period. Return on investment assessments remain challenging when manual inspection already meets customer tolerance targets, leading to hesitant procurement cycles.
Other drivers and restraints analyzed in the detailed report include:
- Shift Toward Cloud-Based Metrology Platforms
- Integration With Industry 4.0 Digital Twins
- Shortage of Skilled Metrology Software Professionals
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The medical category is expected to account for a 10.55% CAGR through 2031, while the automotive domain is projected to retain a 39.25% market share of metrology software in 2025. Acute regulatory oversight requires validated audit trails, which only specialized platforms can deliver. Implant miniaturization drives upgrades to coordinate measuring machines for sub-micrometer accuracy. Aerospace continues to rely on large-volume laser tracker setups that map fuselage joins in situ. Energy projects utilize metrology software for wind blade aerodynamics, leveraging edge analytics to analyze vibration data.
Growth in road vehicles stabilizes, yet battery cell lines demand new analytics that predict volume expansion and electrode misalignment. Electronics assemblers integrate optical digitizers within automated optical inspection to verify surface-mount component coplanarity at scale. Consumer goods producers are starting to migrate from sample-based checks to 100% in-line inspection as brand protection strategies become increasingly stringent. Over the forecast horizon, medical innovation in personalized implants is expected to sustain premium licensing, reinforcing the shift toward software that supports continuous validation.
Cloud deployments reached an 11.35% CAGR, eroding on-premise dominance that represented 68.60% of the metrology software market size in 2025. Multinationals employ hybrid strategies that retain sensitive datasets on-site while moving non-classified analyses to managed environments. Subscription pricing converts capital expenditures into operating expenses, appealing to small enterprises that lack server budgets. Vendor-operated infrastructure offloads patch management, shortening vulnerability windows. Nevertheless, defense and nuclear segments still favor air-gapped installations, ensuring niche demand for on-premise sales.
Edge nodes now perform time-critical calculations adjacent to production lines, forwarding only the results to the cloud for trend analysis. This architecture satisfies latency thresholds without compromising central visibility. Machine learning models trained in the cloud return optimized sampling patterns to edge devices, boosting throughput without hardware upgrades. As cybersecurity certifications mature, audit departments become more comfortable with distributed architectures, bolstering expansion across regulated verticals.
Complete Report Scope:
- By End-User Vertical
- Automotive
- Aerospace
- Electronics Manufacturing
- Energy and Power
- Medical Devices
- Other End-User Verticals
- By Deployment Model
- On-Premise
- Cloud-Based
- By Application
- Quality Control and Inspection
- Reverse Engineering
- Tool and Die Manufacturing
- Virtual Simulation and Digital Twin
- Large-Volume Metrology
- By Measurement Device Type
- Coordinate Measuring Machines (CMM)
- Optical Digitizers and Scanners
- Portable Arms
- Laser Trackers
- Structured Light Scanners
- Other Measurement Device Types
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- Middle East
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America held a 33.10% market share of the metrology software market in 2025, owing to its mature aerospace, automotive, and medical manufacturing clusters that demand validated measurement workflows. Federal initiatives encouraging reshoring promote capital investment in smart quality systems, while ongoing artificial intelligence research accelerates the adoption of predictive analytics. Cloud providers headquartered in the region offer compliance-ready environments, easing the migration process for multi-site manufacturers. Export-oriented suppliers leverage metrology data to support global customer audits, sustaining software update cycles.
Asia Pacific grew fastest at 10.62% CAGR, propelled by China's shift toward high-value production and India's escalating precision engineering exports. Semiconductor fabs across Taiwan and mainland China deploy automated optical metrology in sub-10 nm processes, mandating real-time analytics. Japan's advanced robotics sector embeds measurement feedback within assembly cells to enhance uptime. South Korean shipbuilders utilize large-volume laser trackers to align hull blocks, thereby improving fit accuracy and reducing dry-dock delays. Regional governments subsidize Industry 4.0 pilots, catalyzing the adoption of Industry 4.0 among small manufacturers in Vietnam, Thailand, and Malaysia.
Europe sustains steady growth, anchored by automotive electrification and stringent environmental standards that require lifecycle measurement traceability. German machine tool builders integrate metrology software inside control loops, exporting turnkey precision lines worldwide. The United Kingdom's aerospace composites sector demands non-contact inspection for complex curves, spurring scanner innovation. Data protection regulations influence cloud architecture, prompting vendors to shift toward European data centers with stringent access controls. Circular economy targets create secondary demand for remanufacturing inspection modules that certify reusable components.
- Nikon Metrology NV
- 3D Systems Corporation
- Creaform Inc. (AMETEK Inc.)
- FARO Technologies Inc.
- Carl Zeiss AG
- Hexagon AB
- LK Metrology Ltd.
- Renishaw plc
- Perceptron Inc. (Atlas Copco AB)
- InnovMetric Software Inc.
- Fluke Corporation
- Metrologic Group SA (Sandvik AB)
- Autodesk Inc.
- Dassault Systemes SE
- Verisurf Software Inc.
- Mapvision Ltd.
- GOM GmbH (Carl Zeiss AG)
- Capture 3D LLC
- Stratasys Ltd. (Control Software)
- Software Point Oy
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Automation in Discrete and Process Manufacturing
- 4.2.2 Demand for High Quality and Zero-Defect Products
- 4.2.3 Shift Toward Cloud-Based Metrology Platforms
- 4.2.4 Integration With Industry 4.0 Digital Twins
- 4.2.5 Adoption in Additive Manufacturing Quality Assurance
- 4.2.6 LiDAR and Radar Calibration Needs in Autonomous Vehicles
- 4.3 Market Restraints
- 4.3.1 High Initial Cost and Integration Complexity
- 4.3.2 Shortage of Skilled Metrology Software Professionals
- 4.3.3 Limited Interoperability With Legacy Measurement Hardware
- 4.3.4 Cybersecurity Concerns in Cloud Deployments
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of Macroeconomic Factors
- 4.8 Assessment of the Impact of COVID-19 on the Industry
- 4.9 Porter's Five Forces Analysis
- 4.9.1 Threat of New Entrants
- 4.9.2 Bargaining Power of Buyers
- 4.9.3 Bargaining Power of Suppliers
- 4.9.4 Threat of Substitute Products
- 4.9.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By End-User Vertical
- 5.1.1 Automotive
- 5.1.2 Aerospace
- 5.1.3 Electronics Manufacturing
- 5.1.4 Energy and Power
- 5.1.5 Medical Devices
- 5.1.6 Other End-User Verticals
- 5.2 By Deployment Model
- 5.2.1 On-Premise
- 5.2.2 Cloud-Based
- 5.3 By Application
- 5.3.1 Quality Control and Inspection
- 5.3.2 Reverse Engineering
- 5.3.3 Tool and Die Manufacturing
- 5.3.4 Virtual Simulation and Digital Twin
- 5.3.5 Large-Volume Metrology
- 5.4 By Measurement Device Type
- 5.4.1 Coordinate Measuring Machines (CMM)
- 5.4.2 Optical Digitizers and Scanners
- 5.4.3 Portable Arms
- 5.4.4 Laser Trackers
- 5.4.5 Structured Light Scanners
- 5.4.6 Other Measurement Device Types
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Russia
- 5.5.2.5 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 South Korea
- 5.5.3.5 Australia
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 Middle East
- 5.5.4.1.1 Saudi Arabia
- 5.5.4.1.2 United Arab Emirates
- 5.5.4.1.3 Rest of Middle East
- 5.5.4.2 Africa
- 5.5.4.2.1 South Africa
- 5.5.4.2.2 Egypt
- 5.5.4.2.3 Rest of Africa
- 5.5.4.1 Middle East
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share, Products and Services, and Recent Developments)
- 6.4.1 Nikon Metrology NV
- 6.4.2 3D Systems Corporation
- 6.4.3 Creaform Inc. (AMETEK Inc.)
- 6.4.4 FARO Technologies Inc.
- 6.4.5 Carl Zeiss AG
- 6.4.6 Hexagon AB
- 6.4.7 LK Metrology Ltd.
- 6.4.8 Renishaw plc
- 6.4.9 Perceptron Inc. (Atlas Copco AB)
- 6.4.10 InnovMetric Software Inc.
- 6.4.11 Fluke Corporation
- 6.4.12 Metrologic Group SA (Sandvik AB)
- 6.4.13 Autodesk Inc.
- 6.4.14 Dassault Systemes SE
- 6.4.15 Verisurf Software Inc.
- 6.4.16 Mapvision Ltd.
- 6.4.17 GOM GmbH (Carl Zeiss AG)
- 6.4.18 Capture 3D LLC
- 6.4.19 Stratasys Ltd. (Control Software)
- 6.4.20 Software Point Oy
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

