PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2122772

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2122772
Coronary Stent - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, coronary stents market size in 2026 is estimated at USD 8.66 billion, growing from 2025 value of USD 8.29 billion with 2031 projections showing USD 10.75 billion, growing at 4.42% CAGR over 2026-2031.
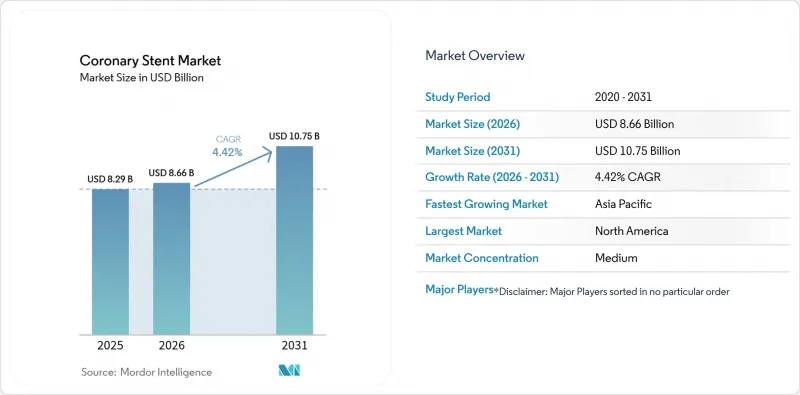
This report is Segmented by Product Type (Drug Eluting Stent, Bare Metal Coronary Stent, and More), Biomaterial (Metallic, Polymeric and More), Mode of Delivery (Balloon-Expandable Stent and Self-Expanding Stent), End User (Hospitals, Ambulatory Surgical Centers and More), and Geography (North America, Europe, Asia-Pacific, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Coronary Stent Market Trends and Insights
Rising Prevalence of CAD and Aging Population
Cardiovascular disease incidence continues climbing as populations age and metabolic syndrome becomes widespread, pushing steady demand for interventions in the coronary stents market. Diabetes now appears in roughly one quarter of PCI cases, and dedicated stent designs for hyperglycemic patients demonstrate lower restenosis. Higher life expectancy means more multivessel disease presentations that once were managed conservatively. Payers see upfront stenting as a cost-saving alternative to repeat hospitalization, prompting policy support. Emerging economies feel the shift faster because urban lifestyles compress disease onset timelines. All these factors combine to maintain a robust pipeline of eligible patients through 2030.
Shift Toward Early PCI in Acute Coronary Syndrome Guidelines
Guideline committees increasingly support immediate revascularization, reflected in PREVENT showing target-vessel failure of 0.4% when preventive PCI accompanies medical therapy. This stance coexists with nuanced evidence from ISCHEMIA, so clinicians rely on risk stratification algorithms to balance mortality and quality of life. Urgent cases are typically complex, favoring premium devices with improved deliverability. Stable disease volumes may plateau, but acute interventions grow, creating a predictable product mix. Manufacturers fine-tune supply chains for rapid response to emergent demand.
Price Caps and Centralized Procurement Squeezing ASPs
Regulated pricing stripped 85-90% from drug-eluting stent tags in India and China, forcing distributors out of the chain and compressing margins. Volume increases only partially offset revenue declines, prompting factories to automate and relocate. Premium technologies see disproportionate pressure, challenging ROI calculations on next-generation platforms. Worldwide buyers now cite Asian benchmarks to negotiate, creating sustained deflation in the coronary stents market.
Other drivers and restraints analyzed in the detailed report include:
- Rapid Uptake of Ultrathin-Strut & Biodegradable-Polymer DES
- Integration of AI-Guided Imaging & Sizing Tools
- Safety Signals Around Late Scaffold Thrombosis in BVS
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Drug-eluting stents generated 75.64% of revenue in 2025, establishing the largest share of the coronary stents market. The segment benefits from a continuous flow of data supporting low restenosis and thrombosis rates with ever thinner struts. Competition now focuses on polymer chemistry, drug kinetics, and radial strength, areas that expand margins even under price pressure. Bioabsorbable vascular scaffolds, while only a fraction of sales today, record a 7.52% CAGR through 2031 as safety profiles improve. Recent trials like INFINITY-SWEDEHEART that showed 0.6% target-vessel failure for DynamX bioadaptor validate renewed clinical confidence.
Next-generation BVS seek to merge temporary scaffolding with the radial performance of metals. Regulatory acceptance widens indications beyond coronary arteries into peripheral territories, such as Abbott's Esprit BTK receiving FDA nod for below-the-knee lesions. This broadens platform potential, spurring incremental R&D. Meanwhile, bare-metal stents retain utility in scenarios needing short antiplatelet regimens, and dual-therapy stents address high bleeding-risk patients. The varied lineup allows physicians to tailor therapy rather than apply a one-size-fits-all approach.
Metallic designs controlled 67.10% of sales in 2025, reflecting physician preference for cobalt-chromium and platinum-chromium alloys that deliver strong radial support. Advances in metallurgy enable 60-micrometer struts without compromising fatigue resistance, meeting demand for high deliverability. Polymeric scaffolds, though smaller today, are gaining at an 7.91% CAGR as biocompatible materials alleviate chronic inflammation. Boston Scientific's SYNERGY bioabsorbable-polymer DES demonstrated low thrombosis in a pooled cohort of 18,000 patients, bolstering payer confidence.
Research into recombinant collagen type III coatings shows promise in eliminating drug dependence while fostering endothelial healing. These innovations align with sustainability mandates and patient preference for reduced permanent implants. Manufacturers also explore hybrid constructs, pairing metallic frameworks with resorbable outer layers, to capture the best of both worlds. The biomaterial shift keeps the coronary stents market competitive for suppliers that can blend mechanical robustness with biological harmony.
Complete Report Scope:
- By Product Type
- Drug-Eluting Stent (DES)
- Bare-Metal Stent (BMS)
- Bioabsorbable Vascular Scaffold (BVS)
- Dual-Therapy Stent (DTS)
- By Biomaterial
- Metallic
- Polymeric
- Natural / Bio-derived
- By Mode of Delivery
- Balloon-Expandable Stent
- Self-Expanding Stent
- By End User
- Hospitals
- Cardiac Catheterization Labs
- Ambulatory Surgical Centers
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America retained 34.90% of global revenue in 2025, underpinned by early adoption of AI-guided imaging and favorable reimbursement for high-performance DES. Hospitals leverage comprehensive insurance coverage to select premium platforms, and regulatory pathways remain predictable. Supply-chain instability tied to cobalt-chromium is partly offset by domestic alloys and streamlined FDA emergency pathways that prioritize critical cardiovascular devices. Clinical trial density further entrenches regional leadership.
Asia-Pacific is the fastest riser with a 7.32% CAGR through 2031, fueled by public procurement that widens access while compressing prices. China's monopsony purchasing model, combined with industrial policy, accelerates domestic champion emergence. India mirrors this trajectory through price ceilings that catapult local firms past 60% share. Urbanization and rising incomes expand PCI eligibility, while public insurance schemes close affordability gaps. These factors create a volume-driven growth pattern distinct from the value-centric North American model.
Europe shows measured expansion as Medical Device Regulation harmonizes quality standards and environmental considerations shape tender scores. Brexit disruptions are settling as mutual recognition agreements stabilize cross-border supply. Sustainability criteria encourage polymers with lower life-cycle impact, nudging R&D toward degradable constructs. Meanwhile, shared-decision frameworks influenced by ISCHEMIA temper elective PCI volumes but elevate demand for best-in-class devices when intervention proceeds.
- Abbott Laboratories
- Boston Scientific
- Medtronic
- Terumo
- B. Braun
- Biosensors International
- SMT
- Lepu Medical Technology (Beijing) Co., Ltd
- Meril Life Science
- Cook Group
- Translumina
- MicroPort
- Cordis
- Alvimedica
- AMG International GmbH
- Balton Sp. z o.o.
- QualiMed Innovative Medizinprodukte GmbH
- Rontis AG
- Concept Medical Inc
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Prevalence CAD and Aging Population
- 4.2.2 Shift Toward Early PCI In Acute Coronary Syndrome Guidelines
- 4.2.3 Rapid Uptake Of Ultrathin-Strut & Biodegradable-Polymer DES
- 4.2.4 Integration Of AI-Guided Imaging & Sizing Tools
- 4.2.5 Hospital Preference For Day-Care Radial PCI Programs
- 4.2.6 Government Tenders Favoring Domestic DES and Innovation Incentives
- 4.3 Market Restraints
- 4.3.1 Price Caps & Centralized Procurement Squeezing ASPs
- 4.3.2 Safety Signals Around Late Scaffold Thrombosis In BVS
- 4.3.3 Supply-Chain Shortages Of High-Purity Co-Cr Alloy
- 4.3.4 Clinical Pushback On Routine Stenting Post-ISCHEMIA Trial
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technology Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size and Growth Forecasts (Value-USD)
- 5.1 By Product Type
- 5.1.1 Drug-Eluting Stent (DES)
- 5.1.2 Bare-Metal Stent (BMS)
- 5.1.3 Bioabsorbable Vascular Scaffold (BVS)
- 5.1.4 Dual-Therapy Stent (DTS)
- 5.2 By Biomaterial
- 5.2.1 Metallic
- 5.2.2 Polymeric
- 5.2.3 Natural / Bio-derived
- 5.3 By Mode of Delivery
- 5.3.1 Balloon-Expandable Stent
- 5.3.2 Self-Expanding Stent
- 5.4 By End User
- 5.4.1 Hospitals
- 5.4.2 Cardiac Catheterization Labs
- 5.4.3 Ambulatory Surgical Centers
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East and Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.3.1 Abbott Laboratories
- 6.3.2 Boston Scientific Corporation
- 6.3.3 Medtronic plc
- 6.3.4 Terumo Corporation
- 6.3.5 B. Braun SE
- 6.3.6 Biosensors International Group Ltd
- 6.3.7 SMT
- 6.3.8 Lepu Medical Technology (Beijing) Co., Ltd
- 6.3.9 Meril Life Sciences Pvt Ltd
- 6.3.10 Cook Medical Inc
- 6.3.11 Translumina GmbH
- 6.3.12 MicroPort Scientific Corporation
- 6.3.13 Cordis
- 6.3.14 Alvimedica
- 6.3.15 AMG International GmbH
- 6.3.16 Balton Sp. z o.o.
- 6.3.17 QualiMed Innovative Medizinprodukte GmbH
- 6.3.18 Rontis AG
- 6.3.19 Concept Medical Inc
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment

