PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2122916

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2122916
Transportation Management System - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the transportation management system market size is USD 9.71 billion in 2026 and is projected to reach USD 14.89 billion by 2031, advancing at an 8.93% CAGR.
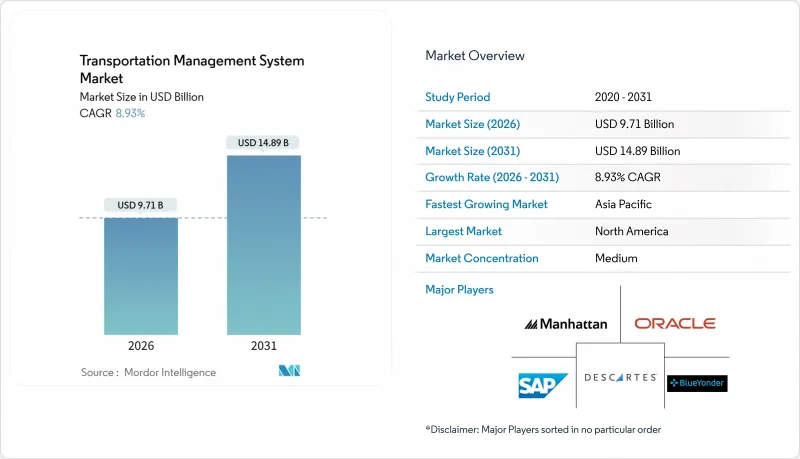
This report is Segmented by Mode of Transportation (Roadways, and More), Deployment (On-Premise, Cloud, Hybrid), Enterprise Size (Large Enterprises, Micro Enterprises, and More), End-User Industry (Manufacturing, Automotive, and More), Component (Software, and Services), Application (Order Management, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Transportation Management System Market Trends and Insights
Cloud-Based TMS Adoption Accelerates Cost-to-Serve Savings
Multi-tenant cloud platforms deliver 15-25% freight-cost reductions by pooling shipper demand, automating carrier selection through real-time rate shopping, and scaling compute elastically during peak seasons. The Transportation Management System market benefits from subscription pricing, which eliminates capital expenditure and aligns vendor incentives with on-time, cost-efficient execution. Oracle and SAP migrated their routing engines to in-memory architectures in 2024, cutting plan-to-execute latency from minutes to seconds, while Blue Yonder fused demand sensing with routing decisions to proactively shift inventory, reducing stockout risk. The ability to launch new features monthly rather than annually keeps functionality current as regulations evolve. Enterprises also avoid hardware refresh cycles, channeling savings toward data-science talent and continuous improvement programs.
E-Commerce and Omnichannel Retail Demand Real-Time, Last-Mile Optimisation
Same-day delivery promises shorten planning windows from days to hours, forcing retailers to embed advanced route-resequencing logic into their Transportation Management System workflows. Amazon's expansion of its Delivery Service Partner network to 4,500 contractors in 2024 heightened demand for light mobile interfaces that sync with consumer-facing tracking pages. Route-density algorithms trimmed per-package urban delivery cost by 30-40% for high-volume shippers, a saving impossible without cloud elasticity and granular telemetry. Crowdsourced delivery models require dynamic capacity matching and real-time bidding, capabilities that legacy on-premise platforms cannot meet. Micro-fulfillment centers, typically placed within 16 km of dense population clusters, amplify the need for systems that co-optimize inventory positioning and dispatch decisions every 15-30 minutes.
High Integration Cost with Legacy ERP/WMS Stacks
Enterprises running SAP ECC or Oracle E-Business Suite incur integration bills of USD 500,000 to USD 3 million when layering a cloud TMS, as legacy systems lack modern APIs. Each additional ERP instance increases complexity, as customer, product, and location master data must be bidirectionally mapped. Manhattan Associates reported an 18% year-over-year increase in professional services revenue from integration projects in 2024, underscoring this friction. Some manufacturers postpone adoption of the Transportation Management System market until broader digital transformations are complete, stretching deployment timelines by several years. The burden falls hardest on capital-intensive verticals, leaving digitally native retailers free to implement a cloud TMS in weeks.
Other drivers and restraints analyzed in the detailed report include:
- AI-Driven Predictive ETA Tools Cut Detention/SLA Penalties
- Regulatory Push for ELD and Greenhouse Gas Reporting Digitalises Freight
- Data-Security and Privacy Concerns for Cloud Deployments
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Road freight dominated in 2025, with a 56.91% share of the Transportation Management System market, underscoring the continued primacy of truckload and less-than-truckload services for domestic distribution. Air freight, however, is recording the fastest 9.83% CAGR because pharmaceutical manufacturers have pivoted high-value biologics onto flights that cut door-to-door transit to below 48 hours, thereby curbing temperature-excursion risk. The Transportation Management System market size for air-centric workflows is expanding further as the International Air Transport Association ONE Record standard enables airlines and forwarders to expose booking and status APIs in real time. Intermodal modules that synchronize container transfers between rail and truck help sustain rail competitiveness on 1,600 km lanes, yet growth lags air because schedule rigidity limits rapid response to demand spikes. Ocean freight users rely on specialized container-tracking extensions that map vessel schedules, port congestion, and drayage appointments within a single control tower.
Air-freight technology adoption accelerated when Amazon Air grew its fleet to 110 aircraft in 2025, prompting retailers to demand minute-level status feeds for cross-border e-commerce packages. Berlin-based marketplace Cargo.one integrated with 100 airlines to create a one-click booking portal linked directly to leading TMS vendors, collapsing the traditional three-day quote cycle to seconds. Regulatory pressure intensifies uptake: the International Civil Aviation Organization CORSIA framework obliges airlines to allocate carbon emissions to shipments, so TMS modules that present emissions data alongside costs now influence carrier selection. As small shippers access instant spot capacity, network density rises, improving load factors and further enhancing the Transportation Management System market value proposition.
Cloud solutions captured 61.23% revenue in 2025 and are outpacing alternatives at a 9.61% CAGR because pay-as-you-go billing scales with shipment counts, a decisive factor for seasonally volatile retailers. TMS customers also value monthly feature releases that deliver rapid regulatory updates and AI upgrades without downtime, a flexibility unavailable in legacy on-premise architectures. Hybrid models retain master data locally but process execution in the cloud, appealing to regulated industries that must prove data residency, yet overall growth remains slower. Vendors have begun sunsetting on-premise roadmaps; Oracle issued its final major on-premise feature pack in 2025, redirecting engineering capacity to its SaaS edition.
Blue Yonder rebuilt its Luminate suite on Microsoft Azure in 2024, stating that customers cut planning cycles by 40% and improved load consolidation by 12% within six months. Microenterprises are now viable buyers because freemium offerings from Kuebix and 3Gtms unlock entry-level functionality, with premium analytics sold a la carte. AI and machine-learning workloads leverage GPU-accelerated clusters in cloud data centers, enabling shipment-type-specific models that predict lead-time variability and carbon footprint. Security concerns continue to diminish as cloud providers pass stringent audits and as breach headlines increasingly implicate poorly patched on-premise servers. Consequently, the Transportation Management System market is tilting irreversibly toward SaaS.
Complete Report Scope:
- By Mode of Transportation
- Roadways
- Railways
- Airways
- Maritime
- By Deployment
- On-Premise
- Cloud
- Hybrid
- By Enterprise Size
- Large Enterprises
- Small and Medium Enterprises
- Micro Enterprises
- By End-User Industry
- Manufacturing
- Retail and E-Commerce
- Food and Beverage
- Healthcare and Pharmaceuticals
- Automotive
- 3PL and Logistics Service Providers
- By Component
- Software
- Services
- Consulting
- Integration and Implementation
- Support and Maintenance
- By Application
- Order Management
- Route Planning and Optimization
- Freight Audit and Payment
- Real-Time Visibility and Tracking
- Inventory and Warehouse Integration
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- Middle East
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America held the largest regional share in 2025 at 42.67% of the Transportation Management System market, thanks to mature e-commerce penetration, stringent enforcement of electronic logging devices, and a fragmented carrier base that intensifies orchestration complexity. Growth steadies as adoption reaches saturation, yet revenue expands from premium AI features, autonomous-vehicle integrations, and carbon-optimization modules. Asia-Pacific advances at a 9.91% CAGR through 2031, led by China's mandate to trim logistics costs by 10% and India's e-way bill system that compels digital freight paperwork. Provincial subsidies in China reimburse up to 30% of software costs for carriers adopting certified TMS, while India's fragmented fleet of 12 million small truckers finds value in marketplace integrations that lower empty-mile ratios from 40% to 25%.
Europe holds a substantial slice, with Germany, France, and the United Kingdom embracing TMS to address cross-border customs complexity and the Fit for 55 carbon-reporting mandates. Vendors with native multilingual interfaces and VAT-compliant invoicing gain an edge. The Middle East and Africa region, particularly the United Arab Emirates and Saudi Arabia, invests in customs-clearance automation to diversify economies; DP World's 2024 rollout of Oracle Transportation Management across global terminals cut container dwell times by 18%. South America confronts integration cost headwinds and currency volatility, yet Brazilian and Argentine carriers adopt lightweight route-optimization apps to offset diesel inflation. Japan's aging driver workforce is pushing fleets toward AI-assisted dispatching to reduce overtime, reinforcing local demand.
Venture capital inflows add fuel: Asia-Pacific logistics-tech startups raised USD 4.2 billion in 2024, ensuring a pipeline of localized innovations. Government blueprints, such as Malaysia's National Logistics Plan and Australia's Freight and Supply Chain Strategy, layer grants and tax deductions on top of venture backing, accelerating small-enterprise adoption.
- SAP SE
- Oracle Corporation
- Blue Yonder Group, Inc.
- Descartes Systems Group
- Manhattan Associates
- MercuryGate International
- Trimble Transportation
- E2open LLC
- Project44, Inc.
- Transplace, LLC
- Infor Nexus
- Kinaxis Inc.
- C.H. Robinson
- BluJay Solutions
- CargoSmart Ltd.
- 3Gtms Inc.
- Alpega Group
- KUEBIX LLC
- WiseTech Global Limited
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Cloud-Based TMS Adoption Accelerates Cost-to-Serve Savings
- 4.2.2 E-Commerce and Omnichannel Retail Demand Real-Time, Last-Mile Optimisation
- 4.2.3 Regulatory Push for ELD and Greenhouse Gas Reporting Digitalises Freight
- 4.2.4 Freight-Marketplace Convergence Enables Dynamic Capacity Procurement
- 4.2.5 AI-Driven Predictive ETA Tools Cut Detention/SLA Penalties
- 4.2.6 Open-Source Telemetry APIs and Micro-Services Unlock Modular TMS for SMEs
- 4.3 Market Restraints
- 4.3.1 High Integration Cost with Legacy ERP/WMS Stacks
- 4.3.2 Data-Security and Privacy Concerns for Cloud Deployments
- 4.3.3 Shortage of In-House Data-Science Talent to Exploit Analytics Modules
- 4.3.4 Fragmented Carrier-Telematics Standards Hinder Multimodal Visibility
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Impact of Macroeconomic Factors on the Market
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Bargaining Power of Suppliers
- 4.8.4 Threat of Substitutes
- 4.8.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Mode of Transportation
- 5.1.1 Roadways
- 5.1.2 Railways
- 5.1.3 Airways
- 5.1.4 Maritime
- 5.2 By Deployment
- 5.2.1 On-Premise
- 5.2.2 Cloud
- 5.2.3 Hybrid
- 5.3 By Enterprise Size
- 5.3.1 Large Enterprises
- 5.3.2 Small and Medium Enterprises
- 5.3.3 Micro Enterprises
- 5.4 By End-User Industry
- 5.4.1 Manufacturing
- 5.4.2 Retail and E-Commerce
- 5.4.3 Food and Beverage
- 5.4.4 Healthcare and Pharmaceuticals
- 5.4.5 Automotive
- 5.4.6 3PL and Logistics Service Providers
- 5.5 By Component
- 5.5.1 Software
- 5.5.2 Services
- 5.5.2.1 Consulting
- 5.5.2.2 Integration and Implementation
- 5.5.2.3 Support and Maintenance
- 5.6 By Application
- 5.6.1 Order Management
- 5.6.2 Route Planning and Optimization
- 5.6.3 Freight Audit and Payment
- 5.6.4 Real-Time Visibility and Tracking
- 5.6.5 Inventory and Warehouse Integration
- 5.7 By Geography
- 5.7.1 North America
- 5.7.1.1 United States
- 5.7.1.2 Canada
- 5.7.1.3 Mexico
- 5.7.2 Europe
- 5.7.2.1 Germany
- 5.7.2.2 United Kingdom
- 5.7.2.3 France
- 5.7.2.4 Russia
- 5.7.2.5 Rest of Europe
- 5.7.3 Asia-Pacific
- 5.7.3.1 China
- 5.7.3.2 Japan
- 5.7.3.3 India
- 5.7.3.4 South Korea
- 5.7.3.5 Australia
- 5.7.3.6 Rest of Asia-Pacific
- 5.7.4 Middle East and Africa
- 5.7.4.1 Middle East
- 5.7.4.1.1 Saudi Arabia
- 5.7.4.1.2 United Arab Emirates
- 5.7.4.1.3 Rest of Middle East
- 5.7.4.2 Africa
- 5.7.4.2.1 South Africa
- 5.7.4.2.2 Egypt
- 5.7.4.2.3 Rest of Africa
- 5.7.4.1 Middle East
- 5.7.5 South America
- 5.7.5.1 Brazil
- 5.7.5.2 Argentina
- 5.7.5.3 Rest of South America
- 5.7.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)}
- 6.4.1 SAP SE
- 6.4.2 Oracle Corporation
- 6.4.3 Blue Yonder Group, Inc.
- 6.4.4 Descartes Systems Group
- 6.4.5 Manhattan Associates
- 6.4.6 MercuryGate International
- 6.4.7 Trimble Transportation
- 6.4.8 E2open LLC
- 6.4.9 Project44, Inc.
- 6.4.10 Transplace, LLC
- 6.4.11 Infor Nexus
- 6.4.12 Kinaxis Inc.
- 6.4.13 C.H. Robinson
- 6.4.14 BluJay Solutions
- 6.4.15 CargoSmart Ltd.
- 6.4.16 3Gtms Inc.
- 6.4.17 Alpega Group
- 6.4.18 KUEBIX LLC
- 6.4.19 WiseTech Global Limited
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

