PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2123133

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2123133
Smart City Platform - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the smart city platform market size reached USD 30.20 billion in 2026 and is projected to climb to USD 54.05 billion by 2031, delivering a compelling 12.34% CAGR across the forecast horizon.
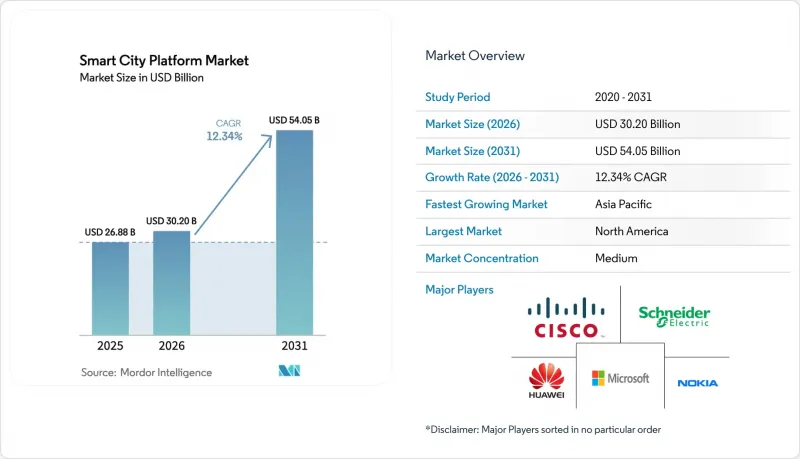
This report is Segmented by Platform Type (Connectivity Management, Integration, and More), Application (Smart Mobility/Transportation, Smart Security and Public Safety, and More), Deployment Model (On-Premise, Cloud, and More), End-User (Government and Municipalities, Utilities and Energy Providers, Healthcare Providers, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Smart City Platform Market Trends and Insights
IoT-Device Proliferation Across Urban Infrastructure
Global municipal IoT endpoints reached 1.2 billion in 2025, a 41% increase from 2024, as utilities, environmental agencies, and public works departments scaled up connected devices. Density remains uneven, with tier-one cities averaging 18 devices per capita, while tier-two municipalities average six, obliging platform vendors to support both high-volume, low-latency workloads and battery-constrained networks. Edge inference is now a design prerequisite, for instance, Intel's OpenVINO toolkit trimmed video-analytics latency by 62% in 47 deployments, freeing bandwidth budgets for additional sensors. This distributed pattern reduces backhaul costs, which still exceed USD 0.08 per gigabyte in fiber-poor markets. Vendor strategies, therefore, emphasize auto-scaling data pipelines and plug-and-play device onboarding to address the bifurcated demand profile.
Expanding Government Smart-City Funding Programs
Public investment increased 29% year-over-year to USD 38.4 billion in 2025, creating a vital flywheel for the smart city platform market. The Infrastructure Investment and Jobs Act allocated USD 1.2 billion for U.S. digital infrastructure, while the European Union's Digital Europe Programme committed EUR 1.8 billion (USD 2.0 billion) through 2027. China, India, and South Korea are channeling funds toward tier-two cities to bridge urban-rural gaps, often stipulating NGSI-LD compliance that benefits vendors with open APIs. Grants speed adoption but simultaneously heighten scrutiny of cybersecurity posture and data governance, prompting cities to incorporate interoperability and zero-trust provisions into RFPs from the outset.
Data-Privacy and Cyber-Security Concerns
Municipal ransomware incidents rose 34% in 2025, pushing average remediation costs to USD 4.2 million. Europe's Network and Information Security Directive 2 now requires 24-hour breach disclosure and penalties of up to 2% of annual revenue for non-compliance. Stricter rules strain vendor economics by increasing compliance overhead by 18% and compel cities to anonymize data, a step that can erode AI accuracy by as much as 19%, according to IEEE researchers. Zero-trust architectures mitigate exposure but necessitate network segmentation and continuous authentication, often delaying deployments by nine months. The policy headwind is particularly acute in privacy-sensitive applications such as healthcare and public-safety video, where citizen opposition can stall project approvals.
Other drivers and restraints analyzed in the detailed report include:
- AI and Cloud-Enabled Real-Time Analytics Adoption
- Rapid Roll-Out of 5G and LPWAN Connectivity
- High Up-Front Capital Expenditure
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Security management platforms are on track for a 13.02% CAGR from 2026 to 2031, reflecting municipal urgency to contain escalating cyber incidents. The segment's surge contrasts with connectivity management's 28.73% market-leading share in 2025, where revenue growth is moderating under pricing pressure. Integration platforms, which hold a 22% share in 2025, benefit from cities migrating to microservices that enable them to integrate legacy SCADA systems with contemporary analytics. Device-management products, at roughly 18% share, ride the wave of edge-AI node growth that requires continuous firmware updates. Data-management layers round out the landscape by leveraging NGSI-LD context models to ensure semantic portability across city silos, cementing their role in the smart city platform market.
Competition is intensifying. Cisco's USD 28 billion acquisition of Splunk illustrated how network observability is converging with security analytics in an integrated stack. NGSI-LD-driven procurement favors open-source solutions with a pedigree, such as FIWARE, which is now active in 89 European municipalities. Vendors embed zero-trust modules, including Palo Alto Networks' Prisma SASE features, in 23 city deployments to limit IoT attack surfaces. RFP language mirrors the shift as 68% of 2025 tenders mandate built-in threat response integration. As cities ask suppliers to assume cyber-risk, recurring service revenue from managed detection and response is emerging as a future profit pool within the smart city platform industry.
Smart healthcare is projected to register a 13.55% CAGR to 2031, outpacing every other use case as telemedicine, ambulance routing, and air-quality-linked care become staples of post-pandemic municipal health strategies. Smart infrastructure retained 31.84% of the smart city platform market share in 2025, reflecting the legacy outcome of early LED retrofits that have now been retrofitted with occupancy and daylight sensors. Mobility and transportation applications held roughly 24% share, aided by connected-vehicle pilots, while public-safety analytics contributed about 19%. Utilities and energy management captured 16%, mainly from advanced metering, and citizen-service portals comprise the remainder, with multilingual chatbots gaining traction.
Healthcare synergies illustrate cross-domain value, such as Seoul's U-Healthcare initiative, which combines wearable and air-quality datasets to alert asthma patients in real-time. Singapore's IoT fitness stations raised park usage 22% in 2025. Lighting vendors, such as Signify, embed acoustic sensors in luminaires for anomaly detection, resulting in an 18% reduction in police response times in pilot studies. Cybersecurity controls added to IEC 62386 lighting interfaces increase fixture costs by USD 8-12 per unit, but de-risk citywide rollouts, further proving that resilience premiums are now accepted as an overhead in the smart city platform market.
Complete Report Scope:
- By Platform Type
- Connectivity Management Platform
- Integration Platform
- Device Management Platform
- Data Management Platform
- Security Management Platform
- By Application
- Smart Mobility / Transportation
- Smart Security and Public Safety
- Smart Utilities (Energy / Water)
- Smart Governance and Citizen Services
- Smart Infrastructure (Buildings / Street Lighting)
- Smart Healthcare
- By Deployment Model
- On-Premise
- Cloud
- Hybrid
- By End-User
- Government and Municipalities
- Utilities and Energy Providers
- Transportation and Logistics Operators
- Healthcare Providers
- Other Commercial Enterprises
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia and New Zealand
- Rest of Asia Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- Middle East
- North America
Geography Analysis
North America accounted for 38.74% of the revenue in 2025, driven by federal and provincial grant programs and a growing utility modernization market. Chicago's Azure Digital Twins rollout across 2,400 buildings exemplifies the region's tilt toward energy-efficiency use cases, with projected annual savings of USD 14 million. Yet procurement fragmentation persists because the United States lacks a national smart-city mandate, forcing vendors to navigate disparate state rules. Canada's CAD 75 million (USD 55 million) Smart Cities Challenge funds illustrate how smaller economies catalyze projects through competitive grants. Mexico's MXN 8.5 billion (USD 500 million) mobility effort demonstrates rising Latin American interest, although budget reallocations after a 2025 cyber breach slowed implementation.
Asia-Pacific is the fastest-growing region, forecast at a 13.78% CAGR as China's CNY 120 billion (USD 16.8 billion) New Infrastructure Initiative and India's INR 48,000 crore (USD 5.8 billion) Smart Cities Mission phase two pull tier-two cities into the digital fold. Domestic champions such as Huawei and Alibaba Cloud leverage data-localization policies to capture share, while Japan's JPY 120 billion (USD 820 million) digital-twin program signals renewed momentum in mature economies. South Korea's KRW 2.1 trillion (USD 1.6 billion) fund positions the nation as a testing ground for autonomous mobility platforms. Australia's open-data exchanges appear small in budget terms but generate outsized developer engagement that broadens ecosystem depth.
Europe's trajectory pivots on interoperability mandates. The EU directive to adopt NGSI-LD by 2026 forces vendors to open proprietary schemas or forfeit access to one of the world's largest smart city platform markets. National programs in the United Kingdom, Germany, France, Italy, and Spain collectively exceed USD 1.9 billion for 2025 alone. Germany's EUR 500 million (USD 565 million) connected-vehicle retrofit illustrates how transport applications integrate with broader city platforms. Southern Europe receives targeted allocations to narrow digital divides, evidenced by Italy's EUR 410 million (USD 464 million) resiliency budget. Spain's Red.es backs municipal IoT frameworks with EUR 290 million (USD 328 million), employing Barcelona's Sentilo architecture as a blueprint.
South America, the Middle East, and Africa remain in early adoption mode yet supply landmark projects. Brazil earmarked BRL 1.8 billion (USD 360 million) for mobility upgrades in major cities, although federal negotiations have delayed disbursement. Saudi Arabia's USD 500 billion NEOM integrates Siemens MindSphere for greenfield infrastructure. South Africa secured African Development Bank financing for a ZAR 480 million (USD 26 million) smart-water platform that slashes non-revenue water by 18%. Nigeria's NGN 15 billion (USD 10 million) pilot in Lagos and Abuja test-beds traffic management and waste-collection platforms. Limited fiber backbones and power instability still curtail rapid expansion, yet blended finance and modular deployments create footholds for future scaling of the smart city platform market.
- Siemens Aktiengesellschaft
- Schneider Electric SE
- Microsoft Corporation
- Hitachi, Ltd.
- Huawei Technologies Co., Ltd.
- Cisco Systems, Inc.
- General Electric Company
- International Business Machines Corporation
- Alibaba Group Holding Limited
- Amazon Web Services, Inc.
- Oracle Corporation
- SAP SE
- Telefonaktiebolaget LM Ericsson
- Fujitsu Limited
- NEC Corporation
- Itron, Inc.
- Atos SE
- Nokia Corporation
- Quantela, Inc.
- Intel Corporation
- PTC Inc.
- Bosch.IO GmbH
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 IoT-Device Proliferation Across Urban Infrastructure
- 4.2.2 Expanding Government Smart-City Funding Programs
- 4.2.3 AI- and Cloud-Enabled Real-Time Analytics Adoption
- 4.2.4 Rapid Roll-Out of 5G and LPWAN Connectivity
- 4.2.5 Interoperability Mandates (NGSI-LD, OASC MIMs)
- 4.2.6 Monetisation of Municipal Data Marketplaces
- 4.3 Market Restraints
- 4.3.1 Data-Privacy and Cyber-security Concerns
- 4.3.2 High Up-Front Capital Expenditure
- 4.3.3 Legacy-System Vendor Lock-In
- 4.3.4 Shortage of City-Level Data-Governance Talent
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Consumers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Assessment of Impact of Macroeconomic Factors
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Platform Type
- 5.1.1 Connectivity Management Platform
- 5.1.2 Integration Platform
- 5.1.3 Device Management Platform
- 5.1.4 Data Management Platform
- 5.1.5 Security Management Platform
- 5.2 By Application
- 5.2.1 Smart Mobility / Transportation
- 5.2.2 Smart Security and Public Safety
- 5.2.3 Smart Utilities (Energy / Water)
- 5.2.4 Smart Governance and Citizen Services
- 5.2.5 Smart Infrastructure (Buildings / Street Lighting)
- 5.2.6 Smart Healthcare
- 5.3 By Deployment Model
- 5.3.1 On-Premise
- 5.3.2 Cloud
- 5.3.3 Hybrid
- 5.4 By End-User
- 5.4.1 Government and Municipalities
- 5.4.2 Utilities and Energy Providers
- 5.4.3 Transportation and Logistics Operators
- 5.4.4 Healthcare Providers
- 5.4.5 Other Commercial Enterprises
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 United Kingdom
- 5.5.3.2 Germany
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Australia and New Zealand
- 5.5.4.6 Rest of Asia Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Nigeria
- 5.5.5.2.3 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Siemens Aktiengesellschaft
- 6.4.2 Schneider Electric SE
- 6.4.3 Microsoft Corporation
- 6.4.4 Hitachi, Ltd.
- 6.4.5 Huawei Technologies Co., Ltd.
- 6.4.6 Cisco Systems, Inc.
- 6.4.7 General Electric Company
- 6.4.8 International Business Machines Corporation
- 6.4.9 Alibaba Group Holding Limited
- 6.4.10 Amazon Web Services, Inc.
- 6.4.11 Oracle Corporation
- 6.4.12 SAP SE
- 6.4.13 Telefonaktiebolaget LM Ericsson
- 6.4.14 Fujitsu Limited
- 6.4.15 NEC Corporation
- 6.4.16 Itron, Inc.
- 6.4.17 Atos SE
- 6.4.18 Nokia Corporation
- 6.4.19 Quantela, Inc.
- 6.4.20 Intel Corporation
- 6.4.21 PTC Inc.
- 6.4.22 Bosch.IO GmbH
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

