PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2123152

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2123152
Managed File Transfer - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the managed file transfer market size is expected to grow from USD 2.19 billion in 2025 to USD 2.46 billion in 2026 and is forecast to reach USD 4.02 billion by 2031 at 10.32% CAGR over 2026-2031.
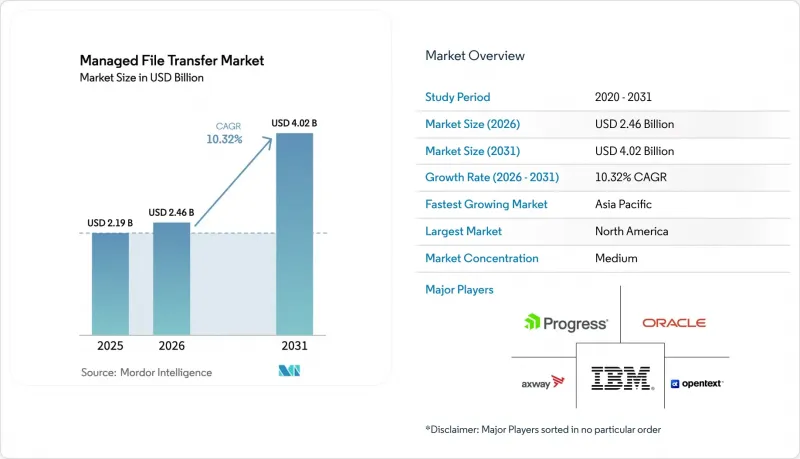
This report is Segmented by Organization Size (Large Enterprises, and Small and Medium Enterprises), Deployment Mode (Cloud-Based, and On-Premise), Transfer Type (System-Centric File Transfer, and More), Solution (Real-Time Monitoring and Control, Automate Application Transfers, and More), End-User Industry (Healthcare, Retail, and More), and Geography. Market Forecasts are Provided in Value (USD).
Global Managed File Transfer Market Trends and Insights
Accelerated Shift to Zero-Trust Architectures
CISA's 2024 advisory on living-off-the-land techniques highlighted how attackers exploit trusted file-transfer utilities to circumvent perimeter defenses. As a result, organizations are dismantling implicit-trust zones and demanding platforms that enforce continuous identity validation, device-posture checks, and content inspection for every file. Managed file transfer market vendors embed policy engines tied to identity providers and DLP tools, delivering adaptive access controls without the latency of middleware. Cyber-insurance carriers now require zero-trust attestations, further accelerating platform refresh cycles. Enterprises that adopted zero-trust MFT reduced mean-time-to-detect from days to minutes, limiting breach impact and lowering premiums.
Escalating Financial Penalties for Non-Compliance
The record GDPR fines imposed on Uber and TikTok demonstrate that weak governance around cross-border transfers can trigger top-tier penalties. The FTC's updated Health Breach Notification Rule extended disclosure mandates to non-HIPAA entities, making audit trails and encryption-at-rest mandatory for health apps. Enterprises respond by adopting platforms pre-loaded with GDPR, HIPAA, SOC 2, and ISO 27001 templates, cutting certification timelines. Real-time logs and automated incident response reduce breach-notification costs and protect brand equity, which lifts demand across regulated industries and bolsters the managed file transfer market.
Skills Gap in Secure Automation Workflows
The 2024 ISC2 study highlighted a 4.8 million-person cybersecurity shortfall, with 92% of firms lacking automation skills. Complex scripting, API orchestration, and policy tuning slow MFT rollouts. SMEs often accept default settings, weakening controls, or pay for costly consultants that prolong payback periods. Vendors simplify interfaces and launch managed-services tiers, but recurring fees erode the cost benefits, tempering the near-term growth of the managed file transfer market.
Other drivers and restraints analyzed in the detailed report include:
- Multi-Cloud and Hybrid Integration Demand Surge
- AI-Powered Threat Detection in File Transfers
- Legacy System Lock-In and Integration Complexity
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Small and medium enterprises are forecast to grow at a 10.07% CAGR, outstripping the overall managed file transfer market. Deloitte found 68% of SMEs face budget pressure, yet cybersecurity spend climbed 15% in 2025. Subscription MFTPaaS eliminates servers and six-figure licenses, letting lean IT teams deploy within days. The October 2025 launch of Automate MFT targets this cohort with a promised 50% TCO cut. Large enterprises retain a 70.24% share due to entrenched on-premises estates, but hybrid strategies signal a gradual pivot toward SaaS connectors. As mid-market adoption increases, the managed file transfer market expands into greenfield accounts that were previously priced out of enterprise-grade security.
Fortune 500 companies are harnessing MFTPaaS for seamless cloud-to-cloud transitions, all the while upholding on-premises gateways for their mainframe connections. This strategic combination ensures uniform policy application and a worldwide presence, all while adhering to data-residency regulations. This adaptability underscores the managed file transfer market's robustness, even amidst economic fluctuations.
On-premises installations accounted for 64.69% of 2025 revenue, while cloud deployments are expected to register a 10.13% CAGR through 2031. Elastic scaling addresses holiday retail surges and healthcare open enrollment peaks, trimming 30-40% of capacity overhead. OMB Memorandum M-24-15 now mandates FedRAMP authorization, signaling institutional acceptance of secure cloud services.
Kiteworks' FedRAMP High certification in 2024 proved that MFTPaaS can satisfy stringent controls. Regions with strict localization laws, notably China and Russia, still favor on-premises hubs; yet, hybrid architectures with regional gateways and cloud orchestration mitigate compliance friction. This transition ecosystem widens the managed file transfer market size while rebalancing revenue streams toward recurring subscriptions.
Complete Report Scope:
- By Organization Size
- Large Enterprises
- Small and Medium Enterprises
- By Deployment Mode
- Cloud-Based
- On-Premise
- By Transfer Type
- System-Centric File Transfer
- People-Centric File Transfer
- Extreme File Transfer
- By Solution
- Real-Time Monitoring and Control
- Fast Partner Onboarding and Collaboration
- Automate Application Transfers
- Other Solutions
- By End-User Industry
- BFSI
- IT and Telecommunications
- Healthcare
- Retail
- Media and Entertainment
- Government and Public Sector
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- Middle East
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
In 2025, North America captured 37.82% of the revenue, driven by strict regulatory measures, increasing adoption of cyber-insurance, and heightened awareness of cybersecurity threats. Responding to CISA's emphasis on "living-off-the-land" attacks, federal agencies took significant steps to modernize their FTP estates, ensuring enhanced security and compliance. This trend is mirrored by Canada's banking regulator, which has implemented robust cybersecurity frameworks, and manufacturers in Mexico's nearshoring sector, who are adopting advanced measures to safeguard their operations. These developments collectively reinforce the region's momentum in addressing cybersecurity challenges.
Asia-Pacific is forecast to post the fastest 11.46% CAGR. Cloud investments driven by Digital India and Japan's reform agenda demand secure hybrid transfers. However, China's PIPL and Russia's localization laws enforce domestic storage, nudging vendors toward in-country data centers. Europe balances expansion with high compliance pressure. Uber and TikTok fines illustrate uncompromising enforcement that fuels demand for audit-ready platforms. The EU-U.S. Data Privacy Framework offers partial relief yet faces legal scrutiny.
Saudi Arabia's 2024 Personal Data Protection Law aligns closely with the GDPR, and Brazil intensifies its LGPD enforcement with heightened fines. As the Middle East, Africa, and South America emerge as new frontiers, infrastructure gaps in these regions are increasingly leaning towards cloud solutions. This trend is paving the way for vendors with regional Points of Presence (PoPs) to tap into the previously uncharted segments of the managed file transfer market.
- IBM Corporation
- Axway Software SA
- OpenText Corporation
- Progress Software Corporation
- Fortra, LLC
- Oracle Corporation
- TIBCO Software Inc.
- Cleo Communications Inc.
- QlikTech (Attunity)
- Coviant Software
- Seeburger AG
- Signiant Inc.
- JSCAPE LLC
- Primeur Group
- Software AG
- Micro Focus International plc
- Broadcom Inc. (CA XCOM)
- Kiteworks (Accellion)
- South River Technologies
- Safe-T Group
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Accelerated Shift to Zero-Trust Architectures
- 4.2.2 Escalating Financial Penalties for Non-Compliance
- 4.2.3 Multi-Cloud and Hybrid Integration Demand Surge
- 4.2.4 AI-Powered Threat Detection in File Transfers
- 4.2.5 Real-Time Supply-Chain Data Synchronization Needs
- 4.2.6 Growing Adoption of MFTPaaS by Mid-Market Firms
- 4.3 Market Restraints
- 4.3.1 Skills Gap in Secure Automation Workflows
- 4.3.2 Legacy System Lock-In and Integration Complexity
- 4.3.3 Rising Cross-Border Data-Localization Barriers
- 4.3.4 Budget Constraints for SMEs Amid Macroeconomic Volatility
- 4.4 Impact of Macroeconomic Factors on the Market
- 4.5 Industry Value Chain Analysis
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Investment Analysis
- 4.9 Porter's Five Forces Analysis
- 4.9.1 Threat of New Entrants
- 4.9.2 Bargaining Power of Buyers
- 4.9.3 Bargaining Power of Suppliers
- 4.9.4 Threat of Substitutes
- 4.9.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Organization Size
- 5.1.1 Large Enterprises
- 5.1.2 Small and Medium Enterprises
- 5.2 By Deployment Mode
- 5.2.1 Cloud-Based
- 5.2.2 On-Premise
- 5.3 By Transfer Type
- 5.3.1 System-Centric File Transfer
- 5.3.2 People-Centric File Transfer
- 5.3.3 Extreme File Transfer
- 5.4 By Solution
- 5.4.1 Real-Time Monitoring and Control
- 5.4.2 Fast Partner Onboarding and Collaboration
- 5.4.3 Automate Application Transfers
- 5.4.4 Other Solutions
- 5.5 By End-User Industry
- 5.5.1 BFSI
- 5.5.2 IT and Telecommunications
- 5.5.3 Healthcare
- 5.5.4 Retail
- 5.5.5 Media and Entertainment
- 5.5.6 Government and Public Sector
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Russia
- 5.6.2.5 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 India
- 5.6.3.4 South Korea
- 5.6.3.5 Australia
- 5.6.3.6 Rest of Asia-Pacific
- 5.6.4 Middle East and Africa
- 5.6.4.1 Middle East
- 5.6.4.1.1 Saudi Arabia
- 5.6.4.1.2 United Arab Emirates
- 5.6.4.1.3 Rest of Middle East
- 5.6.4.2 Africa
- 5.6.4.2.1 South Africa
- 5.6.4.2.2 Egypt
- 5.6.4.2.3 Rest of Africa
- 5.6.4.1 Middle East
- 5.6.5 South America
- 5.6.5.1 Brazil
- 5.6.5.2 Argentina
- 5.6.5.3 Rest of South America
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 IBM Corporation
- 6.4.2 Axway Software SA
- 6.4.3 OpenText Corporation
- 6.4.4 Progress Software Corporation
- 6.4.5 Fortra, LLC
- 6.4.6 Oracle Corporation
- 6.4.7 TIBCO Software Inc.
- 6.4.8 Cleo Communications Inc.
- 6.4.9 QlikTech (Attunity)
- 6.4.10 Coviant Software
- 6.4.11 Seeburger AG
- 6.4.12 Signiant Inc.
- 6.4.13 JSCAPE LLC
- 6.4.14 Primeur Group
- 6.4.15 Software AG
- 6.4.16 Micro Focus International plc
- 6.4.17 Broadcom Inc. (CA XCOM)
- 6.4.18 Kiteworks (Accellion)
- 6.4.19 South River Technologies
- 6.4.20 Safe-T Group
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

