PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2123254

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2123254
Automotive Aluminium Extrusion - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the automotive aluminum extrusion market size is expected to grow from USD 58.97 billion in 2025 to USD 63.88 billion in 2026 and is forecast to reach USD 95.31 billion by 2031 at an 8.33% CAGR over 2026-2031.
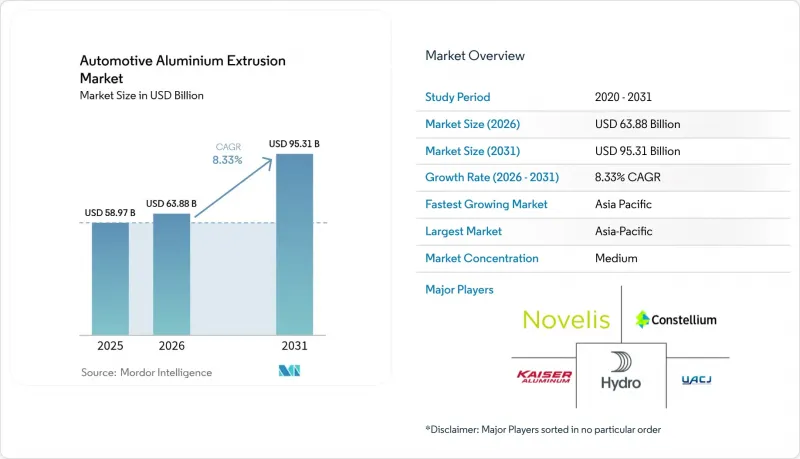
This report is Segmented by Component Type (Body Structure, Crash-Management Systems, and More), Vehicle Type (Passenger Cars, Light Commercial Vehicles, and More), Alloy Series (6xxx Heat-Treatable and More), Press Capacity (Less Than or Equal To15 MN, 16 To 25 MN, 26 To 35 MN, and More Than 35 MN), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Automotive Aluminium Extrusion Market Trends and Insights
Rising EV Penetration Accelerates Lightweight Body-In-White Adoption
Electric-vehicle drivetrains add hundreds of kilograms in battery mass, so automakers redesign structures with hollow aluminum extrusions that merge crash rails and mounting bosses. Demonstrations from leading Asian-Pacific brands show 20-plus percent weight cuts at constant safety ratings. The Aluminum Association projects per-vehicle aluminum content reaching up to 550 PPV by 2030, with extrusions accounting for most of that growth. Mainstream hatchbacks now mirror premium SUVs in specifying extruded rocker and roof rails, spreading tooling amortization across millions of units. Range anxiety, raw-material costs, and warranty exposure jointly motivate this high-volume shift.
Fleet CO2 and Fuel-Economy Mandates in the United States, European Union, and China
The European Union lowered its passenger-car fleet cap to 93.6 g/km in 2025 and will almost halve it by 2030; each excess gram triggers a hefty per-vehicle fine. Similar step-downs appear in United States CAFE updates that require 40.4 mpg United States fleet averages by 2026. China's dual-credit program mirrors these goals by rewarding lightweight materials and levying penalties for non-compliance. Extruded aluminum lets manufacturers trim vehicle mass, offset battery weight, and avoid fines that can reach several thousand USD per car. Clear regulatory roadmaps also give suppliers the confidence to invest in new tooling and capacity. Mature crash data, proven recyclability, and scalable production further tilt the balance toward aluminum extrusions over magnesium or carbon fiber.
LME Aluminum Price Volatility & Supply-Chain Speculation
Aluminum base case price on the London Metal Exchange climbed close to USD 2,500 per ton in Q4-2024, the loftiest level since 2021, after Chinese smelters curtailed output and energy costs surged. Automakers locked into annual or longer vehicle-pricing cycles could not pass through those jumps quickly enough, eroding gross margins on battery-electric models that already carry higher bill-of-materials costs. Warehouse stocks are now dominated by Russian metal, so any sudden sanctions or export quotas could strip several million tonnes from accessible supply and trigger another spike. Hedging offers partial relief, yet the basis risk between cash metal and value-added billet still leaves extruders exposed when premiums widen. Smaller original-equipment manufacturers that rely on spot contracts remain the most vulnerable because they lack the scale to negotiate fixed-price offtake agreements with vertically integrated billet producers.
Other drivers and restraints analyzed in the detailed report include:
- Battery Thermal-Management Enclosures Require Complex Hollow Extrusions
- Near-Shoring of Tier-1 Extrusion Capacity (USMCA, EU-CBAM)
- Scarcity of More than 35 MN Press Lines for Large EV Profiles
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Body structures accounted for 37.83% of the 2025 automotive aluminum extrusion market, underscoring the sector's rapid shift toward lightweight vehicle designs. Carmakers replace conventional steel members with extruded aluminum to boost rigidity while reducing weight, improving fuel economy, and meeting tighter emissions regulations. These components also absorb crash energy effectively, enhancing passenger safety. The rise of multi-material body-in-white designs cements aluminum's role as the preferred structural material. Consequently, body structures remain the cornerstone of extrusion demand in modern vehicles.
Battery enclosures and thermal modules form the fastest-growing component class, expanding at a 9.87% CAGR through 2031 as electric-vehicle adoption accelerates. The corrosion resistance and dimensional precision of aluminum extrusions make them ideal for safeguarding sensitive battery packs. As automakers shift to higher-density batteries and modular EV platforms, the need for advanced thermal-management housings continues to rise. Lightweight enclosures also extend driving range, a key performance metric for buyers-this growth trajectory positions battery systems at the center of future aluminum extrusion demand.
Passenger Cars commanded 52.38% of the Automotive Aluminum Extrusion market in 2025 and mirror the overall market's 9.88% CAGR as BEV penetration climbs. Light commercial vehicles follow as parcel fleets electrify for last-mile delivery, prioritizing range and payload. Medium & heavy-duty trucks adopt extruded cab frames more cautiously, constrained by up-front costs. Buses and coaches present a steady replacement market, with fleet operators weighing long life cycles against lightweight benefits.
The automotive aluminum extrusion market for passenger cars is growing because platform economies of scale spread tooling costs across high unit volumes. Delivery vans, though cost-sensitive, increasingly favor extruded roof bows to offset the weight of battery packs under the floor. Drayage tractors and regional haul trucks investigate aluminum day-cab structures to recoup lost payload, yet frame rails often stay steel for torsional reasons. Transit buses are already alloy-intensive, so incremental adoption centers on next-generation alloys with higher recycled content.
Complete Report Scope:
- By Component Type
- Body Structure
- Crash-Management Systems
- Battery Enclosures and Thermal Modules
- Exterior Trim and Roof Rails
- Interior Modules
- Other Components
- By Vehicle Type
- Passenger Cars
- Light Commercial Vehicles
- Medium and Heavy-Duty Trucks
- Buses and Coaches
- By Alloy Series
- 6xxx Heat-Treatable
- 7xxx High-Strength
- 5xxx Non-Heat-Treatable
- Scandium & Novel Alloys
- By Press Capacity
- Less than or equal to 15 MN
- 16 to 25 MN
- 26 to 35 MN
- More than 35 MN
- By Geography
- North America
- United States
- Canada
- Rest of North America
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Spain
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia-Pacific
- Middle-East and Africa
- United Arab Emirates
- Saudi Arabia
- Turkey
- Egypt
- South Africa
- Rest of Middle-East and Africa
- North America
Geography Analysis
Asia-Pacific held 39.92% of the Automotive Aluminum Extrusion market share in 2025 and is set to grow at a 9.91% CAGR to 2031. China's dual-credit regime rewards high new-energy-vehicle output, while India's extrusion utilization hovers near 40%, leaving headroom for local suppliers as domestic EV production climbs PIB.GOV.IN. Japanese and South Korean value chains stretch into ASEAN, adding press lines in Thailand to serve regional assembly hubs. Tight primary-metal caps in China are pivoting the nation from a net exporter to balanced trade, influencing billet availability across the bloc.
North America benefits from USMCA regional-value rules that favor aluminum sourced and fabricated within the tri-nation zone. Recent capacity additions in the United States, Southeast, and northern Mexico shorten supply lanes to Detroit and Ontario plants. Canada supplies low-carbon primary aluminum via hydropower smelters, aligning with European decarbonization benchmarks and drawing interest from extruders seeking green-metal credentials.
Europe operates under the strictest fleet CO2 ceilings and will implement the Carbon Border Adjustment Mechanism tariff in 2026. Local billet stemming from hydropower smelters in Norway and Iceland helps automakers sidestep these charges. Germany, France, and Spain anchor demand, yet subsidy reductions in late 2025 slowed BEV uptake, challenging extruders to balance capacity. Neighboring Turkey positions itself as a near-shore alternative but must invest in low-carbon smelting or face the same CBAM levy.
- Constellium SE
- Novelis Inc.
- Norsk Hydro ASA
- Kaiser Aluminum Corp.
- UACJ Corp.
- Arconic Corp.
- Kobe Steel Ltd.
- Benteler International
- Bonnell Aluminum
- Hindalco Industries Ltd.
- Guangdong Hongtu
- ETEM Automotive
- Talco Aluminium Company
- Granges AB
- Press-Metal Aluminium
- Sapa Extrusions
- Exlabesa
- Walter Klein GmbH
- Omnimax International
- Innoval Technology
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising EV Penetration Accelerates Lightweight Body-In-White Adoption
- 4.2.2 Fleet CO2 and Fuel-Economy Mandates in the United States, European Union, and China
- 4.2.3 Battery Thermal-Management Enclosures Require Complex Hollow Extrusions
- 4.2.4 Near-Shoring of Tier-1 Extrusion Capacity (USMCA, EU-CBAM)
- 4.2.5 Gigacasting-Extrusion Hybrid Chassis Architectures in Premium EVs
- 4.2.6 Cost-Out & Scrap-Recycling Gains from Closed-Loop Extrusion Lines
- 4.3 Market Restraints
- 4.3.1 LME Aluminum Price Volatility & Supply-Chain Speculation
- 4.3.2 Scarcity of More than 35 MN Press Lines for Large EV Profiles
- 4.3.3 EU-CBAM & Regional Carbon-Tax Pass-Through Risk
- 4.3.4 Engineering Plastics & CFRP Alternatives for Interiors
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value (USD))
- 5.1 By Component Type
- 5.1.1 Body Structure
- 5.1.2 Crash-Management Systems
- 5.1.3 Battery Enclosures and Thermal Modules
- 5.1.4 Exterior Trim and Roof Rails
- 5.1.5 Interior Modules
- 5.1.6 Other Components
- 5.2 By Vehicle Type
- 5.2.1 Passenger Cars
- 5.2.2 Light Commercial Vehicles
- 5.2.3 Medium and Heavy-Duty Trucks
- 5.2.4 Buses and Coaches
- 5.3 By Alloy Series
- 5.3.1 6xxx Heat-Treatable
- 5.3.2 7xxx High-Strength
- 5.3.3 5xxx Non-Heat-Treatable
- 5.3.4 Scandium & Novel Alloys
- 5.4 By Press Capacity
- 5.4.1 Less than or equal to 15 MN
- 5.4.2 16 to 25 MN
- 5.4.3 26 to 35 MN
- 5.4.4 More than 35 MN
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Rest of North America
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Spain
- 5.5.3.5 Russia
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Rest of Asia-Pacific
- 5.5.5 Middle-East and Africa
- 5.5.5.1 United Arab Emirates
- 5.5.5.2 Saudi Arabia
- 5.5.5.3 Turkey
- 5.5.5.4 Egypt
- 5.5.5.5 South Africa
- 5.5.5.6 Rest of Middle-East and Africa
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, SWOT Analysis, and Recent Developments)
- 6.4.1 Constellium SE
- 6.4.2 Novelis Inc.
- 6.4.3 Norsk Hydro ASA
- 6.4.4 Kaiser Aluminum Corp.
- 6.4.5 UACJ Corp.
- 6.4.6 Arconic Corp.
- 6.4.7 Kobe Steel Ltd.
- 6.4.8 Benteler International
- 6.4.9 Bonnell Aluminum
- 6.4.10 Hindalco Industries Ltd.
- 6.4.11 Guangdong Hongtu
- 6.4.12 ETEM Automotive
- 6.4.13 Talco Aluminium Company
- 6.4.14 Granges AB
- 6.4.15 Press-Metal Aluminium
- 6.4.16 Sapa Extrusions
- 6.4.17 Exlabesa
- 6.4.18 Walter Klein GmbH
- 6.4.19 Omnimax International
- 6.4.20 Innoval Technology
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment

