PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2123317

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2123317
Server Microprocessor - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the server microprocessor market size is projected to expand from USD 19.21 billion in 2025 and USD 20.66 billion in 2026 to USD 29.74 billion by 2031, registering a CAGR of 7.56% between 2026 to 2031.
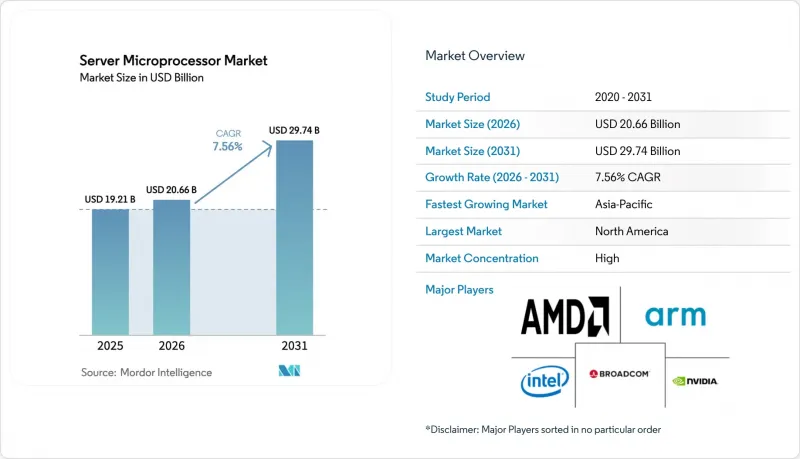
This report is Segmented by Processor Type (APU, CPU, GPU, and More), Instruction-Set Architecture (x86, ARM, RISC-V, and More, Core-Count Bracket (Less Than or Equal To 8 Cores, 9-32 Cores), and More), Fabrication Process Node (Less Than or Equal To 7nm, 8-14nm, and More), End-User Industry (Hyperscale Cloud, Enterprise, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Server Microprocessor Market Trends and Insights
Rising Demand for High-Performance, Energy-Efficient CPUs
Data-center operators are linking procurement directly to performance-per-watt metrics because energy now represents more than 30% of total cost of ownership in hyperscale facilities. Vendors have responded with silicon fabricated at 3 nanometers that cuts wattage by a third while doubling vector throughput. AWS Graviton4 instances show 30% better price-performance over comparable x86 virtual machines, validating Arm-based designs in mainstream cloud workloads. Intel's Xeon 6 Sierra Forest variant relies exclusively on efficiency cores to hit a 205-watt TDP target, supporting sustainability mandates without major code rewrites. Telecom operators substituting outdoor cabinets for air-conditioned halls are demanding even tighter envelopes, so chipmakers are integrating on-package voltage regulators and dynamic power-gating functions. These shifts ensure that the server microprocessor market continues to migrate toward architectures optimized for watts rather than pure clock speed.
Expansion of Hyperscale Data Centers Worldwide
More than 900 hyperscale facilities entered service during 2024-2025, and cumulative capital expenditure topped USD 200 billion, led by operators locating campuses near low-cost renewable energy grids in Saudi Arabia, India, and the Nordics. Rack designs emphasize multi-socket boards that host CPU, GPU, and network acceleration tiles on one interposer, tightening thermal coupling and demanding advanced packaging expertise. AWS, Google, and Meta have each shifted at least 1/3 of their new web-serving capacity to Arm-based processors that promise lower silicon bill of materials. Emerging markets are mandating local data residency under converging privacy laws, so operators must replicate compute clusters regionally, further expanding total socket demand. As this footprint grows, the server microprocessor market benefits from volume elasticity and a broader price band.
Ongoing Semiconductor Supply-Chain Disruptions
TSMC's 3 nanometer lines ran at 85% utilization in Q3 2025, yet wafer demand exceeded supply by 20%, lengthening lead times to 16 weeks. Export restrictions on EUV tools block Chinese fabs from matching leading-edge nodes, fragmenting capacity, and raising risk premiums on contingency inventory. Samsung's gate-all-around ramp and Intel's 18-angstrom plan remain subscale, so a single earthquake or geopolitical flare-up could choke more than half of global server chip output. Vendors pass surcharges straight into contract pricing; AMD's Q2 2025 gross margin slid 200 basis points due to expedited wafer fees. Design teams are splitting dies into smaller chiplets made on mature nodes, but that strategy increases packaging complexity and yields new sources of delay.
Other drivers and restraints analyzed in the detailed report include:
- Cloud-Based AI and ML Workload Proliferation
- 5G-Enabled Edge-Computing Roll-outs
- Strict Data-Center Sustainability Regulations
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
GPU shipments expanded at an 8.72% CAGR during 2026-2031 and cut into the CPU's 70.53% revenue lead as AI inference migrated to tensor engines, a trend that will keep the server microprocessor market in transition through 2031. GPUs like NVIDIA Blackwell now deliver 20 petaflops FP4 performance while paired with Arm-based Grace CPUs over NVLink, enabling rack designs that beat sub-1.3 PUE targets. FPGAs remain niche in unit terms but are critical for encryption offload and compression, trimming CPU cycles by 30% for cloud operators. Integrated APU designs are a winning edge in appliance slots where fans and discrete cards are impractical. ASIC accelerators from Google and AWS achieve 2-3 times better performance per watt than GPUs for specific inference patterns.
Heterogeneous chiplet packages enable vendors to slot CPUs, GPUs, and network dies under a single heat spreader, shaving mask costs and improving time-to-market. The server microprocessor industry therefore pivots from monolithic core count races to mixed-die portfolio strategies that maximize silicon area efficiency. Legacy CPU revenues are flattening, but the overall server microprocessor market continues to grow because accelerators carry higher average selling prices. Procurement teams are evaluating total rack cost rather than socket price, enabling vendors that deliver integrated stacks to secure multiyear supply agreements.
x86 retained 64.91% share in 2025 and remains the compatibility anchor for enterprise software, yet Arm captured a quarter of new sockets, and RISC-V is projected to grow at a 7.97% CAGR on a royalty-free model that resonates with hyperscalers. Qualcomm's USD 1.5 billion Ventana acquisition signaled traditional mobile leaders entering the server space to hedge against rising Arm license fees. China's preference for open governance aligns with its semiconductor sovereignty objectives, so domestic vendors are betting on RISC-V for cloud build-outs.
The competitive narrative now hinges on ecosystem tooling and long-tail software support rather than front-end performance, positioning low-cost RISC-V boards as credible for microservices and caching tiers. Arm's success in bespoke cloud silicon threatens merchant suppliers on margin, but it validates the diversity of design and ensures that the server microprocessor market avoids single-vendor lock-in. Standardization groups are aligning firmware interfaces across ISAs to shorten application migration times, which should keep the server microprocessor industry dynamic through the forecast period.
Complete Report Scope:
- By Processor Type
- APU
- CPU
- GPU
- FPGA
- ASIC Accelerators
- By Instruction-Set Architecture
- x86
- ARM
- RISC-V
- Power
- SPARC and Others
- Consumer Electronics
- By Core-Count Bracket
- Less Than or Equal to 8 Cores
- 9-32 Cores
- 33-64 Cores
- More than 64 Cores
- By Fabrication Process Node
- Less Than or Equal to 7 nm
- 8-14 nm
- 15-28 nm
- More than 28 nm
- By End-User Industry
- Hyperscale Cloud Providers
- Enterprise Data-Centers
- Telecom/ Edge Operators
- HPC and Supercomputing
- Other End-User Industries
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- ASEAN
- Rest of Asia-Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- North America
Geography Analysis
North America generated 39.52% of 2025 revenue, bolstered by more than USD 80 billion in annual hyperscale capital expenditure from AWS, Azure, Google Cloud and Meta. CHIPS Act incentives worth USD 52.7 billion aim to reshore 20% of leading-edge logic by 2030, yet domestic wafer costs remain up to 40% higher than Asian fabs, pressuring gross margins. Canada and Mexico add incremental volume through back-end assembly and test operations that leverage USMCA trade provisions.
Asia-Pacific is projected to post the fastest 9.11% CAGR, driven by China's domestic Arm and RISC-V initiatives, India's USD 12.7 billion AWS investment and Southeast Asia's neutral colocation growth AWS. Chinese hyperscalers such as Alibaba and Tencent already deploy in-house 128-core Arm processors, demonstrating technology parity despite export controls. Japan and South Korea focus on memory and foundry services rather than server CPU design, but still benefit from regional stimuli targeting chip sovereignty.
Europe, South America, the Middle East, and Africa collectively hold under one-quarter of demand yet are expanding as data-sovereignty laws force local storage of sensitive workloads. The EU's EUR 43 billion Chips Act funds fabs in Germany and Italy, though the region still relies on Asian contract manufacturing for most server processors. The Middle East's NEOM campus and UAE AI investments require liquid-cooled racks due to ambient temperatures, adding cost premiums but fostering regional specialization. South American growth hinges on improved fiber infrastructure, while Africa's nascent market leans on refurbished x86 equipment until grid reliability improves.
- Intel Corporation
- Advanced Micro Devices, Inc.
- NVIDIA Corporation
- Arm Ltd.
- Broadcom Inc.
- Marvell Technology, Inc.
- Ampere Computing LLC
- International Business Machines Corporation
- Huawei Technologies Co., Ltd.
- Fujitsu Limited
- Samsung Electronics Co., Ltd.
- Taiwan Semiconductor Manufacturing Company Limited
- Texas Instruments Incorporated
- MediaTek Inc.
- Alibaba Group Holding Ltd. (T-Head)
- SiFive, Inc.
- Graphcore Limited
- Socionext Inc.
- Tenstorrent Inc.
- Ventana Micro Systems Inc.
- Oracle Corporation
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Demand for High-performance, Energy-efficient CPUs
- 4.2.2 Expansion of Hyperscale Data-centers Worldwide
- 4.2.3 Cloud-based AI/ML Workload Proliferation
- 4.2.4 5G-enabled Edge-computing Roll-outs
- 4.2.5 Chiplet-based Modular Design Adoption
- 4.2.6 Government Semiconductor-sovereignty Programs
- 4.3 Market Restraints
- 4.3.1 Declining on-prem Enterprise Server Budgets
- 4.3.2 Ongoing Semiconductor Supply-chain Disruptions
- 4.3.3 Escalating Licensing Costs of Proprietary ISAs
- 4.3.4 Strict Data-center Sustainability Regulations
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Processor Type
- 5.1.1 APU
- 5.1.2 CPU
- 5.1.3 GPU
- 5.1.4 FPGA
- 5.1.5 ASIC Accelerators
- 5.2 By Instruction-Set Architecture
- 5.2.1 x86
- 5.2.2 ARM
- 5.2.3 RISC-V
- 5.2.4 Power
- 5.2.5 SPARC and Others
- 5.2.6 Consumer Electronics
- 5.3 By Core-Count Bracket
- 5.3.1 Less Than or Equal to 8 Cores
- 5.3.2 9-32 Cores
- 5.3.3 33-64 Cores
- 5.3.4 More than 64 Cores
- 5.4 By Fabrication Process Node
- 5.4.1 Less Than or Equal to 7 nm
- 5.4.2 8-14 nm
- 5.4.3 15-28 nm
- 5.4.4 More than 28 nm
- 5.5 By End-User Industry
- 5.5.1 Hyperscale Cloud Providers
- 5.5.2 Enterprise Data-Centers
- 5.5.3 Telecom/ Edge Operators
- 5.5.4 HPC and Supercomputing
- 5.5.5 Other End-User Industries
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Rest of Europe
- 5.6.4 Asia-Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 India
- 5.6.4.4 South Korea
- 5.6.4.5 ASEAN
- 5.6.4.6 Rest of Asia-Pacific
- 5.6.5 Middle East
- 5.6.5.1 Saudi Arabia
- 5.6.5.2 United Arab Emirates
- 5.6.5.3 Rest of Middle East
- 5.6.6 Africa
- 5.6.6.1 South Africa
- 5.6.6.2 Nigeria
- 5.6.6.3 Rest of Africa
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 Intel Corporation
- 6.4.2 Advanced Micro Devices, Inc.
- 6.4.3 NVIDIA Corporation
- 6.4.4 Arm Ltd.
- 6.4.5 Broadcom Inc.
- 6.4.6 Marvell Technology, Inc.
- 6.4.7 Ampere Computing LLC
- 6.4.8 International Business Machines Corporation
- 6.4.9 Huawei Technologies Co., Ltd.
- 6.4.10 Fujitsu Limited
- 6.4.11 Samsung Electronics Co., Ltd.
- 6.4.12 Taiwan Semiconductor Manufacturing Company Limited
- 6.4.13 Texas Instruments Incorporated
- 6.4.14 MediaTek Inc.
- 6.4.15 Alibaba Group Holding Ltd. (T-Head)
- 6.4.16 SiFive, Inc.
- 6.4.17 Graphcore Limited
- 6.4.18 Socionext Inc.
- 6.4.19 Tenstorrent Inc.
- 6.4.20 Ventana Micro Systems Inc.
- 6.4.21 Oracle Corporation
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

