PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2123356

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2123356
Gastroesophageal Reflux Disease - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the gastroesophageal reflux disease market size is projected to expand from USD 6.62 billion in 2025 and USD 6.93 billion in 2026 to USD 8.95 billion by 2031, registering a CAGR of 5.25% between 2026 to 2031.
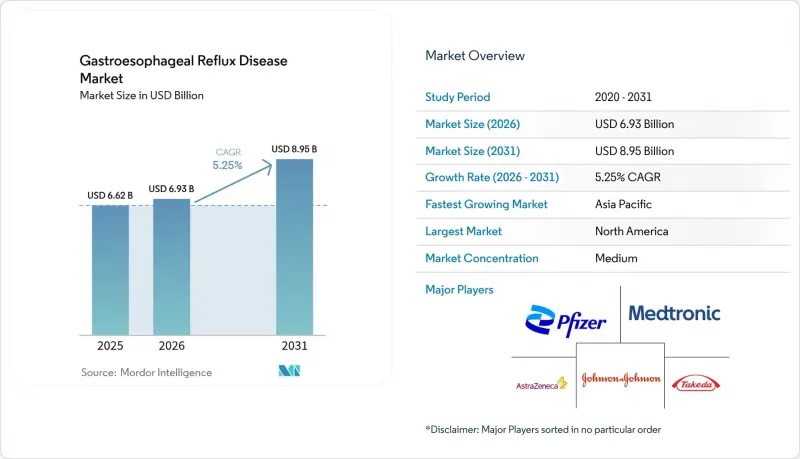
This report is Segmented by Solution Type (Diagnostics [Endoscopy, PH & Impedance Monitoring, and More], Therapeutics [Phramacological and More]), Disease Phenotype (NERD, and More), Line of Therapy (First-Line, and More), Patient Demographics (Pediatric, Adult, Geriatric), End User (Hospitals, and More), and Geography (North America, and More). Market Forecasts are Provided in Value (USD).
Global Gastroesophageal Reflux Disease Market Trends and Insights
Rising GERD Prevalence from Obesity and Ageing
Global obesity reached 42.4% of U.S. adults in 2024, while those aged >=65 formed 17.3% of the world's population, intensifying reflux incidence. Visceral fat raises intra-abdominal pressure and drives transient lower-esophageal sphincter relaxations, explaining why bariatric-surgery candidates show erosive esophagitis prevalence above 30% versus 10% in age-matched controls. Japan logged an 18% rise in GERD diagnoses among citizens over 70 between 2020 and 2025 as life expectancy lengthened and calcium-channel-blocker use climbed. China saw reflux consultations surge 22% in tier-1 cities from 2023-2025 amid Westernized diets and sedentary office work. These demographics underpin sustained demand for geriatric-friendly formulations and Barrett's surveillance.
OTC Availability and Generic Penetration of Acid Suppressants
Over-the-counter omeprazole and esomeprazole captured 35% of U.S. PPI unit volume in 2025, enlarging the treated pool beyond formally diagnosed cases. Indian generic pantoprazole sold below USD 0.05 per 20 mg dose in 2024, spurring a 28% pharmacy-sales jump across tier-2 cities. Brazil permitted OTC pantoprazole in August 2025, a change distributors expect to lift national consumption 15% within two years. While price competition trims branded margins-Protonix revenue slipped 12% in 2025 despite flat volume-innovators are pivoting to PCABs and alginate blends.
Long-Term PPI Safety Concerns Triggering Regulatory Scrutiny
The European Medicines Agency ordered new PPI labels in January 2025 warning of hypomagnesemia after three months of continuous use. A JAMA Internal Medicine cohort of 73 000 users showed a 1.44 hazard ratio for dementia, prompting FDA advisory review in September 2025. By late 2025, 54% of U.S. primary-care doctors attempted PPI tapering within 12 weeks of uncomplicated GERD onset, up from 38% in 2023. Japan's regulator now demands five-year post-marketing bone-density studies, straining smaller generic makers
Other drivers and restraints analyzed in the detailed report include:
- Breakthroughs in Minimally Invasive Anti-Reflux Devices and Diagnostics
- Surge in Single-Use Endoscopy Driven by Infection-Control Mandates
- Rapid Price Erosion Following Blockbuster Patent Expiries
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Endoscopy, impedance-pH monitoring, manometry, and imaging together expanded at a 9.33% CAGR between 2026 and 2031, almost double the 5.25% pace of the overall Gastroesophageal Reflux Disease market. This outperformance reflects infection-control mandates that nudged providers toward single-use scopes priced at USD 300-500 per use and cloud-linked tests that clarify refractory phenotypes before high-cost interventions. Therapeutics still delivered an 84.32% revenue contribution in 2025, anchored by low-priced proton-pump inhibitors and an embryonic but fast-moving potassium-competitive acid-blocker class that wins share in severe erosive esophagitis.
The diagnostic tailwind is strengthened by guideline changes recommending Barrett's surveillance every three years for chronic reflux patients aged >50, a protocol that widens the procedure pool by an estimated 2.1 million cases in North America alone. Device and procedural lines-laparoscopic fundoplication, endoscopic suturing, magnetic sphincter augmentation, and radiofrequency ablation-migrated from tertiary centers to ambulatory surgical suites, helped by Medicare claims that showed a 29% jump in community facility volumes between 2024 and 2025. Digital therapeutics remain small but logged 1.4 million downloads in 2025, and early evidence suggests smartphone-based posture coaching can cut daily PPI use, a metric payers in Germany now reimburse under chronic-disease codes.
Non-erosive reflux disease contributed 67.25% of 2025 revenue, sustained by high prevalence and chronic pharmacotherapy dependence that translates into repeat prescription income, the single largest annuity line in the Gastroesophageal Reflux Disease market. Erosive esophagitis, defined by Los Angeles grades A-D, supplied the remainder of uncomplicated cases and spurred device usage, as grade C and D lesions often trigger fundoplication or LINX implantation when pharmacologic control stalls.
Barrett's esophagus and other complicated GERD phenotypes are advancing at an 8.53% CAGR through 2031 after 2024 guidelines lowered the male screening age to 50 and endorsed radiofrequency ablation protocols that record 92% intestinal-metaplasia eradication. Medicare actuaries estimate that a population-based Barrett's program would insert 800 000 extra endoscopies annually if approved, a surge that would add roughly USD 320 million in incremental diagnostic revenue to the Gastroesophageal Reflux Disease market size for 2028. Down-staged NERD users generate fewer scopes-0.3 per patient over five years-but higher OTC PPI and alginate turns, a pattern that benefits generics producers whose volumes outstrip branded scripts four-to-one in most emerging economies.
Complete Report Scope:
- By Solution Type
- Diagnostics
- Endoscopy
- pH & Impedance Monitoring
- Manometry
- Imaging & Ancillary Tests
- Therapeutics
- Phramacological
- Proton Pump Inhibitors (PPIs)
- Potassium-Competitive Acid Blockers (PCABs)
- Histamine-2 Receptor Antagonists (H2RAs)
- Others (Combinational Formulations, Prokinetic Agents, Alginates)
- Device / Procedural
- Laparoscopic Fundoplication
- Anti-Reflux Endoscopic Suturing / Plication
- Magnetic Sphincter Augmentation
- Transoral Incisionless Fundoplication (TIF)
- Others (Radio-Frequency Ablation, LES Electrical Stimulation)
- Lifestyle & Digital Therapeutics
- Phramacological
- Diagnostics
- By Disease Phenotype
- Non-Erosive Reflux Disease (NERD)
- Erosive Esophagitis (Grades A-D)
- Barrett's Esophagus / Complicated GERD
- By Line of Therapy
- First-Line Empiric Management
- Maintenance / Step-Down Therapy
- Refractory / Rescue Treatment
- By Patient Demographics
- Pediatric (0-17 yrs)
- Adult (18-64 yrs)
- Geriatric (65 yrs +)
- By End User
- Hospitals
- Ambulatory Surgical Centres
- Specialty / GI Clinics
- Home-care Settings
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America contributed 37.34% revenue in 2025, far ahead of any other region. The market benefits from high payer coverage, early PCAB uptake, and a deep installer base for magnetic sphincter augmentation. Single-use endoscopy also penetrates fastest here because legal exposure around infection drives proactive procurement. ASC migration is most pronounced in Texas, Florida, and California, where light certificate-of-need barriers allow rapid capacity swings. Although PCAB scripts accelerate, step-therapy rules keep low-cost PPIs dominant first line, a fact that tempers overall price lifts yet boosts unit turns in the Gastroesophageal Reflux Disease market.
Asia-Pacific is on track for a 7.42% CAGR through 2031, the quickest worldwide, as obesity rises in China and India and public programs pilot Barrett's screening that funnels more scopes into provincial hospitals. China's ten-province pilot will finance 500,000 endoscopies by 2027, creating volume that local manufacturers such as Aohua are ready to supply. India exported USD 420 million in generic PPIs during 2025, handing domestic firms global reach and margin despite sub-dollar pricing at home. Japan shows a decade-deep PCAB curve, with vonoprazan cornering 40% of new GERD starts in 2025, an adoption blueprint for the wider region.
Europe's mature PPI environment slows top-line growth to low single digits, yet single-use scopes and PCABs revive momentum. Germany, the United Kingdom, and France allocate infection-prevention budgets that speed disposable scope buys, whereas southern and eastern markets stick with reused fleets for capital reasons. Regulatory coherence under the European Medicines Agency accelerates device approvals but also amplifies safety alerts that trim long-term PPI days-of-therapy. South America's expansion is steady but capped by reimbursement ceilings; Brazil's OTC PPI penetration rose after ANVISA's 2025 rule change, but high-cost devices stay a private-pay preserve.
The Middle East and Africa fracture into high-income Gulf Cooperation Council states investing in tertiary GI hubs and sub-Saharan economies plagued by endoscope shortages. Nigeria reported more than four-week consumable stock-outs at 62% of public hospitals in 2025. Sub-Saharan Africa averages 0.8 scopes per million inhabitants, compared with 47 per million in OECD peers, a structural obstacle that confines screening to late-stage disease and keeps pharmaceutical volume high in the regional Gastroesophageal Reflux Disease market.
- AstraZeneca
- Bayer
- Boston Scientific
- Cipla
- Dr. Reddy's Laboratories
- Eisai
- EndoGastric Solutions
- EndoStim BV
- FUJIFILM
- GlaxoSmithKline
- Ironwood Pharmaceuticals
- Johnson & Johnson (Incl. Ethicon & Torax)
- Mederi Therapeutics
- Medtronic
- Novartis
- Olympus
- Perrigo Company
- Pfizer
- Phathom Pharmaceuticals
- Sanofi
- Sun Pharmaceuticals Industries
- Takeda Pharmaceutical Co.
- Teva Pharmaceutical Industries
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising GERD Prevalence from Obesity & Ageing
- 4.2.2 OTC Availability & Generic Penetration of Acid Suppressants
- 4.2.3 Breakthroughs in Minimally Invasive Anti-Reflux Devices & Diagnostics
- 4.2.4 Surge In Single-Use Endoscopy Driven by Infection-Control Mandates
- 4.2.5 Commercialization of Potassium-Competitive Acid Blockers (PCABS)
- 4.2.6 AI-Enabled Ph-Wearables Powering Tele-Gastroenterology Services
- 4.3 Market Restraints
- 4.3.1 Long-Term PPI Safety Concerns Triggering Regulatory Scrutiny
- 4.3.2 Rapid Price Erosion Following Blockbuster Patent Expiries
- 4.3.3 Weak Reimbursement for Novel Anti-Reflux Procedures in EMs
- 4.3.4 Supply-Chain Fragility for Endoscopy Consumables in LMICs
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value in USD)
- 5.1 By Solution Type
- 5.1.1 Diagnostics
- 5.1.1.1 Endoscopy
- 5.1.1.2 pH & Impedance Monitoring
- 5.1.1.3 Manometry
- 5.1.1.4 Imaging & Ancillary Tests
- 5.1.2 Therapeutics
- 5.1.2.1 Phramacological
- 5.1.2.1.1 Proton Pump Inhibitors (PPIs)
- 5.1.2.1.2 Potassium-Competitive Acid Blockers (PCABs)
- 5.1.2.1.3 Histamine-2 Receptor Antagonists (H2RAs)
- 5.1.2.1.4 Others (Combinational Formulations, Prokinetic Agents, Alginates)
- 5.1.2.2 Device / Procedural
- 5.1.2.2.1 Laparoscopic Fundoplication
- 5.1.2.2.2 Anti-Reflux Endoscopic Suturing / Plication
- 5.1.2.2.3 Magnetic Sphincter Augmentation
- 5.1.2.2.4 Transoral Incisionless Fundoplication (TIF)
- 5.1.2.2.5 Others (Radio-Frequency Ablation, LES Electrical Stimulation)
- 5.1.2.3 Lifestyle & Digital Therapeutics
- 5.1.2.1 Phramacological
- 5.1.1 Diagnostics
- 5.2 By Disease Phenotype
- 5.2.1 Non-Erosive Reflux Disease (NERD)
- 5.2.2 Erosive Esophagitis (Grades A-D)
- 5.2.3 Barrett's Esophagus / Complicated GERD
- 5.3 By Line of Therapy
- 5.3.1 First-Line Empiric Management
- 5.3.2 Maintenance / Step-Down Therapy
- 5.3.3 Refractory / Rescue Treatment
- 5.4 By Patient Demographics
- 5.4.1 Pediatric (0-17 yrs)
- 5.4.2 Adult (18-64 yrs)
- 5.4.3 Geriatric (65 yrs +)
- 5.5 By End User
- 5.5.1 Hospitals
- 5.5.2 Ambulatory Surgical Centres
- 5.5.3 Specialty / GI Clinics
- 5.5.4 Home-care Settings
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 France
- 5.6.2.3 United Kingdom
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 India
- 5.6.3.4 South Korea
- 5.6.3.5 Australia
- 5.6.3.6 Rest of Asia-Pacific
- 5.6.4 Middle East & Africa
- 5.6.4.1 GCC
- 5.6.4.2 South Africa
- 5.6.4.3 Rest of Middle East & Africa
- 5.6.5 South America
- 5.6.5.1 Brazil
- 5.6.5.2 Argentina
- 5.6.5.3 Rest of South America
- 5.6.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.3.1 AstraZeneca
- 6.3.2 Bayer AG
- 6.3.3 Boston Scientific Corporation
- 6.3.4 Cipla Ltd.
- 6.3.5 Dr. Reddy's Laboratories
- 6.3.6 Eisai Co., Ltd.
- 6.3.7 EndoGastric Solutions
- 6.3.8 EndoStim BV
- 6.3.9 Fujifilm Holdings
- 6.3.10 GlaxoSmithKline plc
- 6.3.11 Ironwood Pharmaceuticals
- 6.3.12 Johnson & Johnson (Incl. Ethicon & Torax)
- 6.3.13 Mederi Therapeutics
- 6.3.14 Medtronic plc
- 6.3.15 Novartis AG
- 6.3.16 Olympus Corporation
- 6.3.17 Perrigo Company
- 6.3.18 Pfizer
- 6.3.19 Phathom Pharmaceuticals
- 6.3.20 Sanofi
- 6.3.21 Sun Pharmaceutical Industries
- 6.3.22 Takeda Pharmaceutical Co.
- 6.3.23 Teva Pharmaceutical Industries
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment

