PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2123384

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2123384
Functional Safety - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the functional safety market size is expected to increase from USD 7.11 billion in 2025 to USD 7.84 billion in 2026 and reach USD 12.82 billion by 2031, growing at a CAGR of 10.34% over 2026-2031.
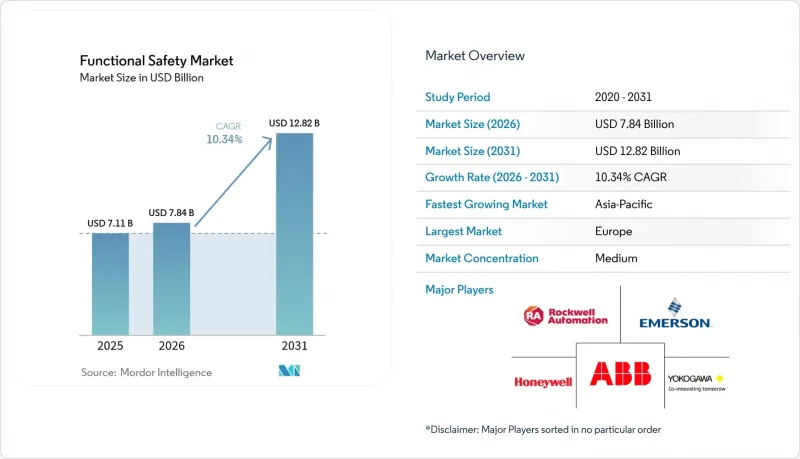
This report is Segmented by Device Type (Safety Sensors, Safety Switches, and More), Safety Systems (Burner Management Systems, Emergency Shutdown Systems, and More), Services (Testing, Inspection and Certification, Design, Engineering and Maintenance, and More), End-User Industry (Oil and Gas, Food and Beverage, Automotive, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Functional Safety Market Trends and Insights
Stringent Global Safety Regulations and Standards
Regulatory mandates remain the prime catalyst for new installations and retrofits. IEC TS 61508-3-2:2024 formalized model-checking and theorem-proving techniques, cutting certification cycles for programmable safety systems by up to 20%. ISO 26262 Edition 3 draft texts circulated during 2024-2025 extend ASIL-D coverage to Level 3-4 automated-driving functions, pushing chipset and controller redesign among tier-one automotive suppliers. Europe's Machinery Regulation (EU) 2023/1230 introduces digital product passports from 2027, accelerating brownfield upgrades, while OSHA's March 2025 revision to 29 CFR 1910.119 requires quantified risk analysis for every SIL-rated loop in United States refineries.
Expansion of Industry 4.0 and Industrial Automation
Edge computing and digital twin rollouts are embedding functional safety logic into broader automation stacks. Siemens connected its Simatic Safety Integrated family to Industrial Edge in 2024, enabling deterministic response times below 10 milliseconds and synchronized cloud analytics for predictive maintenance. Rockwell Automation consolidated standard and safety control in the FactoryTalk GuardLogix 5580 line, trimming panel footprints by nearly 40% for discrete manufacturers. Wireless, IO-Link-enabled safety sensors launched by Pepperl+Fuchs in 2025 are feeding real-time diagnostics into MES platforms, cutting line downtime by up to 25% in automotive sites. China's Made-in-China 2025 roadmap and India's Production-Linked Incentive scheme channel new capex into automation, sustaining above-global growth in Asia-Pacific.
High Upfront Cost of SIL-Certified Components and Systems
SIL-rated hardware sells at two to three times the price of standard automation equipment, stretching capital budgets for mid-tier operators. ABB's AC 800M High Integrity chassis lists at USD 18,000-25,000, compared with USD 6,000-8,000 for the non-safety variant, while SICK's deTec4 laser scanners cost roughly USD 4,500-6,000, quadruple the cost of a conventional distance sensor. Validation studies frequently add six-figure fees, prompting many Southeast Asian and Latin American SMEs to defer upgrades in favor of higher insurance premiums or extended maintenance windows.
Other drivers and restraints analyzed in the detailed report include:
- Heightened Incident-Related Scrutiny in Oil and Gas and Power Sectors
- Integration of Functional Safety with Industrial Cybersecurity
- Complexity of Retrofitting Legacy Brownfield Facilities
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Safety sensors accounted for 33.78% of the functional safety market in 2025 as brownfield facilities replaced electromechanical guards with electronic light curtains, laser scanners, and magnetic interlocks. Demand is robust in oil and gas and food processing, where operators favor contactless sensing to minimize mechanical wear. Programmable safety systems, however, are projected to record an 11.78% CAGR, reflecting a pivot toward software-defined logic that decouples application code from hardware, allowing remote parameter updates without jeopardizing integrity.
The functional safety market continues to integrate safety inputs, logic solvers, and final elements into unified platforms. Pilz's PSS 4000 and Omron's NX-series controllers embed SIL 3 functions alongside standard automation, cutting hardware line items by nearly a third. Contactless RFID switches are reducing nuisance trips by roughly 45%, while AI-enabled self-diagnostic sensors transmit remaining useful life data, lowering unplanned downtime in packaging and assembly lines.
Emergency shutdown systems held 28.67% of the functional safety market share in 2025 owing to their universal deployment in refineries, LNG terminals, and petrochemical complexes. Simultaneously, driven by methane-emission regulations that deter flaring and promote enclosed overpressure protection, high-integrity pressure protection systems are poised for an 11.73% CAGR expansion during the forecast period. These systems play a critical role in ensuring operational safety and compliance with environmental standards, further driving their adoption across various industries.
Modern distributed control architectures blur boundaries between process control and safety. Honeywell's Experion PKS now embeds SIL-certified logic within the same environment as regulatory loops, aiding operator situational awareness. Emerson's wireless DeltaV SIS transmitters shave USD 500-1,000 per loop on greenfield LNG builds, encouraging adoption in cost-sensitive Middle East projects. Digital twins used during HIPPS design have cut factory-acceptance test time by nearly half, shortening time-to-first-gas for offshore fields.
Complete Report Scope:
- By Device Type
- Safety Sensors
- Safety Controllers/Modules/Relays
- Safety Switches
- Programmable Safety Systems
- Emergency Stop Devices
- Final Control Elements
- Other Device Types
- By Safety Systems
- Burner Management Systems
- Turbomachinery Control Systems
- High-Integrity Pressure Protection Systems
- Fire and Gas Monitoring Control Systems
- Emergency Shutdown Systems
- Supervisory Control and Data Acquisition Systems
- Distributed Control Systems
- By Services
- Testing, Inspection and Certification
- Design, Engineering and Maintenance
- Training and Consulting Services
- By End-User Industry
- Oil and Gas
- Power Generation
- Food and Beverage
- Pharmaceutical
- Automotive
- Other End-User Industries
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Italy
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia Pacific
- Middle East and Africa
- Middle East
- United Arab Emirates
- Saudi Arabia
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- Middle East
- North America
Geography Analysis
Europe accounted for 34.89% of the functional safety market share in 2025, led by Germany, France, and the United Kingdom, where CE marking laws and high labor costs sustain automation spending. The incoming Machinery Regulation's digital passports will catalyze another retrofit spike before 2027. Southern Europe is channeling stimulus into cleaner combined-cycle plants, translating into fresh orders for SIL-rated turbomachinery controls.
Asia-Pacific is projected to post an 11.39% CAGR through 2031. China's alignment with GB/T 20438 and IEC 61508, and subsidies under Made-in-China 2025, are driving the mass deployment of safety controllers in electronics and machinery plants. India's USD 1.8 billion Production-Linked Incentive allocation for automation is already visible in pharmaceutical greenfields. Japan and South Korea, faced with aging workforces and intense semiconductor expansion, are specifying SIL-2 or higher safety systems for robotics and battery cell lines.
North America represents roughly one-quarter of global revenue, underpinned by brownfield retrofits in Gulf Coast and Canadian oil sands facilities. OSHA's tighter proof-test windows, NERC's battery-storage mandates, and BSEE subsea rules converge to fuel the adoption of emergency shutdown and HIPPS packages. Mexico and Brazil provide incremental growth through midstream expansion and pre-salt field upgrades, while the Middle East and Africa continue to order integrated safety-instrumented solutions for mega-refineries and gas-to-liquids complexes.
- Rockwell Automation Inc.
- Emerson Electric Company
- Honeywell International Inc.
- ABB Ltd
- Yokogawa Electric Corporation
- Schneider Electric SE
- Siemens AG
- General Electric Company
- Omron Corporation
- SICK AG
- Panasonic Corporation
- Pepperl+Fuchs SE
- Banner Engineering Corporation
- Pilz GmbH and Co. KG
- HIMA Paul Hildebrandt GmbH
- Mitsubishi Electric Corporation
- Phoenix Contact GmbH and Co. KG
- Turck GmbH and Co. KG
- Balluff GmbH
- IDEC Corporation
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Stringent Global Safety Regulations and Standards (IEC 61508, ISO 26262)
- 4.2.2 Expansion of Industry 4.0 and Industrial Automation
- 4.2.3 Heightened Incident-Related Scrutiny in Oil and Gas, and Power Sectors
- 4.2.4 Integration of Functional Safety with Industrial Cybersecurity
- 4.2.5 Emergence of SIL-Certified AI/ML Shutdown Algorithms
- 4.2.6 Rise of Safety-as-a-Service Subscription Models for SMEs
- 4.3 Market Restraints
- 4.3.1 High Upfront Cost of SIL-Certified Components and Systems
- 4.3.2 Complexity of Retrofitting Legacy Brown-Field Facilities
- 4.3.3 Shortage of Certified Functional Safety Engineers
- 4.3.4 Liability Ambiguity for OTA Safety-Critical Software Updates
- 4.4 Industry Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Device Type
- 5.1.1 Safety Sensors
- 5.1.2 Safety Controllers/Modules/Relays
- 5.1.3 Safety Switches
- 5.1.4 Programmable Safety Systems
- 5.1.5 Emergency Stop Devices
- 5.1.6 Final Control Elements
- 5.1.7 Other Device Types
- 5.2 By Safety Systems
- 5.2.1 Burner Management Systems
- 5.2.2 Turbomachinery Control Systems
- 5.2.3 High-Integrity Pressure Protection Systems
- 5.2.4 Fire and Gas Monitoring Control Systems
- 5.2.5 Emergency Shutdown Systems
- 5.2.6 Supervisory Control and Data Acquisition Systems
- 5.2.7 Distributed Control Systems
- 5.3 By Services
- 5.3.1 Testing, Inspection and Certification
- 5.3.2 Design, Engineering and Maintenance
- 5.3.3 Training and Consulting Services
- 5.4 By End-User Industry
- 5.4.1 Oil and Gas
- 5.4.2 Power Generation
- 5.4.3 Food and Beverage
- 5.4.4 Pharmaceutical
- 5.4.5 Automotive
- 5.4.6 Other End-User Industries
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 United Kingdom
- 5.5.3.2 Germany
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Rest of Europe
- 5.5.4 Asia Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Rest of Asia Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 United Arab Emirates
- 5.5.5.1.2 Saudi Arabia
- 5.5.5.1.3 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Egypt
- 5.5.5.2.3 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 Rockwell Automation Inc.
- 6.4.2 Emerson Electric Company
- 6.4.3 Honeywell International Inc.
- 6.4.4 ABB Ltd
- 6.4.5 Yokogawa Electric Corporation
- 6.4.6 Schneider Electric SE
- 6.4.7 Siemens AG
- 6.4.8 General Electric Company
- 6.4.9 Omron Corporation
- 6.4.10 SICK AG
- 6.4.11 Panasonic Corporation
- 6.4.12 Pepperl+Fuchs SE
- 6.4.13 Banner Engineering Corporation
- 6.4.14 Pilz GmbH and Co. KG
- 6.4.15 HIMA Paul Hildebrandt GmbH
- 6.4.16 Mitsubishi Electric Corporation
- 6.4.17 Phoenix Contact GmbH and Co. KG
- 6.4.18 Turck GmbH and Co. KG
- 6.4.19 Balluff GmbH
- 6.4.20 IDEC Corporation
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

