PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2123388

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2123388
Assistive Robotics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the assistive robotics market size is expected to grow from USD 10.55 billion in 2025 to USD 12.65 billion in 2026 and is forecast to reach USD 31.29 billion by 2031 at 19.86% CAGR over 2026-2031.
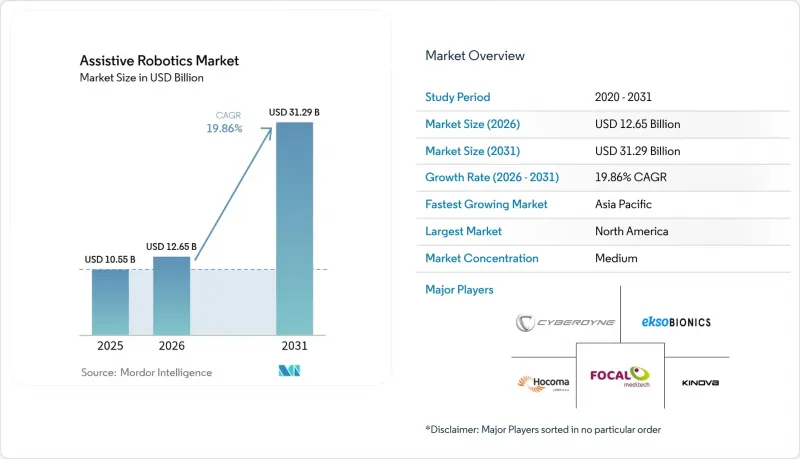
This report is Segmented by Robot Type (Socially Assistive Robots, Mixed Assistive Robots, and More), Mobility (Mobile Robots, and Stationary Robots), Application (Elderly Assistance, Surgery Assistance, Public Relation, Industrial Tasks, and More), End User (Hospitals, Rehabilitation Centers, Homecare Settings, Other End User), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Assistive Robotics Market Trends and Insights
Rising Geriatric Population Accelerating Care Demand
Global aging is widening the caregiver gap, prompting providers to turn to robotic solutions that help alleviate workforce shortages. Japan mandated the installation of robotic lifts in all new nursing facilities starting in 2025, triggering significant orders for transfer-assist platforms. South Korea has allocated USD 120 million to deploy companion robots in 5,000 senior centers by 2027, framing robots as a solution to social isolation. Italy reported that 23% of citizens over 65 live alone, which is accelerating the adoption of social-cognitive robots for medication reminders and emergency alerts. Robots costing USD 30,000 can offset the cost of 0.5 full-time caregivers over five years in high-wage countries, resulting in a sub-three-year payback and validating their economic viability.
Growing Adoption of Robot-Assisted Surgery Procedures
Hospitals in the United States performed more than 1.5 million robotic surgeries in 2024, a 22% increase year-over-year, driven by new reimbursement codes that now cover partial nephrectomy and lobectomy procedures. Stryker's Mako orthopedic platform reached 1,500 installed units by late 2024, with revision surgeries decreasing by 30% compared to manual techniques. Europe's Medical Device Regulation streamlined software update approvals, enabling AI planning tools that reduce operative time by 18 minutes per procedure. The resulting productivity boosts support hospital capital budgets and encourage community facilities to join the adoption curve.
High Capital and Maintenance Costs for Healthcare Providers
Robotic surgery systems cost USD 1.5-3.0 million upfront and require annual service contracts averaging USD 150,000, which restricts their adoption among community hospitals with low case volumes. Exoskeletons priced at USD 80,000-120,000 face similar hurdles outside large academic centers. Exclusive maintenance agreements exacerbate the total cost of ownership, and pay-per-procedure leases often shift risk back onto providers. These financial barriers remain acute in emerging markets where capital budgets are limited.
Other drivers and restraints analyzed in the detailed report include:
- Integration of AI with Assistive Robots Enhancing Autonomy
- Surge in Home-Based Rehabilitation and Tele-Rehabilitation Models
- Limited Clinical Evidence for Long-Term Outcomes
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Mixed platforms are projected to expand at a 21.65% CAGR, outpacing physically assistive incumbents as healthcare systems seek single investments that tackle mobility and social-cognitive needs. Physically assistive solutions held 59.28% of 2025 revenue, but growth is moderating as saturation builds in core lifting and transfer applications. Socially assistive robots remain the smallest slice, yet increased demand for cognitive engagement in memory care is driving orders for conversational units. Panasonic's Hospi now bundles a greeting interface that reduced nurse call-button use by 18% in trials.
Providers appreciate the modularity of mixed robots, which can add or remove arms, screens, or conversational software to fit patient requirements, extending lifecycles and smoothing return on investment. Regulators are clarifying the paths for combination devices, simplifying approvals that previously required dual submissions. This framework is expected to shorten commercialization cycles and fuel broader adoption of hybrid designs.
Mobile robots commanded 57.05% of the revenue in 2025 and are projected to track a 21.05% CAGR, as simultaneous localization and mapping algorithms enable autonomous navigation in cluttered homes. Stationary robots remain critical in operating rooms that need sub-millimeter accuracy, yet their fixed nature limits cross-departmental utility. Hospitals deploy mobile units for logistics, with autonomous carts now handling 30% of internal deliveries at many U.S. medical centers.
The Asia Pacific leads the mobile shift, where urban homes' tight footprints demand adaptable systems, whereas North America retains a larger stationary base, thanks to spacious residences that can accommodate fixed rehabilitation setups. Supply constraints in precision sensors could hinder mobile deployments, but manufacturers are redesigning boards to accommodate multiple sensor brands, thereby protecting shipment schedules.
Complete Report Scope:
- By Robot Type
- Physically Assistive Robots
- Socially Assistive Robots
- Mixed Assistive Robots
- By Mobility
- Mobile Robots
- Stationary Robots
- By Application
- Elderly Assistance
- Handicap Assistance
- Surgery Assistance
- Companionship
- Public Relation
- Industrial Tasks
- Defense and Search and Rescue
- By End User
- Hospitals
- Rehabilitation Centers
- Homecare Settings
- Other End User
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- United Kingdom
- Germany
- France
- Italy
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- Middle East
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America remains the largest regional buyer, accounting for USD 4.18 billion of the assistive robotics market size in 2025, and benefiting from cohesive reimbursement frameworks, robust venture funding, and a dense cluster of surgical robot manufacturers. The United States anchors demand as Medicare opens coverage to new orthopedic indications, and the Veterans Health Administration deploys exoskeletons for mobility-impaired veterans. Canada's provincial pilots signal early momentum, though broad coverage decisions remain pending.
Europe contributed approximately USD 2.16 billion in 2025 sales, led by installations in Germany and the United Kingdom. Germany's statutory insurance coverage for robotic gait therapy spurred a 35% spike in Lokomat orders, while French caps on annual reimbursement restrain device classes eligible for coverage. Southern and Eastern European markets are price-sensitive, with Italy and Spain emphasizing lower-cost manual therapy despite favorable clinical data.
The Asia Pacific region booked USD 3.58 billion in 2025 revenue and is projected to surpass North America by 2028. Japan's Ministry of Health, Labour and Welfare is funding offsets for upfront costs of nursing-home robots, and South Korea's robotics innovation fund is investing USD 200 million in early-stage firms. China's policy push for one million service robots by 2027 has driven a 48% rise in healthcare installations, with domestic brands capturing a significant share of the hospital market through aggressive pricing. Australia and New Zealand continue to adopt homecare robots under disability and accident schemes.
The Middle East and Africa generated USD 0.27 billion in 2025, with the United Arab Emirates leveraging partnerships to establish itself as a regional hub for robotic rehabilitation.
South America posted USD 0.36 billion, underpinned by Brazil's private health insurance segment investing in surgical robotics to attract medical tourists. Despite smaller baselines, both regions could accelerate as telemedicine infrastructure reduces barriers to support services.
- Kinova Inc.
- Ekso Bionics Holdings Inc.
- Cyberdyne Inc.
- Focal Meditech BV
- ReWalk Robotics Ltd.
- Hocoma AG
- Fourier Intelligence Co. Ltd.
- F&P Robotics AG
- Axosuits SRL
- Hyundai Motor Company
- Intuitive Surgical Inc.
- SoftBank Robotics Corp.
- Panasonic Holdings Corporation
- Ubtech Robotics Inc.
- Barrett Technology LLC
- Stryker Corporation
- Blue Frog Robotics SAS
- DreamFace Technologies Pte. Ltd.
- Double Robotics Inc.
- CT Asia Robotics Co. Ltd.
- Hanson Robotics Limited
- Motorika Medical Ltd.
- Rex Bionics Ltd.
- Bionik Laboratories Corp.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Geriatric Population Accelerating Care Demand
- 4.2.2 Growing Adoption of Robot-Assisted Surgery Procedures
- 4.2.3 Integration of AI with Assistive Robots Enhancing Autonomy
- 4.2.4 Surge in Home-Based Rehabilitation and Tele-Rehabilitation Models
- 4.2.5 Emergence of Soft Robotics Improving Safety and Wearability
- 4.2.6 Government Reimbursement for Exoskeletons in Select Markets
- 4.3 Market Restraints
- 4.3.1 High Capital and Maintenance Costs for Healthcare Providers
- 4.3.2 Limited Clinical Evidence for Long-Term Outcomes
- 4.3.3 Fragmented Regulatory Frameworks Slowing Approvals
- 4.3.4 Supply Chain Volatility in Critical Sensors and Actuators
- 4.4 Value-Chain Analysis
- 4.5 Impact of Macroeconomic Factors on the Market
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Buyers
- 4.8.3 Bargaining Power of Suppliers
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Robot Type
- 5.1.1 Physically Assistive Robots
- 5.1.2 Socially Assistive Robots
- 5.1.3 Mixed Assistive Robots
- 5.2 By Mobility
- 5.2.1 Mobile Robots
- 5.2.2 Stationary Robots
- 5.3 By Application
- 5.3.1 Elderly Assistance
- 5.3.2 Handicap Assistance
- 5.3.3 Surgery Assistance
- 5.3.4 Companionship
- 5.3.5 Public Relation
- 5.3.6 Industrial Tasks
- 5.3.7 Defense and Search and Rescue
- 5.4 By End User
- 5.4.1 Hospitals
- 5.4.2 Rehabilitation Centers
- 5.4.3 Homecare Settings
- 5.4.4 Other End User
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 United Kingdom
- 5.5.2.2 Germany
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 South Korea
- 5.5.3.5 Rest of Asia
- 5.5.4 Middle East and Africa
- 5.5.4.1 Middle East
- 5.5.4.1.1 Saudi Arabia
- 5.5.4.1.2 United Arab Emirates
- 5.5.4.1.3 Rest of Middle East
- 5.5.4.2 Africa
- 5.5.4.2.1 South Africa
- 5.5.4.2.2 Egypt
- 5.5.4.2.3 Rest of Africa
- 5.5.4.1 Middle East
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Kinova Inc.
- 6.4.2 Ekso Bionics Holdings Inc.
- 6.4.3 Cyberdyne Inc.
- 6.4.4 Focal Meditech BV
- 6.4.5 ReWalk Robotics Ltd.
- 6.4.6 Hocoma AG
- 6.4.7 Fourier Intelligence Co. Ltd.
- 6.4.8 F&P Robotics AG
- 6.4.9 Axosuits SRL
- 6.4.10 Hyundai Motor Company
- 6.4.11 Intuitive Surgical Inc.
- 6.4.12 SoftBank Robotics Corp.
- 6.4.13 Panasonic Holdings Corporation
- 6.4.14 Ubtech Robotics Inc.
- 6.4.15 Barrett Technology LLC
- 6.4.16 Stryker Corporation
- 6.4.17 Blue Frog Robotics SAS
- 6.4.18 DreamFace Technologies Pte. Ltd.
- 6.4.19 Double Robotics Inc.
- 6.4.20 CT Asia Robotics Co. Ltd.
- 6.4.21 Hanson Robotics Limited
- 6.4.22 Motorika Medical Ltd.
- 6.4.23 Rex Bionics Ltd.
- 6.4.24 Bionik Laboratories Corp.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

