PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2123466

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2123466
Enterprise Key Management (EKM) - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the enterprise key management market size is expected to grow from USD 2.84 billion in 2025 to USD 3.46 billion in 2026 and is forecast to reach USD 9.26 billion by 2031 at 21.76% CAGR over 2026-2031.
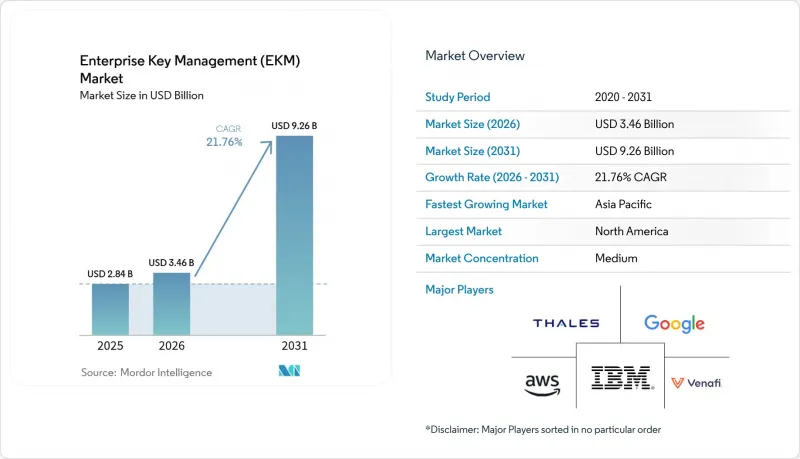
This report is Segmented by Deployment Type (Cloud, and On-Premises), Size of Enterprise (Small- and Medium-Sized Enterprises, and Large Enterprises), Application (Disk Encryption, File and Folder Encryption, and More), End-User Vertical (BFSI, Healthcare, Government and Defense, IT and Telecom, Retail, Other End-User Verticals), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Enterprise Key Management (EKM) Market Trends and Insights
Growing Regulatory Mandates for Data Encryption Across Industries
Global regulators now frame encryption as a baseline control, not a discretionary enhancement. In 2024 the European Data Protection Board issued USD 1.6 billion in fines, and 43% cited inadequate encryption controls. Parallel pressure comes from HIPAA cloud guidance updates and overlapping financial directives such as PCI-DSS and SOX that demand demonstrable key segregation. Multinational corporations must therefore orchestrate homogeneous key governance across diverging regional statutes, propelling demand for platforms capable of mapping a single control stack to multiple audit frameworks. Smaller suppliers are swept in as prime contractors embed encryption clauses into procurement contracts, broadening the total purchasing cohort and reinforcing market momentum.
Exponential Data Growth From Cloud and IoT Workloads
Enterprise data volumes climbed 47% year-over-year in 2024, with unstructured sensor output from IoT and edge deployments driving the steepest curve. Such scale renders appliance-based key stores impractical because millions of devices require low-latency credential rotation even in intermittent-connectivity scenarios. Manufacturing plants that now capture terabytes of telemetry daily and healthcare systems deploying remote patient monitors illustrate the urgency. Cloud-native key services counter this strain through API-driven elasticity, enabling microservices to generate short-lived keys per container instance without manual intervention. As micro-segmentation becomes standard, these services emerge as mandatory underpinnings of modern DevSecOps workflows.
Limited Interoperability Standards Among Key Management Solutions
Although PKCS#11 and KMIP exist, they cover baseline functions unsuited for cloud-native patterns and post-quantum algorithms. Proprietary interfaces lock enterprises into single-vendor stacks, complicating exit strategies and multi-cloud rollouts. Migrating keys between provider HSMs often requires data re-encryption, an operational hurdle that curtails agility and inflates cost of ownership. Interoperability gaps consequently decelerate large-scale deployments and inspire procurement teams to insist on open-standard roadmaps before signing multi-year agreements.
Other drivers and restraints analyzed in the detailed report include:
- Rising Cost of Data Breaches Elevating Board-Level Security Budgets
- Shift Toward Hybrid and Multi-Cloud Architectures Requiring Centralized Key Management
- Shortage of Cybersecurity Professionals Skilled in Cryptographic Key Management
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Cloud deployment generated 62.54% of 2025 revenue, cementing its status as the anchor segment within the enterprise key management market. The segment is forecast to record a 23.62% CAGR through 2031 as buyers favor algorithmic agility and elastic scaling over hardware replacement cycles. Cloud-native services integrate seamlessly into DevSecOps toolchains, shortening the interval between code commit and credential issuance for containerized workloads. Financial institutions exemplify adoption momentum by migrating real-time payment platforms to cloud-based vaults that guarantee sub-millisecond key retrieval. The trend intensifies as central banks approve cloud controls for systemically important institutions, removing a longstanding regulatory barrier.
Hardware-centric deployments remain relevant where data sovereignty or latency demands insist on local key custody, yet even these environments increasingly employ hybrid federations that route certain keys to public cloud HSMs for global failover. Vendors that support both patterns within a unified console gain preference because they allow organizations to preserve legacy investments while modernizing selectively. As a result, the enterprise key management market size attributable to hybrid deployments is expanding, although cloud remains both the largest and fastest growing slice.
Large enterprises retained 57.12% of enterprise key management market share in 2025, reflecting their mature compliance obligations and deep security staffing benches. Yet small and medium enterprises are advancing at a 23.55% CAGR, propelled by supply-chain mandates that cascade encryption requirements downstream. Subscription pricing removes capex barriers, while managed service providers bundle regulatory reporting to offset skills shortages. Healthcare clinics illustrate the pattern by adopting cloud-vault subscriptions that ensure HIPAA alignment without hiring in-house cryptographers.
Regulators indirectly accelerate SME penetration by penalizing prime contractors for subcontractor lapses, which incentivizes tier-1 firms to sponsor onboarding programs for smaller partners. Consequently, a growing share of enterprise key management market size now originates from mid-market accounts that historically relied on rudimentary password vaults. Vendors that offer pre-packaged compliance templates and automated rotation policies capture disproportionate mindshare among this cohort.
Complete Report Scope:
- By Deployment Type
- Cloud
- On-Premises
- By Size of Enterprise
- Small- and Medium-sized Enterprises
- Large Enterprises
- By Application
- Disk Encryption
- File and Folder Encryption
- Database Encryption
- Communication Encryption
- Cloud Encryption
- By End-user Vertical
- BFSI
- Healthcare
- Government and Defense
- IT and Telecom
- Retail
- Other End-user Verticals
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- Saudi Arabia
- United Arab Emirates
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- Middle East
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America held 38.35% of 2025 revenue, anchored by NIST's leadership in post-quantum standards and early budget commitments from U.S. federal agencies that require quantum-safe readiness by 2035. Canadian enterprises piggyback on the U.S. innovation stream while tailoring deployments to PIPEDA privacy constraints, and Mexico's industrial renaissance drives demand for IoT-grade vaults that span factory lines in cross-border supply chains.
Asia Pacific records the briskest trajectory at 22.58% CAGR as sovereign cybersecurity agendas take hold. China's Cryptography Law compels domestic hosting of keys for critical infrastructure, fueling indigenous vendor growth while obligating Western suppliers to establish joint-venture models. India's pending Personal Data Protection Bill and Digital India push prompt BFSI and healthcare rollouts, whereas Japan's Society 5.0 blueprint accelerates factory-floor deployments of edge HSM clusters. South Korea's advanced telecom infrastructure underpins demand for ultra-low-latency key retrieval at 5G edge nodes.
Europe sustains moderate expansion as GDPR fines demonstrate tangible cost for weak encryption and the forthcoming AI Act extends cryptographic duties to automated decision systems. Germany's Mittelstand industrial base focuses on machine identity governance, and France's cloud sovereignty doctrine nurtures local-cloud HSM ecosystems. The United Kingdom, operating under its post-Brexit Data Protection regime, leverages regulatory flexibility to pilot confidential computing constructs in financial services. Collectively, these forces uphold a diversified regional revenue mix and hedge against single-market volatility.
- Amazon Web Services, Inc.
- Venafi, Inc.
- Thales Group
- Google LLC
- International Business Machines Corporation
- Oracle Corporation
- Hewlett Packard Enterprise Company
- Quantum Corporation
- WinMagic Inc.
- Microsoft Corporation
- Dell Technologies Inc.
- HashiCorp, Inc.
- Micro Focus International plc
- Entrust Corporation
- Fortanix Inc.
- ESCRYPT GmbH
- Keyfactor, Inc.
- nCipher Security, LLC
- HyTrust, Inc.
- CipherCloud, Inc.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing Regulatory Mandates for Data Encryption Across Industries
- 4.2.2 Exponential Data Growth From Cloud and IoT Workloads
- 4.2.3 Rising Cost of Data Breaches Elevating Board-Level Security Budgets
- 4.2.4 Shift Toward Hybrid and Multi-Cloud Architectures Requiring Centralized Key Management
- 4.2.5 Emergence of Post-Quantum Cryptography Readiness Programs
- 4.2.6 Integration of Hardware Security Modules With DevSecOps Pipelines
- 4.3 Market Restraints
- 4.3.1 Limited Interoperability Standards Among Key Management Solutions
- 4.3.2 Shortage of Cybersecurity Professionals Skilled in Cryptographic Key Management
- 4.3.3 High Initial Integration Complexity With Legacy Systems
- 4.3.4 Rising Cryptographic Sprawl Leading to Governance Challenges
- 4.4 Industry Value Chain Analysis
- 4.5 Impact of Macroeconomic Factors
- 4.6 Technological Outlook
- 4.7 Regulatory Landscape
- 4.8 Porter's Five Forces Analysis
- 4.8.1 Threat of New Entrants
- 4.8.2 Bargaining Power of Buyers/Consumers
- 4.8.3 Bargaining Power of Suppliers
- 4.8.4 Threat of Substitutes
- 4.8.5 Intensity of Competitive Rivalry
- 4.9 Impact of Macroeconomic Factors
- 4.10 Investment Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Deployment Type
- 5.1.1 Cloud
- 5.1.2 On-Premises
- 5.2 By Size of Enterprise
- 5.2.1 Small- and Medium-sized Enterprises
- 5.2.2 Large Enterprises
- 5.3 By Application
- 5.3.1 Disk Encryption
- 5.3.2 File and Folder Encryption
- 5.3.3 Database Encryption
- 5.3.4 Communication Encryption
- 5.3.5 Cloud Encryption
- 5.4 By End-user Vertical
- 5.4.1 BFSI
- 5.4.2 Healthcare
- 5.4.3 Government and Defense
- 5.4.4 IT and Telecom
- 5.4.5 Retail
- 5.4.6 Other End-user Verticals
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Russia
- 5.5.2.5 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 South Korea
- 5.5.3.5 Australia
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 Middle East
- 5.5.4.1.1 Saudi Arabia
- 5.5.4.1.2 United Arab Emirates
- 5.5.4.1.3 Rest of Middle East
- 5.5.4.2 Africa
- 5.5.4.2.1 South Africa
- 5.5.4.2.2 Egypt
- 5.5.4.2.3 Rest of Africa
- 5.5.4.1 Middle East
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Amazon Web Services, Inc.
- 6.4.2 Venafi, Inc.
- 6.4.3 Thales Group
- 6.4.4 Google LLC
- 6.4.5 International Business Machines Corporation
- 6.4.6 Oracle Corporation
- 6.4.7 Hewlett Packard Enterprise Company
- 6.4.8 Quantum Corporation
- 6.4.9 WinMagic Inc.
- 6.4.10 Microsoft Corporation
- 6.4.11 Dell Technologies Inc.
- 6.4.12 HashiCorp, Inc.
- 6.4.13 Micro Focus International plc
- 6.4.14 Entrust Corporation
- 6.4.15 Fortanix Inc.
- 6.4.16 ESCRYPT GmbH
- 6.4.17 Keyfactor, Inc.
- 6.4.18 nCipher Security, LLC
- 6.4.19 HyTrust, Inc.
- 6.4.20 CipherCloud, Inc.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK

