PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2123590

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2123590
Ureteroscopes - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the ureteroscope market size was valued at USD 1.34 billion in 2025 and estimated to grow from USD 1.42 billion in 2026 to reach USD 1.87 billion by 2031, at a CAGR of 5.75% during the forecast period (2026-2031).
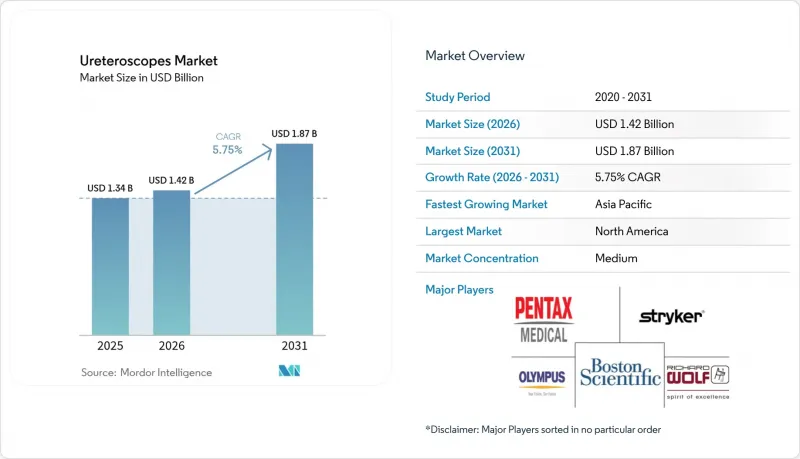
This report is Segmented by Product (Flexible Ureteroscopes and Semi-Rigid Ureteroscopes), Usability (Single-Use/Disposable Ureteroscopes and Reusable Ureteroscopes), Application (Urolithiasis, and More), End User (Hospitals, and More), Geography (North America, Europe, Asia-Pacific, The Middle East and Africa, and South America). The Market Forecasts are Provided in Terms of Value (USD).
Global Ureteroscopes Market Trends and Insights
Rising Global Burden of Urolithiasis & Related Urological Disorders
Kidney-stone incidence hit 106 million cases in 2021 and continues to climb, providing a constant pipeline of candidates for endoscopic stone removal. The gender gap narrows each year; U.S. prevalence among women rose from 6.5% in 2007-2008 to 9.1% in 2017-2020, prompting vendors to refine ergonomics that suit broader anatomies. Regional dynamics vary: Eastern Europe and Central Asia register rising case loads, whereas several East-Asian nations report modest declines, steering sales targets accordingly. Pediatric stone disease, exceeding 3 million annual cases, fuels demand for ultra-miniature shafts that limit ureteral trauma, underpinning long-term growth in the ureteroscope market.
Shift Toward Minimally Invasive Stone-Management Procedures
European Association of Urology guidelines now recommend ureteroscopy ahead of shock-wave therapy for stones under 20 mm, citing stone-free rates between 81%-94%. Same-day discharge cuts facility costs and boosts ASC throughput, while machine-learning algorithms streamline case selection, reducing intra-operative surprises. Combined, these factors enlarge procedural volume, reinforcing expansion of the ureteroscope market.
High Acquisition & Maintenance Cost of Digital Ureteroscopes
A modern digital flexible scope often exceeds USD 20,000 and carries USD 6,000-8,000 in annual service, deterring cash-strapped hospitals. Although disposables bypass repair bills, their per-procedure expense can outstrip local tariffs in emerging economies, slowing uptake and tempering ureteroscope market expansion.
Other drivers and restraints analyzed in the detailed report include:
- Advancements in Digital Flexible & Single-Use Ureteroscope Technology
- Increasing Healthcare Spending & Reimbursement Support for Endourology
- Environmental & Waste-Management Concerns over Disposable Scopes
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Flexible designs held 57.68% of the ureteroscope market in 2025, buoyed by pixel-dense sensors that boost calyceal visualization and ultra-slim 7.5 Fr shafts that ease access without prior dilation. A multicenter study published in May 2025 comparing a 6.3 Fr and 7.5 Fr disposable scope logged stone-free rates of 95% and 92.9%, respectively, and shaved operative time by 4.5 minutes with the smaller device. Semi-rigid systems, prized for durability, grow at 8.89% CAGR because budget-sensitive hospitals regard them as a low-risk entry point, subtly lifting overall ureteroscope market size.
Manufacturers now differentiate through software rather than optics alone. Boston Scientific's pressure-monitoring layer and Olympus's EDOF imaging illustrate value-add pathways that influence tender outcomes. Meta-audits show a generational decline in shaft diameter correlating with fewer ureteral dilations and shorter hospital stays, fostering healthy replacement timelines across the ureteroscope market.
Reusable scopes retain 70.85% share because high-volume centers amortize capital quickly and value established reprocessing protocols. Yet single-use devices expand at a 9.78% CAGR, propelled by data linking disposables to lower post-operative infection rates and zero repair downtime. Portable form factors allow ASCs lacking autoclaves to perform advanced lithotripsy, widening ureteroscope market size in decentralized corridors.
Cost divides opinion: 59.11% of urologists cite price as the prime barrier, but total-cost-of-ownership studies show parity once repair, sterilization labor, and scope loss are tallied. Optical parity debates have subsided; LithoVue Elite's 270° deflection and full-HD sensor now match many reusable benchmarks, smoothing adoption curves.
Complete Report Scope:
- By Product
- Flexible Ureteroscopes
- Digital Flexible Ureteroscopes
- Fiber-optic Flexible Ureteroscopes
- Semi-Rigid Ureteroscopes
- Flexible Ureteroscopes
- By Usability
- Single-Use / Disposable Ureteroscopes
- Reusable Ureteroscopes
- By Application
- Urolithiasis
- Kidney Cancer
- Urinary Stricture
- Other Applications
- By End User
- Hospitals
- Ambulatory Surgical Centers
- Other End Users
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America retained a 37.75% share of the ureteroscope market in 2025, fueled by 9.25% kidney-stone prevalence among U.S. adults and broad coverage for digital scopes. The 2025 outpatient payment bump bolsters ROI, encouraging both academic hospitals and ASCs to refresh fleets. Realtime pressure-monitoring models such as LithoVue Elite help manage complex cases, cementing premium-product demand.
Europe ranks second. Single-use uptake is brisk in the United Kingdom and Germany; conversely, Scandinavian buyers weigh environmental metrics, tempering disposable growth. Southern and Eastern Europe unlock latent demand via modernization funds, broadening ureteroscope market presence across the continent.
Asia-Pacific is the fastest-growing region at a 6.85% CAGR through 2031. China's centralized value-based procurement compresses pricing yet drives bulk orders; Japan and South Korea adopt ultra-slim digital scopes early, while India's private-hospital boom fuels volume growth. Divergent price tiers oblige suppliers to tailor portfolios, enlarging ureteroscope market size across both premium and cost-sensitive segments.
- Olympus
- Boston Scientific
- Stryker
- Karl Storz
- Richard Wolf
- PENTAX Medical (Hoya Corp.)
- Dornier MedTech
- EMS Electro Medical Systems S.A.
- Cook Group
- Vimex
- Elmed Medical Industry & Trade Inc.
- Opcom Inc.
- AED.MD, Inc.
- Prosurg
- Coloplast
- Pusen Medical
- OTU Medical
- Zhuhai Kangji Medical
- Urotech GmbH
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Global Burden of Urolithiasis & Related Urological Disorders
- 4.2.2 Shift Toward Minimally Invasive Stone-Management Procedures
- 4.2.3 Advancements in Digital Flexible & Single-Use Ureteroscope Technology
- 4.2.4 Increasing Healthcare Spending & Reimbursement Support for Endourology
- 4.2.5 Growth of Ambulatory Surgical Centers Performing Ureteroscopy
- 4.2.6 Integration of High-Power Laser Lithotripsy & Imaging Enhancements
- 4.3 Market Restraints
- 4.3.1 High Acquisition & Maintenance Cost of Digital Ureteroscopes
- 4.3.2 Limited Availability of Trained Endourologists in Developing Regions
- 4.3.3 Stringent Device Sterilization & Regulatory Compliance Requirements
- 4.3.4 Environmental & Waste-Management Concerns over Disposable Scopes
- 4.4 Regulatory Outlook
- 4.5 Porter's Five Forces Analysis
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Bargaining Power of Suppliers
- 4.5.4 Threat of Substitutes
- 4.5.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Product
- 5.1.1 Flexible Ureteroscopes
- 5.1.1.1 Digital Flexible Ureteroscopes
- 5.1.1.2 Fiber-optic Flexible Ureteroscopes
- 5.1.2 Semi-Rigid Ureteroscopes
- 5.1.1 Flexible Ureteroscopes
- 5.2 By Usability
- 5.2.1 Single-Use / Disposable Ureteroscopes
- 5.2.2 Reusable Ureteroscopes
- 5.3 By Application
- 5.3.1 Urolithiasis
- 5.3.2 Kidney Cancer
- 5.3.3 Urinary Stricture
- 5.3.4 Other Applications
- 5.4 By End User
- 5.4.1 Hospitals
- 5.4.2 Ambulatory Surgical Centers
- 5.4.3 Other End Users
- 5.5 Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East & Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East & Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Business Segments, Financials, Headcount, Key Information, Market Rank, Market Share, Products and Services, and analysis of Recent Developments)
- 6.3.1 Olympus Corporation
- 6.3.2 Boston Scientific Corporation
- 6.3.3 Stryker Corporation
- 6.3.4 Karl Storz SE & Co. KG
- 6.3.5 Richard Wolf GmbH
- 6.3.6 PENTAX Medical (Hoya Corp.)
- 6.3.7 Dornier MedTech
- 6.3.8 EMS Electro Medical Systems S.A.
- 6.3.9 Cook Medical LLC
- 6.3.10 Vimex Sp. z o.o.
- 6.3.11 Elmed Medical Industry & Trade Inc.
- 6.3.12 Opcom Inc.
- 6.3.13 AED.MD, Inc.
- 6.3.14 Prosurg Inc.
- 6.3.15 Coloplast A/S
- 6.3.16 Pusen Medical
- 6.3.17 OTU Medical
- 6.3.18 Zhuhai Kangji Medical
- 6.3.19 Urotech GmbH
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment

