PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2123610

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2123610
Automotive Battery Management Systems - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the automotive battery management system market size in 2026 is estimated at USD 18.66 billion, growing from 2025 value of USD 15.21 billion with 2031 projections showing USD 51.85 billion, growing at 22.68% CAGR over 2026-2031.
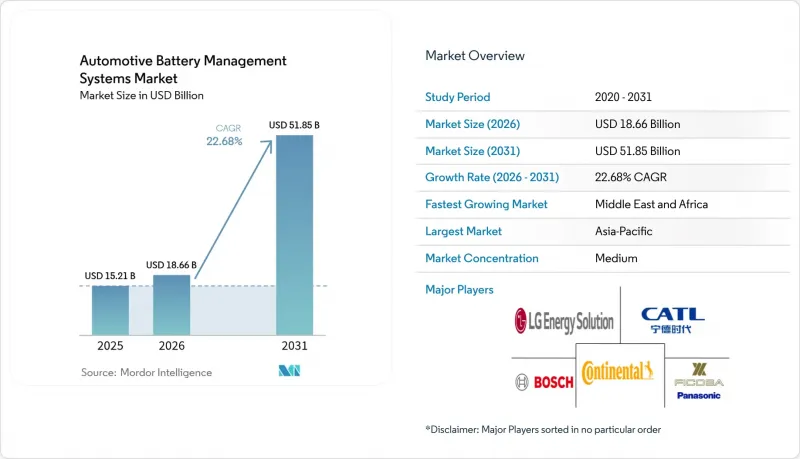
This report is Segmented by Component (Battery IC, Battery Sensors, and More), Topology (Centralized, Modular, and More), Propulsion Type (Hybrid Electric Vehicle (HEV), Battery Electric Vehicle (BEV), and More), Vehicle Type (Passenger Cars, Light Commercial Vehicles, and More), and Geography (North America, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Automotive Battery Management Systems Market Trends and Insights
EV sales mandates widening globally
Binding ZEV policies in regions such as the EU and California raise the baseline for durability, range retention, and transparency of battery health. Euro 7 rules will be effective in 2026, and California's Advanced Clean Cars II demands 80% range retention for 150,000 miles, compelling BMS suppliers to incorporate more refined state-of-health analytics and degradation modeling. Harmonizing rules incentivize global platforms to adopt one compliance-ready architecture, elevating the automotive battery management system market as OEMs avoid region-specific designs. Suppliers that already embed adaptive algorithms gain a head start, whereas legacy providers face added validation cycles and cost.
Falling cost of battery packs
Rapid declines in lithium-ion battery-pack prices are reshaping cost structures. Mainstream LFP packs averaged USD 75 per kWh in 2024, and pilot sodium-ion runs have demonstrated costs as low as USD 10 per kWh. As cells get cheaper, OEMs can allocate larger portions of the battery budget to smarter BMS functions, such as predictive analytics and wireless connectivity, rather than focusing solely on hardware cost reduction. This shift toward higher value content per pack reinforces demand for advanced battery management solutions across the automotive battery management system market.
Thermal-runaway recalls raising warranty reserves
High-profile fire events have led to sizable recalls, forcing automakers to boost warranty accruals and adopt conservative pack design. Samsung SDI's multi-brand recall and Hyundai Mobis' development of self-extinguishing modules underscore industry urgency. Added cost for insulation, fire suppression, and redundant sensors can slow deployment of experimental BMS functions, tempering near-term growth in the automotive battery management system market.
Other drivers and restraints analyzed in the detailed report include:
- Shift from centralized to modular and wireless topologies
- Soaring demand for LFP chemistry requiring advanced active balancing
- Acute power-semiconductor shortages
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Battery Sensors captured 35.02% of the automotive battery management system market share in 2025, and the segment is forecast to post a 24.12% CAGR through 2031. Wider deployment of multi-physics sensing, covering temperature, pressure, off-gas, and humidity, allows OEMs to move from passive protection toward real-time predictive diagnostics. Adoption accelerates as regulators demand enhanced thermal-runaway detection and as fleet operators seek granular data to optimize duty cycles and warranty coverage. Integrating CO2 and H2 sensors into module-level boards improves early-warning capabilities, helping avoid costly recalls and downtime. As EV packs scale above 800 V, high-resolution shunt and Hall-effect sensors become indispensable for accurate state-of-charge and state-of-health estimation, cementing the segment's long-term expansion path.
Tight cell-level voltage accuracy, now reaching +-2 mV, enables finer charge balancing and extended pack life, making IC precision a decisive purchase criterion. Leading chipmakers have fused measurement, balancing, and communication blocks onto single dies, shrinking board footprints and simplifying automotive qualifications. The residual "Other electronics and materials" bucket, encompassing thermally conductive gap fillers, aerogel sheets, and phase-change composites, continues to broaden as energy density rises, calling for superior heat-spreading and insulation solutions.
In 2025, Modular arrangements accounted for 48.42% of the automotive battery management system market share, reflecting OEM preference for scalable sub-battery modules that can be rearranged without wholesale redesign. Box-level isolation of sensing and actuation delivers fault tolerance suited to commercial fleets and high-utilization ride-hailing vehicles. Incremental hardware blocks also facilitate rapid line-side replacement, lifting vehicle uptime.
Wireless designs are scaling rapidly, showing a 33.82% CAGR across 2026-2031 as antenna miniaturization, secure mesh protocols, and certified RF stacks reach production maturity. Eliminating daisy-chain harnesses cuts pack weight and opens valuable cubic centimeters for active cooling plates or extra cells. Centralized topologies continue in entry-price passenger cars, where minimal components trump expandability, whereas niche distributed architectures meet extreme redundancy mandates in motorsports and aerospace crossover programs, cushioning product diversity inside the automotive battery management system market.
Complete Report Scope:
- By Component
- Battery IC
- Battery Sensors
- Other Electronics and Materials
- By Topology
- Centralized
- Modular
- Distributed
- Wireless
- By Propulsion Type
- Hybrid Electric Vehicle (HEV)
- Plug-in Hybrid Electric Vehicle (PHEV)
- Battery Electric Vehicle (BEV)
- Fuel-Cell Electric Vehicle (FCEV)
- By Vehicle Type
- Passenger Cars
- Light Commercial Vehicles
- Medium and Heavy Commercial Vehicles
- Two and Three-Wheelers
- Off-Highway and Specialty Vehicles
- By Geography
- North America
- United States
- Canada
- Rest of North America
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Spain
- Italy
- Russia
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Australia
- Rest of Asia-Pacific
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- Turkey
- Egypt
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia-Pacific retained a commanding 60.77% share of the automotive battery management system market in 2025. China's vertically integrated battery value chain-from upstream refining to final vehicle assembly-compresses cost structures and quickens design iterations. Government purchase incentives, favorable license-plate policies in megacities, and a mature charging ecosystem lift EV penetration and reinforce BMS unit shipments. Supply-chain leverage even extends to Europe and North America, as Chinese cell and module suppliers open factories in Poland, Hungary, and Nevada to secure tariff-free access and shorten logistics lanes.
The Middle East and Africa region, although emerging from a low base, is the fastest-growing region with a 26.9% CAGR through 2031. Dubai, Riyadh, and Cairo are rolling out e-bus corridors and last-mile delivery electrification targets that demand heat-tolerant BMS designs. Public-private alliances channel investment into grid-tied battery storage, creating adjacent sales for repurposed vehicle packs and second-life BMS software.
North America gains momentum as the Inflation Reduction Act galvanizes domestic cell and module manufacturing. Investments by BMW, Toyota, and Hyundai in the Carolinas, Georgia, and Ontario shrink reliance on Asian imports and underpin local sourcing of BMS boards. Europe remains a regulatory trailblazer, with the upcoming battery passport pushing traceability features that increase system complexity and software content. Such requirements elevate per-vehicle revenue and differentiate suppliers ready with secure cloud pipelines, sustaining a healthy overall outlook for the automotive battery management system market.
- LG Energy Solution
- CATL
- Panasonic (Ficosa)
- Robert Bosch GmbH
- Continental AG
- Texas Instruments
- Analog Devices
- Infineon Technologies
- NXP Semiconductors
- Renesas Electronics
- Hitachi Astemo
- Mitsubishi Electric
- Denso Corporation
- Preh GmbH
- Eaton Mobility (Eatron)
- Lithium Balance
- Sensata Technologies
- Eberspacher Vecture
- Rimac Technology
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 EV sales mandates widening globally
- 4.2.2 Falling cost of battery packs
- 4.2.3 Shift from centralized to modular and wireless topologies
- 4.2.4 Soaring demand for LFP chemistry requiring advanced active balancing
- 4.2.5 ISO 21434-driven "cyber-secure BMS" demand
- 4.2.6 OEM move to in-house BMS ASIC design to cut IP royalty cost
- 4.3 Market Restraints
- 4.3.1 Thermal-runaway recalls raising warranty reserves
- 4.3.2 Acute power-semiconductor shortages
- 4.3.3 Post-2027 EU "battery-passport" traceability overheads
- 4.3.4 AI-based predictive BMS still lacks functional-safety certification
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value in USD)
- 5.1 By Component
- 5.1.1 Battery IC
- 5.1.2 Battery Sensors
- 5.1.3 Other Electronics and Materials
- 5.2 By Topology
- 5.2.1 Centralized
- 5.2.2 Modular
- 5.2.3 Distributed
- 5.2.4 Wireless
- 5.3 By Propulsion Type
- 5.3.1 Hybrid Electric Vehicle (HEV)
- 5.3.2 Plug-in Hybrid Electric Vehicle (PHEV)
- 5.3.3 Battery Electric Vehicle (BEV)
- 5.3.4 Fuel-Cell Electric Vehicle (FCEV)
- 5.4 By Vehicle Type
- 5.4.1 Passenger Cars
- 5.4.2 Light Commercial Vehicles
- 5.4.3 Medium and Heavy Commercial Vehicles
- 5.4.4 Two and Three-Wheelers
- 5.4.5 Off-Highway and Specialty Vehicles
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Rest of North America
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Spain
- 5.5.3.5 Italy
- 5.5.3.6 Russia
- 5.5.3.7 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Australia
- 5.5.4.6 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 United Arab Emirates
- 5.5.5.3 Turkey
- 5.5.5.4 Egypt
- 5.5.5.5 South Africa
- 5.5.5.6 Rest of Middle East and Africa
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, SWOT Analysis, and Recent Developments)
- 6.4.1 LG Energy Solution
- 6.4.2 CATL
- 6.4.3 Panasonic (Ficosa)
- 6.4.4 Robert Bosch GmbH
- 6.4.5 Continental AG
- 6.4.6 Texas Instruments
- 6.4.7 Analog Devices
- 6.4.8 Infineon Technologies
- 6.4.9 NXP Semiconductors
- 6.4.10 Renesas Electronics
- 6.4.11 Hitachi Astemo
- 6.4.12 Mitsubishi Electric
- 6.4.13 Denso Corporation
- 6.4.14 Preh GmbH
- 6.4.15 Eaton Mobility (Eatron)
- 6.4.16 Lithium Balance
- 6.4.17 Sensata Technologies
- 6.4.18 Eberspacher Vecture
- 6.4.19 Rimac Technology
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment

