PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2123796

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2123796
Ultra-Thin Glass - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the ultra-Thin glass market size is projected to be USD 14.18 billion in 2025, USD 15.71 billion in 2026, and reach USD 26.87 billion by 2031, growing at a CAGR of 11.34% from 2026 to 2031.
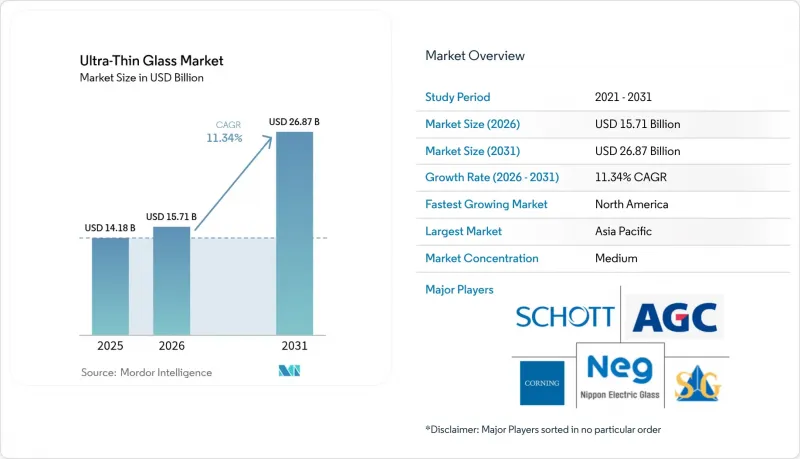
This report is Segmented by Glass Type (Aluminosilicate, Borosilicate, Soda-Lime, and Others), Manufacturing Process (Fusion Draw, Down-Draw, Float, and Roll-To-Roll), Application (Semiconductor Substrate, Touch Panels, Sensors, Automotive, and Others), End-User (Consumer Electronics, Automotive, and More), and Geography (Asia-Pacific, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Ultra-Thin Glass Market Trends and Insights
Growing Demand from Consumer Electronics
In 2025, consumer electronics accounted for a significant portion of the market volume, driven by a robust upgrade cycle towards under-display sensors and edge-to-edge touch modules, fueling double-digit growth. Samsung's Galaxy S25 Ultra, featuring the new Corning Gorilla Armor 2, achieved a notable reduction in surface reflectance. This innovation has led rival OEMs to pursue similar 0.4-millimeter substrates. Following suit, notebook vendors are now adopting ultra-thin glass panels, moving away from the previously used yellow-prone polyimide films. However, the segment's dynamics are evolving, with semiconductor substrates for AI accelerators beginning to capture a larger market share. These advanced packaging applications not only command higher average selling prices but also utilize alkali-free chemistries. This ensures the protection of 112 Gbps SerDes lanes, subtly shifting the revenue focus towards these performance-critical grades.
Rapid Adoption in Foldable Smartphones and Notebooks
Ultra-thin glass economics have been revolutionized by the advent of foldable form factors. Samsung Display is rolling out its 8.6-generation OLED line, set to deliver crease-free panels tailored for Apple's anticipated foldable iPhone debuting in 2026. In a bid to mitigate risks, Chinese panel manufacturers are collaborating on microfloat soda-lime covers. These innovative covers boast impressive endurance and come at a significant cost advantage. Meanwhile, Corning has struck a deal, licensing its Willow roll-to-roll borosilicate, specifically designed for 180-degree notebook hinges. As a result, the industry's spotlight has shifted from merely ensuring hinge durability to mastering yield management. Notably, both float and microfloat lines are nearing the pivotal threshold, a sweet spot that harmonizes price and reliability for the mass-market foldable segment.
High Cost of High-Purity Raw Materials and Precision Processing
Costs rise as electronic-grade silica, with iron content less than 50 ppm, high-purity alumina powder, and platinum-rhodium furnace hardware see price hikes. In 2025, spot silica prices surged, impacting float-line margins, especially for those without hedged contracts. Fusion-draw furnaces, operating at high temperatures, necessitate crucible replacements periodically. Additionally, ion-exchange and laser patterning techniques command a significant premium for aluminosilicate covers compared to soda-lime. European manufacturers grapple with heightened pressures from soaring natural-gas tariffs. While SCHOTT's electric-melting retrofit in Mainz offers some relief, it doesn't fully shield against energy price fluctuations.
Other drivers and restraints analyzed in the detailed report include:
- Advancements in Flexible OLED and Micro-LED Display Lines
- Weight-Reduction Needs in Automotive Glazing and HUDs
- Brittleness and Yield Loss During Large-Area Handling
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Soda-lime ultra-thin products captured 46.09% of 2025 revenue and are forecast to grow at a 12.10% CAGR, underpinned by microfloat lines that hit sub-100 μm thickness at high yield. Aluminosilicate commands foldable-device covers where surface compression above 800 MPa secures 200,000 folds without cracks. Borosilicate and alkali-free glass underpin semiconductor substrates; their sub-3.5 ppm/°C expansion protects high-speed interconnects. Lithium-aluminosilicate remains a niche in HUD optics for its near-zero expansion. ISO 12543-4 durability tests favor borosilicate in automotive laminates, nudging premium OEMs upscale despite higher costs. Chinese float operators are therefore scaling soda-lime to significant production levels for mid-tier electronics, while patent-rich incumbents retain high-margin aluminosilicate and borosilicate tiers.
Float and microfloat technologies delivered 50.68% of 2025 production, and capacity expansions point to a 12.89% CAGR through 2031. The cost of a microfloat line is significantly lower than that of a fusion draw, allowing for a shorter payback period, assuming an optimal utilization rate. However, certain zero-defect applications, such as glass interposers and foldable covers, remain reliant on fusion and down-draw methods. This preference is due to the fact that in these methods, the melt never comes into contact with refractory surfaces. For instance, SCHOTT's down-draw borosilicate achieves a thickness of 20 μm with a roughness of less than 0.5 nm. These metrics are beyond reach in the tin-bath float method, where contact results in asperities of approximately 2 nm. Meanwhile, slit-draw and roll-to-roll processes are catering to the burgeoning flexible electronics market. Notably, Corning Willow is pioneering curved OLED lighting, and Fraunhofer is coating reels for photovoltaic modules. Consequently, the choice of process has evolved into a balancing act between acceptable inclusion density and capital expenditure, leading to a segmentation in the supply base.
Complete Report Scope:
- By Glass Type
- Aluminosilicate (e.g., Gorilla, Dragontrail)
- Borosilicate/Alkali-Free
- Soda-Lime Ultra-Thin
- Others (Lithium-Aluminosilicate, etc.)
- By Manufacturing Process
- Fusion Draw
- Down-Draw/Overflow
- Float and Microfloat
- Slit Draw/Roll-to-Roll
- By Application
- Semiconductor Substrate
- Touch Panel Displays
- Fingerprint Sensors
- Automotive Glazing
- Other Applications (Automotive Displays and Glazing, etc.)
- By End-User Industry
- Consumer Electronics
- Automotive
- Biotechnology
- Other End-User Industries (Energy and Power, etc.)
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle-East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle-East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific delivered 49.59% of 2025 revenue, buoyed by Korean OLED investments and Chinese float retrofits that bolster economies of scale. North America's 11.91% CAGR through 2031, fueled by the CHIPS Act's fabs and mandates for vehicle lightweighting. Major players are driving the demand for advanced packaging, while AGC's Tlaxcala plant in Mexico supplies U.S. OEMs. Europe, holding a notable market share, is influenced by automotive glazing needs and stringent ecodesign regulations. SCHOTT's retrofit of electric melting not only mitigates energy volatility but also reduces CO2 emissions. Meanwhile, OEMs like BMW are adopting ultra-thin roofs to achieve a fleet target by 2027. Although South America and the MEA regions are still emerging, they stand to benefit from solar-energy initiatives, especially with a focus on 100 μm borosilicate covers post-2028.
- AGC Inc.
- Central Glass Co., Ltd.
- Changzhou Almaden Co., Ltd.
- Corning Incorporated
- CSG Holding Co., Ltd.
- Emerge Glass
- Fraunhofer
- Irico Group New Energy Company Limited
- Nippon Electric Glass Co., Ltd.
- Nippon Sheet Glass Co., Ltd.
- Nitto Denko Corporation.
- OFILM
- Samsung
- SCHOTT AG
- Taiwan Glass Ind. Corp.
- Tunghsu Optoelectronic Technology
- Xinyi Glass Holdings Limited.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing demand from consumer electronics
- 4.2.2 Rapid adoption in foldable smartphones and notebooks
- 4.2.3 Advancements in flexible OLED and micro-LED display lines
- 4.2.4 Weight-reduction needs in automotive glazing and HUDs
- 4.2.5 Glass interposers for chiplet packaging
- 4.3 Market Restraints
- 4.3.1 High cost of high-purity raw materials and precision processing
- 4.3.2 Brittleness and yield loss during large-area handling
- 4.3.3 Limited recycling streams for greater than 0.3 mm glass waste
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Bargaining Power of Suppliers
- 4.5.4 Threat of Substitute Products
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Value)
- 5.1 By Glass Type
- 5.1.1 Aluminosilicate (e.g., Gorilla, Dragontrail)
- 5.1.2 Borosilicate/Alkali-Free
- 5.1.3 Soda-Lime Ultra-Thin
- 5.1.4 Others (Lithium-Aluminosilicate, etc.)
- 5.2 By Manufacturing Process
- 5.2.1 Fusion Draw
- 5.2.2 Down-Draw/Overflow
- 5.2.3 Float and Microfloat
- 5.2.4 Slit Draw/Roll-to-Roll
- 5.3 By Application
- 5.3.1 Semiconductor Substrate
- 5.3.2 Touch Panel Displays
- 5.3.3 Fingerprint Sensors
- 5.3.4 Automotive Glazing
- 5.3.5 Other Applications (Automotive Displays and Glazing, etc.)
- 5.4 By End-User Industry
- 5.4.1 Consumer Electronics
- 5.4.2 Automotive
- 5.4.3 Biotechnology
- 5.4.4 Other End-User Industries (Energy and Power, etc.)
- 5.5 By Geography
- 5.5.1 Asia-Pacific
- 5.5.1.1 China
- 5.5.1.2 India
- 5.5.1.3 Japan
- 5.5.1.4 South Korea
- 5.5.1.5 Rest of Asia-Pacific
- 5.5.2 North America
- 5.5.2.1 United States
- 5.5.2.2 Canada
- 5.5.2.3 Mexico
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Rest of Europe
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle-East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 South Africa
- 5.5.5.3 Rest of Middle-East and Africa
- 5.5.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share(%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials, Strategic Info, Products and Services, Recent Developments)
- 6.4.1 AGC Inc.
- 6.4.2 Central Glass Co., Ltd.
- 6.4.3 Changzhou Almaden Co., Ltd.
- 6.4.4 Corning Incorporated
- 6.4.5 CSG Holding Co., Ltd.
- 6.4.6 Emerge Glass
- 6.4.7 Fraunhofer
- 6.4.8 Irico Group New Energy Company Limited
- 6.4.9 Nippon Electric Glass Co., Ltd.
- 6.4.10 Nippon Sheet Glass Co., Ltd.
- 6.4.11 Nitto Denko Corporation.
- 6.4.12 OFILM
- 6.4.13 Samsung
- 6.4.14 SCHOTT AG
- 6.4.15 Taiwan Glass Ind. Corp.
- 6.4.16 Tunghsu Optoelectronic Technology
- 6.4.17 Xinyi Glass Holdings Limited.
7 Market Opportunities and Future Outlook
- 7.1 White-space and Unmet-need Assessment
- 7.2 Development of Advanced Glass for Solar Energy Projects

