PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2124131

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2124131
Digital Holography - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the digital holography market size is expected to grow from USD 4.87 billion in 2025 to USD 5.58 billion in 2026 and is forecast to reach USD 11.03 billion by 2031 at 14.62% CAGR over 2026-2031.
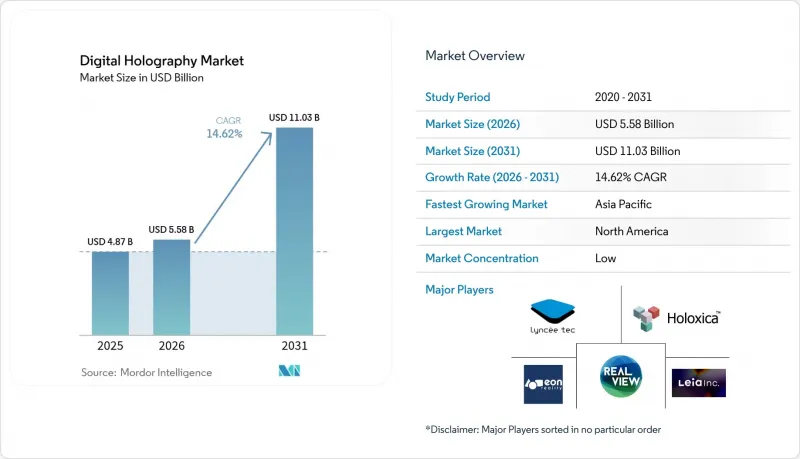
This report is Segmented by Offering (Hardware, and Software), Technique (Off-Axis Holography, In-Line Holography, and More), Application (Digital Holographic Displays, and More) End-User Vertical (Medical and Life Sciences, Aerospace and Defense, Automotive, Commercial and Retail, and More), and Geography (North America, Europe, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Digital Holography Market Trends and Insights
Surge in label-free quantitative phase imaging demand in regenerative medicine trials
Japanese and South Korean regenerative-medicine investigators increasingly relied on digital holographic microscopy to study living cells without stains, supported by Japan's USD 215 million grant program in 2025. The ability of digital holography to capture both amplitude and phase information simultaneously enables researchers to analyze living cells with unprecedented detail, revealing cellular morphology and dynamics that remain invisible to conventional microscopy. Phase Holographic Imaging reported a strategic expansion into the Spanish and Portuguese markets in Q1 2024, specifically targeting regenerative medicine applications. The resulting ability to monitor morphology and cell-cycle kinetics in real time sharpened trial design, shortened discovery timelines and reinforced Asia's first-mover status in precision cell therapy. Spillover demand appeared in U.S. cancer-research centers adopting the same quantitative-phase workflows.
Adoption of holographic HUDs in premium German automotive OEM 2026 line-ups
German automotive manufacturers are at the forefront of integrating holographic head-up displays (HUDs) into their premium vehicle models, with production implementations scheduled for 2026. BMW Group, Mercedes-Benz and Audi confirmed 2026 model-year launches using windshield-embedded holographic HUDs that maintain 5 000-nit brightness and remain visible through polarized sunglasses. Eastman, Ceres Holographics and Covestro supplied Holographic In-Plane Transparent Display (HIPTD) films that anchor the solution. By relocating speed, navigation and ADAS alerts into the driver's line of sight, OEMs targeted higher Euro NCAP scores and reduced distraction-related incidents.
Sparse supply of high-efficiency 4K spatial light modulators from APAC foundries
The digital holography market faces significant supply constraints for high-efficiency 4K spatial light modulators (SLMs), a critical component in holographic display systems. APAC foundries, particularly in Japan and South Korea, are struggling to meet growing demand due to production capacity limitations and competing priorities for semiconductor manufacturing lines. This supply shortage is exacerbated by the specialized nature of SLM production, which requires expertise in both semiconductor fabrication and optical engineering. Recent research has explored alternative approaches, such as digital micromirror devices (DMDs), which offer advantages including higher resolution and faster switching speeds compared to traditional liquid crystal SLMs. Spot prices for phase-only devices spiked 18% in 2025.
Other drivers and restraints analyzed in the detailed report include:
- Standardization of H.266/VVC enabling bandwidth-light holographic telepresence on U.S. 5G networks
- Defense funding for long-range holographic LiDAR ISR payloads in Israel and UAE
- Prohibitive clean-room CAPEX (> USD 80 m) for phase-only SLM fabrication
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Hardware captured 61.35% of digital holography market share in 2025, anchored by lasers, cameras and spatial-light modulators that convert optical interference into raw holograms. Cameras now exceed 100 MP at sub-3 µm pixel pitches, lifting system-level resolution. Meanwhile, software revenue is on course to add USD 1.58 billion through 2031 as iterative-phase retrieval, neural up-scaling and compression modules become indispensable for turnkey deployments. UCLA researchers demonstrated a recurrent-neural-network reconstruction that lifted structural-similarity metrics 40% and shortened compute time fifteen-fold, underscoring software's role in unlocking latent value. Industrial original-equipment buyers have shifted to subscription models that bundle firmware upgrades, cloud render pipelines and on-premises debugging utilities in multi-year service-level agreements. These shifts point toward a future in which vendors package complete stacks, compressing integration timelines and amplifying switching costs-thereby raising the digital holography market size in recurring-revenue terms.
Second-generation application-programming interfaces link hologram generation engines with AR/VR design packages, removing barriers that previously fragmented content pipelines. Medical imaging labs exploit open-source Python plug-ins to automate phase-unwrap workflows, cutting experiment-setup times from hours to minutes. Automotive dashboard suppliers license proprietary calibration algorithms that align laser modulators to curved windshields, simplifying field-service logistics and protecting margin. Collectively, these dynamics confirm that software, though representing the smaller top-line slice today, will deliver disproportionate long-term profitability inside the digital holography industry.
Off-axis holography retained 68.50% of revenue in 2025 owing to robust photolithography-mask inspection and aerospace metrology installations. Users appreciate its single-exposure acquisition and inherent noise rejection, which preserve data integrity on vibrating factory floors. Yet synthetic-aperture and hybrid approaches are projected to climb at a 16.42% CAGR, propelled by multiview registration algorithms that chain sequential captures into one ultra-high-numerical-aperture composite. UCLA, Beihang University and Fraunhofer teams each reported > 57° viewing angles derived from synthetic-aperture assembly, tearing down the field-of-view wall that once limited commercial viability.
In-line holography, a workhorse for label-free microscopy, maintains a niche in cost-sensitive university labs that favor simpler alignments over maximal resolution. Touchable-holography prototypes from the Public University of Navarra added tactile feedback via ultrasonic phased arrays in April 2025, prompting museum and ed-tech pilots. The confluence of decreasing laser-diode pricing, precision-servo advances and AI reconstruction now positions hybrid systems to usurp legacy interferometers in inspection lines, potentially redirecting another 5% share toward synthetic-aperture architectures by 2028. If spatial-light-modulator supply stabilizes, the digital holography market share of these techniques could accelerate faster than forecast.
Complete Report Scope:
- By Offering
- Hardware
- Lasers
- CCD/CMOS Image Sensors
- Spatial Light Modulators
- Beam Splitters and Optics
- Processors and Memory
- Software
- Reconstruction Algorithms
- Visualization/Rendering Engines
- Compression and Transmission Software
- Hardware
- By Technique
- Off-Axis Holography
- In-Line Holography
- Synthetic Aperture and Hybrid Techniques
- Touchable Holography
- By Application
- Digital Holographic Displays
- Digital Holographic Microscopy
- Holographic Telepresence and Communication
- Head-Up Displays (Automotive and Aviation)
- Data Storage and Security Authentication
- Manufacturing and Metrology Inspection
- By End-User Vertical
- Medical and Life Sciences
- Aerospace and Defense
- Automotive
- Commercial and Retail
- Education and Research Institutes
- Industrial Automation
- Media and Entertainment
- Consumer Electronics
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Nordics (Denmark, Sweden, Norway, Finland)
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- India
- Southeast Asia
- Australia
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East
- Gulf Cooperation Council Countries
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Rest of Africa
- North America
Geography Analysis
North America captured 41.70% of global revenue in 2025, driven by Pentagon R&D allocations and Silicon Valley enterprise pilots. U.S. telecom carriers fast-tracked city-center telepresence studios after H.266/VVC proved bandwidth-viable, turning Chicago, Dallas and San Francisco into early hubs. Canada emerged as a HUD-design incubator, leveraging provincial tax credits to lure optical-component start-ups that feed Detroit and Munich supply chains. Venture funding exceeded USD 300 million in 2025 for Montreal-based sensor firms.
Asia-Pacific, already the fastest-growing region with a 15.92% CAGR, benefited from Beijing's 5G-Advanced footprint that streams real-time product holograms to high-street boutiques, advancing the digital holography market size for retail. Japanese life-science complexes adopted high-throughput phase-imaging rigs for regenerative-medicine assays, while South Korean automakers synchronized HOE tooling with HUD electronics to shorten ramp-up cycles. India's e-waste challenge repurposed obsolete LCD backlights into holography-ready light-engines, diverting 500 tons of landfill in 2025.
Europe sustained momentum through Germany's auto-tech partnerships and the UK's National Health Service pilots. Horizon Europe earmarked EUR 95 million for advanced photonics projects in 2025, with phase-only SLM and polymer-film waveguide research receiving first-round grants. Israel and the UAE advanced defense LiDAR adoption, while Turkey initiated smart-city holographic-mapping bids. Latin America trailed due to volumetric-video standard gaps; Brazil's broadcasters postponed 3D studio renovations pending specification clarity. Notwithstanding, Mexican architectural firms used holographic walk-throughs to win offshore contracts, hinting at latent demand growth once standards mature.
- RealView Imaging Ltd.
- Lyncee TEC SA
- Phase Holographic Imaging AB
- EON Reality Inc.
- Geola Digital UAB
- MetroLaser Inc.
- Leia Inc.
- Intelligent Imaging Innovations Inc.
- Light Logics Holography and Optics
- Jasper Display Corporation
- Holoxica Limited
- zSpace Inc.
- EchoPixel Inc.
- Zebra Imaging
- NKT Photonics A/S
- HYPERVSN (Baylan Ltd.)
- Ovizio Imaging Systems NV
- Realfiction ApS
- VNTANA
- Looking Glass Factory Inc.
- SeeReal Technologies GmbH
- Light Field Lab Inc.
- HoloTech Switzerland AG
- Daqri LLC
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surge in label-free quantitative phase imaging demand in regenerative medicine trials across Japan and South Korea
- 4.2.2 Adoption of holographic HUDs in premium German automotive OEM 2026 line-ups
- 4.2.3 Standardization of H.266/VVC enabling bandwidth-light holographic telepresence on United States 5G networks
- 4.2.4 Defense funding for long-range holographic LiDAR ISR payloads in Israel and United Arab Emirates
- 4.2.5 Retail 5G-Advanced roll-out powering edge-rendered volumetric ads in Chinese Tier-1 malls
- 4.2.6 EU-MDR incentives for radiation-free holographic surgical guidance in French university hospitals
- 4.3 Market Restraints
- 4.3.1 Sparse supply of high-efficiency 4K spatial light modulators from Asia-Pacific foundries
- 4.3.2 Prohibitive clean-room CAPEX (Above USD 80 m) for phase-only SLM fabrication
- 4.3.3 Lack of volumetric-video standards among LATAM broadcasters hindering content roll-out
- 4.3.4 Clinician scepticism due to absence of multi-centre RCT evidence for holographic diagnostics
- 4.4 Industry Ecosystem Analysis
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Threat of New Entrants
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Bargaining Power of Suppliers
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUES)
- 5.1 By Offering
- 5.1.1 Hardware
- 5.1.1.1 Lasers
- 5.1.1.2 CCD/CMOS Image Sensors
- 5.1.1.3 Spatial Light Modulators
- 5.1.1.4 Beam Splitters and Optics
- 5.1.1.5 Processors and Memory
- 5.1.2 Software
- 5.1.2.1 Reconstruction Algorithms
- 5.1.2.2 Visualization/Rendering Engines
- 5.1.2.3 Compression and Transmission Software
- 5.1.1 Hardware
- 5.2 By Technique
- 5.2.1 Off-Axis Holography
- 5.2.2 In-Line Holography
- 5.2.3 Synthetic Aperture and Hybrid Techniques
- 5.2.4 Touchable Holography
- 5.3 By Application
- 5.3.1 Digital Holographic Displays
- 5.3.2 Digital Holographic Microscopy
- 5.3.3 Holographic Telepresence and Communication
- 5.3.4 Head-Up Displays (Automotive and Aviation)
- 5.3.5 Data Storage and Security Authentication
- 5.3.6 Manufacturing and Metrology Inspection
- 5.4 By End-User Vertical
- 5.4.1 Medical and Life Sciences
- 5.4.2 Aerospace and Defense
- 5.4.3 Automotive
- 5.4.4 Commercial and Retail
- 5.4.5 Education and Research Institutes
- 5.4.6 Industrial Automation
- 5.4.7 Media and Entertainment
- 5.4.8 Consumer Electronics
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Nordics (Denmark, Sweden, Norway, Finland)
- 5.5.2.7 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 South Korea
- 5.5.3.4 India
- 5.5.3.5 Southeast Asia
- 5.5.3.6 Australia
- 5.5.3.7 Rest of Asia-Pacific
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle East
- 5.5.5.1 Gulf Cooperation Council Countries
- 5.5.5.2 Turkey
- 5.5.5.3 Rest of Middle East
- 5.5.6 Africa
- 5.5.6.1 South Africa
- 5.5.6.2 Nigeria
- 5.5.6.3 Rest of Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 RealView Imaging Ltd.
- 6.4.2 Lyncee TEC SA
- 6.4.3 Phase Holographic Imaging AB
- 6.4.4 EON Reality Inc.
- 6.4.5 Geola Digital UAB
- 6.4.6 MetroLaser Inc.
- 6.4.7 Leia Inc.
- 6.4.8 Intelligent Imaging Innovations Inc.
- 6.4.9 Light Logics Holography and Optics
- 6.4.10 Jasper Display Corporation
- 6.4.11 Holoxica Limited
- 6.4.12 zSpace Inc.
- 6.4.13 EchoPixel Inc.
- 6.4.14 Zebra Imaging
- 6.4.15 NKT Photonics A/S
- 6.4.16 HYPERVSN (Baylan Ltd.)
- 6.4.17 Ovizio Imaging Systems NV
- 6.4.18 Realfiction ApS
- 6.4.19 VNTANA
- 6.4.20 Looking Glass Factory Inc.
- 6.4.21 SeeReal Technologies GmbH
- 6.4.22 Light Field Lab Inc.
- 6.4.23 HoloTech Switzerland AG
- 6.4.24 Daqri LLC
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-Need Assessment

