PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2124196

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2124196
Polymer Coated Fabric - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the polymer coated fabric market size is projected to grow from USD 19.90 billion in 2025 to USD 20.87 billion in 2026, and reach USD 27.03 billion by 2031, growing at a CAGR of 5.31% from 2026 to 2031.
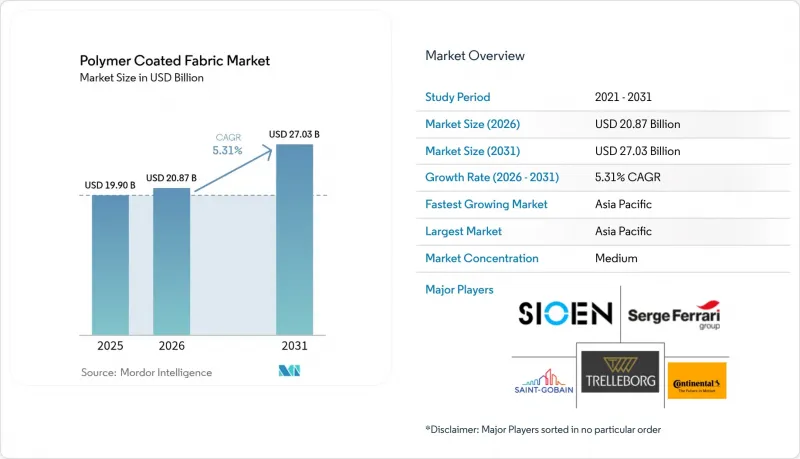
This report is Segmented by Product Type (Polyvinyl Chloride, Polyurethane, Polyethylene, Silicone, and Others), Application (Transportation, Industrial Equipment Covers, Roofing and Awning, Protective Clothing, Furniture, Sports and Leisure, and Others), and Geography (North America, South America, Europe, Asia-Pacific, and Middle East and Africa). Market Forecasts are Provided in Terms of Value (USD).
Global Polymer Coated Fabric Market Trends and Insights
Lightweight and Sustainable Interior Materials Demand
Automotive OEMs are replacing traditional vinyl and leather with polyurethane-coated textiles that lower door-panel and seat-cover weight by up to 15%, a shift aligned with U.S. CAFE targets of 49 miles per gallon by 2026. Water-based polyurethane systems remove N-methyl-2-pyrrolidone, cutting volatile-organic-compound emissions by 95% and enabling compliance with ISO 12219-1 cabin-air standards. European automakers increasingly specify bio-attributed polyols sourced from waste cooking oil or castor beans, achieving 20-30% renewable-carbon content while maintaining tensile strengths above 25 MPa. Furniture manufacturers are adopting analogous chemistries to satisfy California Proposition 65 disclosure rules and the European Union Furniture and Furnishings regulations on flame retardancy. Closed-loop recycling lines that reclaim polyester scrim from end-of-life seat covers are emerging, lowering virgin-fiber use by up to 40% and reinforcing circular-economy goals.
Climate-Resilient Tensile Structures Boom
PTFE-coated glass and PVC-coated polyester membranes now headline designs for stadium roofs, airport halls, and outdoor canopies in cyclone-prone regions because they resist wind loads above 200 km/h without tearing. A Joint Research Centre field study confirmed that PTFE membranes in coastal Qatar retained 98% of initial tensile strength after 15 years, outperforming metallic cladding that corroded in fewer than eight. Self-cleaning titanium-dioxide topcoats slash maintenance costs by 30% through photocatalytic degradation of organic dirt. Saudi Arabia has earmarked USD 2.1 billion for shaded walkways in Riyadh and Jeddah by 2028, embedding fabric structures in national adaptation plans. Similar solutions are gaining traction in sub-Saharan infrastructure projects where relocatable membranes deliver a 50% cost advantage over fixed concrete shelters.
Crude-Derived Polymer Price Volatility
Brent crude averaged USD 70-90 per barrel through 2025, lifting ethylene and propylene feedstock costs that make up 60-70% of PVC pricing. Mid-sized European converters locked into quarterly supply contracts saw margin squeeze when Q2 2025 spot prices jumped 12%, forcing three-week production stoppages until markets normalized. Polyurethane raw-material inputs such as MDI follow similar trends because benzene prices track oil with a three-month lag. Some Asian converters have acquired minority stakes in polyol plants to secure volumes and pricing, while smaller firms resort to toll-coating models that cap profit potential at 8-10% of finished-fabric value. Vertical integration is therefore becoming a critical hedge against raw-material swings.
Other drivers and restraints analyzed in the detailed report include:
- Antimicrobial Healthcare Furnishings Adoption
- Sensor-Embedded Smart Fabrics Integration
- Environmental Scrutiny of PVC and Phthalates
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
PVC accounted for 42.15% of polymer polymer-coated fabrics market revenue in 2025, owing to resin prices that run 30-40% below polyurethane and built-in flame retardancy that satisfies NFPA 701 without extra additives. Water-based polyurethane is capturing share fastest at a 6.12% CAGR to 2031 because automotive and furniture OEMs demand soft-touch surfaces that meet South Coast AQMD Rule 1168 limits on volatile organic compounds. These chemistries also help converters sidestep vapor-recovery investments equal to 15% of plant capital.
Polyethylene coatings cater to chemical-inertness niches such as agricultural silage covers, while silicone systems dominate high-temperature uses like exhaust-insulation blankets because they remain stable above 250 °C. Fluoropolymer dispersions and bio-based polyesters populate the "Others" category, each serving specialty demand for extreme chemical resistance or cradle-to-grave certification. Historical data show the product-type hierarchy grew at roughly 4.8% per year from 2020-2025, but momentum is accelerating as auto production rebounds and public-works spending returns. Stricter European public-procurement rules that grant 30% weighting to ISO 14001 certification continue to nudge customers toward polyurethane solutions with documented recycling pathways.
Complete Report Scope:
- By Product Type
- Polyvinyl Chloride (PVC)
- Polyurethane (PU)
- Polyethylene
- Silicone
- Others
- By Application
- Transportation
- Industrial Equipment Covers
- Roofing and Awning
- Protective Clothing
- Furniture
- Sports and Leisure
- Others
- By Geography
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Rest of Asia-Pacific
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Rest of Europe
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- South Africa
- Rest of Middle East and Africa
- Asia-Pacific
Geography Analysis
Asia-Pacific dominated the polymer coated fabrics market with a 46.42% share in 2025 and is projected to maintain a 5.98% CAGR through 2031. China alone produced 27 million motor vehicles in 2025 and hosts more than 800,000 tons/year of coated-fabric capacity concentrated in Jiangsu and Zhejiang, where feedstock proximity lowers logistics overhead by up to 15% . India's National Infrastructure Pipeline earmarks USD 1.4 trillion through 2030, stimulating domestic demand and export growth to the Middle East and Africa.
North America accounted for a significant market share in 2025. Automotive seating absorbed 180,000 tons of polyurethane coated fabric, and federal infrastructure spending of USD 110 billion through 2026 is spurring uptake in geotextiles and temporary shelters. Europe's market growth is driven by lightweight requirements under the 55% transport-emission-reduction goal in the European Green Deal, pushing OEMs toward polyurethane solutions with certified carbon footprints.
South America plus the Middle East and Africa are witnessing a considerable rise in demand for polymer coated fabrics. Brazil's farm-sector demand for silage covers and the Gulf Cooperation Council's construction pipeline-particularly stadium roofs and transit hubs-are the main growth drivers. Historically, geographic expansion lagged during pandemic disruptions, but normalization of supply chains and resumption of infrastructure projects underpin the 5.31% global forecast growth rate to 2031.
- Continental AG
- Freudenberg Performance Materials Holding GmbH
- Heytex Gruppe
- OMNOVA North America Inc.
- MICHELIN
- Saint-Gobain
- Seaman Corporation
- Serge Ferrari Group
- Sioen Industries NV
- SPRADLING INTERNATIONAL GmbH
- SRF Limited
- Trelleborg AB
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Lightweight and Sustainable Interior Materials Demand
- 4.2.2 Climate-Resilient Tensile Structures Boom
- 4.2.3 Antimicrobial Healthcare Furnishings Adoption
- 4.2.4 Sensor-Embedded Smart Fabrics Integration
- 4.2.5 Flexible PV Back-Sheet Fabrics Investments
- 4.3 Market Restraints
- 4.3.1 Crude-Derived Polymer Price Volatility
- 4.3.2 Environmental Scrutiny of PVC and Phthalates
- 4.3.3 Micro-plastic Release Regulations Tighten
- 4.4 Value Chain Analysis
- 4.5 Porter's Five Forces
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Bargaining Power of Suppliers
- 4.5.4 Threat of Substitutes
- 4.5.5 Degree of Competition
5 Market Size and Growth Forecasts (Value)
- 5.1 By Product Type
- 5.1.1 Polyvinyl Chloride (PVC)
- 5.1.2 Polyurethane (PU)
- 5.1.3 Polyethylene
- 5.1.4 Silicone
- 5.1.5 Others
- 5.2 By Application
- 5.2.1 Transportation
- 5.2.2 Industrial Equipment Covers
- 5.2.3 Roofing and Awning
- 5.2.4 Protective Clothing
- 5.2.5 Furniture
- 5.2.6 Sports and Leisure
- 5.2.7 Others
- 5.3 By Geography
- 5.3.1 Asia-Pacific
- 5.3.1.1 China
- 5.3.1.2 India
- 5.3.1.3 Japan
- 5.3.1.4 South Korea
- 5.3.1.5 Rest of Asia-Pacific
- 5.3.2 North America
- 5.3.2.1 United States
- 5.3.2.2 Canada
- 5.3.2.3 Mexico
- 5.3.3 Europe
- 5.3.3.1 Germany
- 5.3.3.2 United Kingdom
- 5.3.3.3 France
- 5.3.3.4 Italy
- 5.3.3.5 Rest of Europe
- 5.3.4 South America
- 5.3.4.1 Brazil
- 5.3.4.2 Argentina
- 5.3.4.3 Rest of South America
- 5.3.5 Middle East and Africa
- 5.3.5.1 Saudi Arabia
- 5.3.5.2 South Africa
- 5.3.5.3 Rest of Middle East and Africa
- 5.3.1 Asia-Pacific
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share (%)/Ranking Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products and Services, Recent Developments)
- 6.4.1 Continental AG
- 6.4.2 Freudenberg Performance Materials Holding GmbH
- 6.4.3 Heytex Gruppe
- 6.4.4 OMNOVA North America Inc.
- 6.4.5 MICHELIN
- 6.4.6 Saint-Gobain
- 6.4.7 Seaman Corporation
- 6.4.8 Serge Ferrari Group
- 6.4.9 Sioen Industries NV
- 6.4.10 SPRADLING INTERNATIONAL GmbH
- 6.4.11 SRF Limited
- 6.4.12 Trelleborg AB
7 Market Opportunities and Future Outlook
- 7.1 White-Space and Unmet-Need Assessment

