PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2124282

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2124282
Pressure Vessel - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the pressure vessel market size is expected to grow from USD 60.77 billion in 2025 to USD 63.52 billion in 2026 and is forecast to reach USD 79.23 billion by 2031 at 4.52% CAGR over 2026-2031.
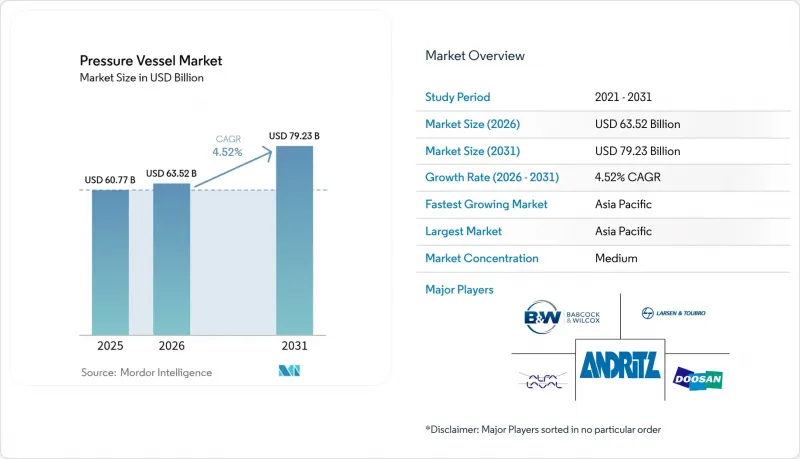
This report is Segmented by Material (Carbon Steel, Composites, Clad and Alloy Steels, and More), Pressure Rating (0 To 10 Bar, Above 100 Bar, and More), Application (Storage Vessels, Process/Reactors, Heat Exchangers, Boilers, and Others), End-User Industry (Power Generation, Oil and Gas Mid/Downstream, Pharmaceuticals and Biotech, and More), and Geography (North America, Europe, Asia-Pacific, and More).
Global Pressure Vessel Market Trends and Insights
Energy Infrastructure Upgrades in Emerging Economies
Asia-Pacific governments accelerate refinery, petrochemical, and power-generation projects that require large quantities of certified vessels; Dongfang Electric's supply of domestic reactor pressure vessels for Taishan 2 underscores the shift from imports to local fabrication. Industrial parks across India and Southeast Asia specify standardised vessels for combined-cycle plants and LNG terminals, redistributing orders away from traditional Western suppliers. Funding from national development banks shortens project cycles and boosts volume guarantees for regional fabricators. Lower labour costs complement burgeoning technical skills, enabling price-competitive products that comply with ASME and PED codes. This geographic capacity migration adds manufacturing resilience and cost pressure within the pressure vessel market.
Rising Global LNG Trade and Associated Cryogenic Storage Demand
Canada's first Pacific-coast export cargo to Asia shows North American LNG flows demand hundreds of double-walled stainless-steel vessels that maintain -162 °C temperatures under variable loading. The USD 40 billion LNG Canada plant illustrates the scale, with tanks engineered to manage boil-off gas and cyclic thermal stresses. Vessel complexity grows when integrating onto LNG-fuelled ships and heavy-duty trucks, where weight reduction and vacuum insulation become mission-critical. These technical barriers favour incumbents with proven cryogenic know-how, consolidating market share among specialised suppliers. Long-term offtake contracts reduce volume risk, enabling large backlog visibility for cryogenic vessel manufacturers.
Volatile Steel Prices Squeezing OEM Margins
European apparent steel consumption shrank for the fourth year in 2024, and new US import tariffs have intensified cost swings. Pressure vessel makers negotiate fixed-price delivery contracts months before plate mills settle quarterly surcharges, creating negative margins when spot prices spike. Some producers accelerate substitution toward composites or duplex stainless grades to mitigate exposure, but code approvals limit rapid changeovers. Working-capital burdens also rise because mills demand quicker payment during tight supply cycles. Thus, price volatility directly constrains profitability in the pressure vessel market.
Other drivers and restraints analyzed in the detailed report include:
- Nuclear New-Build Resurgence in Asia
- Stricter Workplace Safety Regulations (API 510, PED, ASME)
- Lengthy Certification & Compliance Cycles
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Carbon steel retained 47.35% share of the pressure vessel market in 2025, thanks to low cost and broad code coverage. However, the composites' pressure vessel market size is projected to rise 7.05% CAGR to 2031 as hydrogen mobility scales production volumes. Stainless steel maintains an evergreen role in food, pharmaceutical, and biotech services, where corrosion resistance justifies its premium price. Clad and alloy steels address high-temperature petrochemical reactors, and aluminium occupies weight-sensitive niches. Composite overwrapped pressure vessels achieve 60% weight reduction at 700 bar service, expanding adoption into transport and stationary storage.
The pressure vessel market responds by retooling filament-winding lines and securing carbon-fibre supply agreements to capture the emerging composite opportunity. Steel fabricators defend their share by adding electropolishing lines and duplex alloys to meet stringent hygiene codes. Material diversification, therefore, intensifies competition, with regulatory approvals acting as both barrier and catalyst. Certifications for composite liners in nuclear service remain elusive, keeping steel dominant in that premium segment but not halting composite encroachment elsewhere.
Low-pressure vessels between 0 and 10 bar held 40.60% of the pressure vessel market share in 2025 across bulk storage and water treatment. The pressure vessel market size for ultra-high-pressure units above 100 bar will rise at a 7.25% CAGR to 2031 because hydrogen tanks and supercritical reactors require extreme ratings. Medium (10-50 bar) and high (50-100 bar) segments provide steady replacements in refining and chemical plants. Hydrogen fuel cell vehicles store at 350-700 bar, so Type 4 tanks become the design default.
Manufacturers targeting this segment invest in autofrettage presses, precision winding, and in-house burst-test rigs to comply with ISO 19881. Cost-per-kilogram of stored hydrogen becomes the competitive metric, driving thinner liners and advanced fibers. Conversely, low-pressure producers focus on modular tank farms and automated rolling lines to preserve margin in commodity markets. This bifurcation underscores how emerging technologies redefine competitive clusters within the pressure vessel market.
Complete Report Scope:
- By Material
- Carbon Steel
- Stainless Steel
- Clad and Alloy Steels
- Composites
- Aluminium and Others
- By Pressure Rating
- 0 to 10 bar (Low)
- 10 to 50 bar (Medium)
- 50 to 100 bar (High)
- Above 100 bar (Ultra-high)
- By Application
- Storage Vessels
- Process/Reactors
- Heat Exchangers
- Boilers
- Others (Custom vessels, Specialty vessels, Expansion vessels)
- By End-User Industry
- Oil and Gas Upstream
- Oil and Gas Mid/Downstream
- Chemical and Petrochemical
- Power Generation
- Food and Beverage
- Pharmaceuticals and Biotech
- Water and Wastewater
- Others
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Russia
- Rest of Europe
- Asia Pacific
- China
- India
- Japan
- South Korea
- ASEAN Countries
- Rest of Asia Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- Saudi Arabia
- United Arab Emirates
- South Africa
- Egypt
- Rest of Middle East and Africa
- North America
Geography Analysis
Asia-Pacific held 44.62% of the pressure vessel market in 2025 and is forecast to expand at a 6.05% CAGR through 2031. China's localisation of nuclear island components and India's refinery build-outs underpin large order books. Japan Steel Works and Mitsubishi Heavy Industries supply reactor forgings globally, reinforcing regional dominance in high-specification segments. South Korea leverages shipbuilding expertise to produce LNG tanks, and ASEAN economies invest in hydrogen refuelling stations that use 700 bar COPVs. These projects embed long-term manufacturing ecosystems across the region. North America represents a mature yet opportunity-rich landscape. The US aims to raise nuclear capacity from 100 GW in 2024 to 300 GW by 2050, implying that sizable reactor-grade vessel demand and export terminals along the Gulf Coast and British Columbia require cryogenic storage, sustaining specialised vessel orders. Replacement cycles in refineries and stricter OSHA rules create recurring domestic demand, although fabricators face competition from Asian imports on commodity tanks.
Europe prioritises decarbonisation, channelling funds into hydrogen infrastructure and small modular reactors. PED harmonisation simplifies cross-border sales but raises compliance thresholds. Steel price volatility and energy costs challenge margins, prompting consolidation among medium-sized fabricators. Scandinavia and Germany pilot Power-to-X plants, adding ultra-high-pressure vessels to local wish lists. Overall, European customers pay premiums for traceable supply chains and carbon-footprint disclosures.
Emerging regions such as South America, the Middle East, and Africa show divergent growth arcs. Brazil's pre-salt fields extend downstream infrastructure, Mexico retrofits refineries, and Argentina eyes shale monetisation. Gulf petrochemical clusters in Saudi Arabia and the UAE commission mega-scale reactors and heat exchangers. African nations pursue modular fertiliser and gasification units, leaning on foreign EPC contractors that bundle imported vessels. Collectively, these areas inject volume upside into the global pressure vessel market, albeit from smaller bases.
- Babcock & Wilcox Enterprises Inc
- Doosan Enerbility Co. Ltd
- Alfa Laval AB
- Andritz AG
- Larsen & Toubro Ltd
- Ergil (Aager GmbH)
- IHI Plant Services Corp.
- Frames Group BV
- GEA Group AG
- Mitsubishi Heavy Industries Ltd
- CB&I (McDermott)
- Paul Mueller Company
- Halvorsen Company
- Westinghouse Electric Co.
- Hitachi Zosen Corp.
- Keller Technology
- Samuel Pressure Vessel Group
- Toyo Kanso Co.
- Parr Instrument Company
- Pressure Vessel Engineering (PVE)
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Energy infrastructure upgrades in emerging economies
- 4.2.2 Rising global LNG trade and associated cryogenic storage demand
- 4.2.3 Nuclear new-build resurgence in Asia
- 4.2.4 Stricter workplace safety regulations (API 510, PED, ASME)
- 4.2.5 Adoption of composite overwrapped pressure vessels (COPVs) in hydrogen mobility
- 4.2.6 Modular small-scale chemical processing skids
- 4.3 Market Restraints
- 4.3.1 Volatile steel prices squeezing OEM margins
- 4.3.2 Lengthy certification & compliance cycles
- 4.3.3 Slow commercialization of Generation IV nuclear designs
- 4.3.4 Scarcity of skilled welders & inspectors
- 4.4 Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Industry Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Material
- 5.1.1 Carbon Steel
- 5.1.2 Stainless Steel
- 5.1.3 Clad and Alloy Steels
- 5.1.4 Composites
- 5.1.5 Aluminium and Others
- 5.2 By Pressure Rating
- 5.2.1 0 to 10 bar (Low)
- 5.2.2 10 to 50 bar (Medium)
- 5.2.3 50 to 100 bar (High)
- 5.2.4 Above 100 bar (Ultra-high)
- 5.3 By Application
- 5.3.1 Storage Vessels
- 5.3.2 Process/Reactors
- 5.3.3 Heat Exchangers
- 5.3.4 Boilers
- 5.3.5 Others (Custom vessels, Specialty vessels, Expansion vessels)
- 5.4 By End-User Industry
- 5.4.1 Oil and Gas Upstream
- 5.4.2 Oil and Gas Mid/Downstream
- 5.4.3 Chemical and Petrochemical
- 5.4.4 Power Generation
- 5.4.5 Food and Beverage
- 5.4.6 Pharmaceuticals and Biotech
- 5.4.7 Water and Wastewater
- 5.4.8 Others
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Russia
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia Pacific
- 5.5.3.1 China
- 5.5.3.2 India
- 5.5.3.3 Japan
- 5.5.3.4 South Korea
- 5.5.3.5 ASEAN Countries
- 5.5.3.6 Rest of Asia Pacific
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 United Arab Emirates
- 5.5.5.3 South Africa
- 5.5.5.4 Egypt
- 5.5.5.5 Rest of Middle East and Africa
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves (M&A, Partnerships, PPAs)
- 6.3 Market Share Analysis (Market Rank/Share for key companies)
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Products & Services, and Recent Developments)
- 6.4.1 Babcock & Wilcox Enterprises Inc
- 6.4.2 Doosan Enerbility Co. Ltd
- 6.4.3 Alfa Laval AB
- 6.4.4 Andritz AG
- 6.4.5 Larsen & Toubro Ltd
- 6.4.6 Ergil (Aager GmbH)
- 6.4.7 IHI Plant Services Corp.
- 6.4.8 Frames Group BV
- 6.4.9 GEA Group AG
- 6.4.10 Mitsubishi Heavy Industries Ltd
- 6.4.11 CB&I (McDermott)
- 6.4.12 Paul Mueller Company
- 6.4.13 Halvorsen Company
- 6.4.14 Westinghouse Electric Co.
- 6.4.15 Hitachi Zosen Corp.
- 6.4.16 Keller Technology
- 6.4.17 Samuel Pressure Vessel Group
- 6.4.18 Toyo Kanso Co.
- 6.4.19 Parr Instrument Company
- 6.4.20 Pressure Vessel Engineering (PVE)
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment

