PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2124290

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2124290
K-12 Education - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the k-12 education market size stands at USD 3.54 trillion in 2026 and is projected to reach USD 5.83 trillion by 2031, expanding at a 10.51% CAGR.
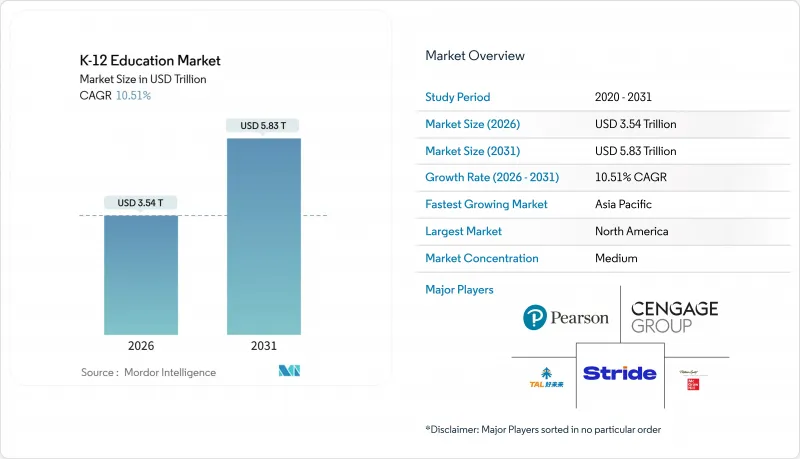
This report is Segmented by Institution Type (Public, and Private), Learning Model (Traditional In-Person, Hybrid, and More), Technology (Learning Management Systems (LMS), Digital Content and E-Textbooks, and More), Application (Pre-Primary and Primary School, Middle School, and High School), and Geography. The Market Sizes and Forecasts are Provided in Terms of Value (USD).
Global K-12 Education Market Trends and Insights
AI-Powered Learning Analytics Enhancing Student Outcomes
Predictive dashboards now surface mastery gaps in near real time, enabling timely intervention that lifts quarterly pass rates. U.S. districts using early-warning models flagged at-risk students with 78% accuracy in 2025, raising proficiency by 12 points. China followed suit, mandating adaptive assessments in 50,000 middle schools that year. India earmarked INR 50 billion (USD 600 million) for AI infrastructure, and pilots in Karnataka improved math scores 15% by the end of 2025. Vendors offering closed-loop systems diagnostics that feed automated lesson plans are capturing multi-year contracts, pressuring publishers that rely on static test banks. As training ramps and data standards settle, this driver will add the greatest boost to mid-term growth.
Government Mandates for Classroom Digitisation
Funding is increasingly tied to connectivity benchmarks and device penetration ratios. The U.S. Infrastructure Investment and Jobs Act steered USD 7.2 billion into school broadband upgrades, catalyzing cloud-platform adoption. Europe's Digital Education Action Plan committed EUR 10 billion (USD 11.3 billion) for interactive displays, with compliance audits by the European Commission in 2026. South Korea, Australia, and other early movers imposed deadlines for digital textbooks, unleashing multi-billion-dollar procurement waves. While the spending bolsters short-term revenue, districts must budget for recurring software renewals to sustain the gains.
Digital Divide in Rural and Low-Income Districts
Infrastructure gaps threaten to widen achievement inequities. In 2024, 9.7 million U.S. students lacked reliable home broadband, mostly in Appalachia, tribal lands, and the Mississippi Delta. Sub-Saharan Africa saw only 28% of schools electrified, rendering online tools impractical. India's rural device ratios reached 40:1 in 2025, forcing chalkboard fallback. Brazilian Northeast districts still trail urban adoption by 50%. Until subsidies and device-donation schemes scale, the digital divide will shave 1.3 points off near-term growth.
Other drivers and restraints analyzed in the detailed report include:
- Growing Penetration of Digital Devices and Broadband Access
- Rising Demand for Personalised and Adaptive Learning Platforms
- Student-Data Privacy Litigations Constraining Roll-Outs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Geography Analysis
North America retained 40.14% of 2025 revenue, underpinned by USD 7.2 billion in E-Rate connectivity grants and robust state mandates for digital content. U.S. districts allocate large line items to cloud subscriptions, analytics dashboards, and device refresh cycles, cementing incumbent vendor dominance. Canada invested CAD 1.2 billion (USD 880 million) in 2025 to extend smart-classroom access to Indigenous communities.
Asia-Pacific is the fastest-growing region at an 11.97% CAGR, propelled by China's nationwide AI-tutoring rollout and India's rural fiber program. The K-12 education market size in Asia-Pacific will eclipse North America before 2031 if current policy momentum endures. Governments continue subsidizing hardware and mandating adaptive-assessment platforms to mitigate teacher shortages.
Europe progresses more slowly due to stringent data-sovereignty rules that favor locally hosted or open-source systems, stretching procurement cycles. Germany's DigitalPakt Schule injected EUR 6.5 billion (USD 7.3 billion) through 2024, yet district implementation still lags 18 months behind funding awards. The United Kingdom improved device ownership among low-income households to 81% in 2025, aided by GBP 1.8 billion (USD 2.3 billion) investments.
South America and the Middle East and Africa remain fragmented. Brazil accounts for 55% of Latin American EdTech spending, though connectivity gaps persist in rural Northeast states. In the Middle East and Africa, smart-classroom pilots flourish in the United Arab Emirates and Saudi Arabia under Vision 2030, whereas South Africa and Nigeria grapple with infrastructure shortfalls. Vendors seeking regional growth must adapt pricing to variable purchasing power and offer off-line functionality where bandwidth remains scarce.
- McGraw-Hill Education
- Pearson plc
- Cengage Group
- Stride Inc.
- TAL Education Group
- Think and Learn Pvt Ltd (BYJU'S)
- Tata ClassEdge
- Next Education India Pvt Ltd
- Instructure Inc.
- Finalsite
- Google for Education (Alphabet)
- Microsoft Education
- Apple Education
- Kahoot ASA
- Blackboard Inc. (Anthology)
- DreamBox Learning
- ClassDojo
- Duolingo for Schools
- Seesaw Learning Inc.
- Desmos Studio PBC
- IXL Learning
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing Penetration of Digital Devices and Broadband Access
- 4.2.2 AI-Powered Learning Analytics Enhancing Student Outcomes
- 4.2.3 Government Mandates for Classroom Digitisation
- 4.2.4 Rising Demand for Personalised and Adaptive Learning Platforms
- 4.2.5 Emergence of Micro-Credentialing for Career Readiness
- 4.2.6 District-Level Open-Source Curriculum Collaborations
- 4.3 Market Restraints
- 4.3.1 Digital Divide in Rural and Low-Income Districts
- 4.3.2 Teacher Resistance to Technology Adoption
- 4.3.3 Student-Data Privacy Litigations Constraining Roll-Outs
- 4.3.4 Fragmented Procurement Processes Lengthening Sales Cycles
- 4.4 Industry Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Intensity of Competitive Rivalry
- 4.8 Impact of Macroeconomic Factors on the Market
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Institution Type
- 5.1.1 Public
- 5.1.2 Private
- 5.2 By Learning Model
- 5.2.1 Traditional In-Person
- 5.2.2 Hybrid
- 5.2.3 Fully Online / Virtual Schools
- 5.3 By Technology
- 5.3.1 Learning Management Systems (LMS)
- 5.3.2 Digital Content and e-Textbooks
- 5.3.3 Assessment and Analytics Tools
- 5.3.4 Collaboration and Communication Platforms
- 5.3.5 AR/VR and Simulation Tools
- 5.3.6 Other Technologies
- 5.4 By Application (Grade Level)
- 5.4.1 Pre-Primary and Primary School (K-5)
- 5.4.2 Middle School (6-8)
- 5.4.3 High School (9-12)
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 United Kingdom
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 India
- 5.5.4.3 Japan
- 5.5.4.4 South Korea
- 5.5.4.5 Australia
- 5.5.4.6 Rest of Asia-Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 Middle East
- 5.5.5.1.1 Saudi Arabia
- 5.5.5.1.2 United Arab Emirates
- 5.5.5.1.3 Turkey
- 5.5.5.1.4 Rest of Middle East
- 5.5.5.2 Africa
- 5.5.5.2.1 South Africa
- 5.5.5.2.2 Nigeria
- 5.5.5.2.3 Egypt
- 5.5.5.2.4 Rest of Africa
- 5.5.5.1 Middle East
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves and Partnerships
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 McGraw-Hill Education
- 6.4.2 Pearson plc
- 6.4.3 Cengage Group
- 6.4.4 Stride Inc.
- 6.4.5 TAL Education Group
- 6.4.6 Think and Learn Pvt Ltd (BYJU'S)
- 6.4.7 Tata ClassEdge
- 6.4.8 Next Education India Pvt Ltd
- 6.4.9 Instructure Inc.
- 6.4.10 Finalsite
- 6.4.11 Google for Education (Alphabet)
- 6.4.12 Microsoft Education
- 6.4.13 Apple Education
- 6.4.14 Kahoot ASA
- 6.4.15 Blackboard Inc. (Anthology)
- 6.4.16 DreamBox Learning
- 6.4.17 ClassDojo
- 6.4.18 Duolingo for Schools
- 6.4.19 Seesaw Learning Inc.
- 6.4.20 Desmos Studio PBC
- 6.4.21 IXL Learning
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

