PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2124322

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2124322
Enterprise WLAN - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the enterprise WLAN market size was valued at USD 24.86 billion in 2025 and estimated to grow from USD 27.98 billion in 2026 to reach USD 50.53 billion by 2031, at a CAGR of 12.55% during the forecast period (2026-2031).
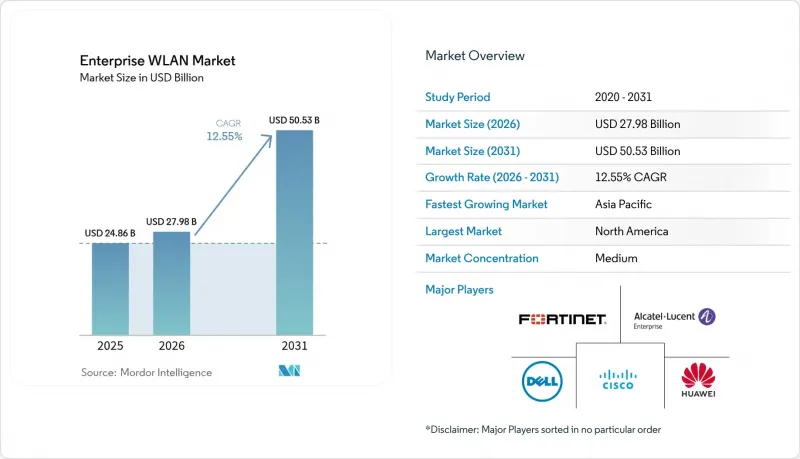
This report is Segmented by Component (Hardware, Software, and Services), Organization Size (Large Enterprises, Small and Medium-Sized Enterprises), End-User Vertical (Retail, Healthcare, Banking, Financial Services, and Insurance, Manufacturing, Education, and More), Deployment Mode (On-Premises and Cloud-Managed), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Enterprise WLAN Market Trends and Insights
Surge in Wi-Fi 6/6E Upgrade Cycles Drives Performance Leap
Key Highlights
- Opening 1,200 MHz of 6 GHz spectrum gives enterprises the first contiguous stretch of ultra-wide channels for multigigabit WLAN, and multi-link operation in Wi-Fi 7 boosts throughput while trimming latency. Video collaboration, immersive training, and AR-assisted maintenance demand such deterministic performance, prompting 40% of large organizations to bring forward refresh schedules. Indian regulators value the 6 GHz allocation at USD 4,030 billion in cumulative economic activity for 2024-2034, underscoring its macro impact.Yet higher power budgets and POE++ switches are prerequisites, nudging buyers to coordinate access-layer and switching upgrades in tandem.
Hybrid Work Models Demand Network Transformation
Hybrid work is now standard practice, requiring seamless roaming, granular access control, and application-level QoS across offices and homes. Enterprises allocate an average of USD 115.7 million over three years for advanced wireless projects to enable unified user experiences, VPN-grade security, and analytics-driven capacity planning. Passpoint (IEEE 802.11u) simplifies secure onboarding for employees and guests, lowering help-desk tickets while tightening identity assurance. The enterprise WLAN market benefits as CIOs align network modernization with workplace flexibility mandates
Persistent Supply-Chain Disruptions Constrain Growth
Lead times for network ASICs stretch up to 52 weeks in some data-center SKUs, prompting buyers to postpone rollouts or adopt cloud alternatives that lessen hardware dependence. Vendors with diversified suppliers weather shortages better and capture displaced demand. Extreme Networks cites pandemic-era resilience that unlocked new sales in healthcare refits.
Other drivers and restraints analyzed in the detailed report include:
- IoT Density Drives Network Architecture Evolution
- Cloud Management Transforms Operational Economics
- Cybersecurity Skills Gap Threatens Network Security
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Hardware contributed 60.55% of 2025 revenue, powered by demand for high-density Wi-Fi 6E access points that safeguard application performance in auditoriums, factories, and hospitals. Vendors bundle tri-radio designs, integrated IoT radios, and advanced RF analytics that justify premium price points. The enterprise WLAN market is now cycling through switch upgrades that supply 2.5 Gbps or 5 Gbps multigig Ethernet plus 90 W POE to drive next-generation APs. The software category, though smaller, is climbing at a 13.75% CAGR as AI-native cloud control, assurance analytics, and threat-centric micro-segmentation become indispensable. Mist AI and Cisco DNA Center illustrate how controller logic, network data lakes, and machine learning converge into single-pane experiences.
Access point firmware and license subscriptions convert once-periodic capital spending into recurring revenue, enticing investors and compressing refresh intervals. Meanwhile, professional and managed services flourish because organizations lack in-house RF planning and zero-trust design skills. Consultants orchestrate site surveys, spectrum audits, and compliance validation, adding stickiness to vendor ecosystems
Large enterprises held 57.35% of the enterprise WLAN market share in 2025, reflecting multi-campus estates that demand scaled authentication, policy engines, and resiliency. SD-branch architectures feeding into SASE frameworks align well with Fortune 1000 security mandates. Yet SMEs post the strongest 12.95% CAGR, encouraged by subscription-based WLAN as a service that removes controller hardware and heavy upfront cost. Cloud onboarding and automated RF optimization free smaller IT teams from arcane CLI workflows, making enterprise-grade features accessible without hiring certified wireless engineers.
Vendors repackage enterprise functionality into tiered offerings that emphasize quick deployment, pay-as-you-grow licensing, and mobile-first dashboards. MSP channels bundle WLAN with broadband and VoIP, deepening penetration among retail, hospitality, and professional services. As talent shortages persist, SMEs turn to outsourced monitoring, driving a services layer that grows in lockstep with cloud-managed adoption.
Complete Report Scope:
- By Component
- Hardware
- Access Points
- WLAN Controllers
- Wireless Hotspot Gateways
- Software
- WLAN Security
- WLAN Management
- WLAN Analytics
- Other Software
- Services
- Professional Services
- Managed Services
- Hardware
- By Organization Size
- Large Enterprises
- Small and Medium-sized Enterprises (SME)
- By End-user Vertical
- Banking, Financial Services and Insurance
- Healthcare
- Retail
- IT and Telecommunications
- Manufacturing
- Education
- Hospitality
- Other Verticals
- By Deployment Mode
- On-premises
- Cloud-managed
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Argentina
- Brazil
- Rest of South America
- Europe
- United Kingdom
- Germany
- France
- Italy
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- India
- Rest of Asia Pacific
- Middle East and Africa
- United Arab Emirates
- Saudi Arabia
- South Africa
- Rest of Middle and Africa
- North America
Geography Analysis
North America generated the highest revenue with a 38.40% share in 2025, buoyed by FCC-backed 6 GHz allocations that created an estimated USD 870 billion in economic value during 2023-2024. United States shipments swung sharply, down 30.6% year over year in Q2 2024, then rebounded 15.3% sequentially as backlogs cleared, according to InfotechLead. Federal broadband funding, smart-building incentives, and a vibrant managed services channel sustain spending across healthcare, education, and financial services.
Asia Pacific posts the fastest 13.05% CAGR between 2026 and 2031. China remains the biggest market, steered by industrial policies that favor digital factories and campus rollouts. India's policy think tank values unlicensed 6 GHz at USD 4,030 billion in cumulative impact through 2034, further catalyzing enterprise WLAN market demand. ASEAN members expand manufacturing footprints and modernize airports, both requiring high-density Wi-Fi and zero-trust segmentation.
Europe shows mixed momentum. Shipments sank 22.3% year over year in Q2 2024 amid macro headwinds, then ticked up modestly in Q3 as inventory normalization progressed, according to InfotechLead. The European Vision for 6G Network Ecosystems prioritizes AI-native and integrated sensing features, and spectrum regulators push common frameworks to accelerate vendor innovation.These initiatives will shape enterprise WLAN upgrades because interoperability between 5G-Advanced and Wi-Fi 7 is a design goal for campus environments.
The Middle East and Africa remain smaller but record double-digit growth as governments invest in smart cities. United Arab Emirates ministries deploy converged Wi-Fi/IoT networks in federal buildings, while South African retailers adopt cloud-managed WLAN to support omnichannel commerce. Latin America, starting from a low base, registered 235% year-over-year growth in Q3 2023 after supply bottlenecks eased and currency stability improved. The region's hospitality and mining sectors show particular interest in AI-assisted WLAN for guest services and remote site connectivity.
- Cisco Systems
- Hewlett Packard Enterprise Aruba
- Huawei Technologies
- Juniper Networks (Mist)
- Extreme Networks
- CommScope - Ruckus
- Dell Technologies
- Fortinet
- Ubiquiti Inc.
- Arista Networks
- Cambium Networks
- Zebra Technologies
- Netgear
- TP-Link Technologies
- Arista Networks
- Ruijie Networks
- Alcatel-Lucent Enterprise
- Huawei Technologies
- EnGenius Networks
- Cambium Networks
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Surge in Wi-Fi 6/6E upgrade cycles
- 4.2.2 Rapid adoption of BYOD and hybrid work
- 4.2.3 Exploding enterprise IoT node density
- 4.2.4 Cloud-managed WLAN lowers TCO
- 4.2.5 6 GHz spectrum allocations (global)
- 4.2.6 Smart-building stimulus funds
- 4.3 Market Restraints
- 4.3.1 Chip-set supply-chain volatility
- 4.3.2 Skills gap in Wi-Fi design and security
- 4.3.3 Enterprise private-5G substitution risk
- 4.3.4 Rising cybersecurity insurance premiums
- 4.4 Value Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 COVID-19 Impact Assessment
- 4.9 Investment Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Component
- 5.1.1 Hardware
- 5.1.1.1 Access Points
- 5.1.1.2 WLAN Controllers
- 5.1.1.3 Wireless Hotspot Gateways
- 5.1.2 Software
- 5.1.2.1 WLAN Security
- 5.1.2.2 WLAN Management
- 5.1.2.3 WLAN Analytics
- 5.1.2.4 Other Software
- 5.1.3 Services
- 5.1.3.1 Professional Services
- 5.1.3.2 Managed Services
- 5.1.1 Hardware
- 5.2 By Organization Size
- 5.2.1 Large Enterprises
- 5.2.2 Small and Medium-sized Enterprises (SME)
- 5.3 By End-user Vertical
- 5.3.1 Banking, Financial Services and Insurance
- 5.3.2 Healthcare
- 5.3.3 Retail
- 5.3.4 IT and Telecommunications
- 5.3.5 Manufacturing
- 5.3.6 Education
- 5.3.7 Hospitality
- 5.3.8 Other Verticals
- 5.4 By Deployment Mode
- 5.4.1 On-premises
- 5.4.2 Cloud-managed
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Argentina
- 5.5.2.2 Brazil
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 United Kingdom
- 5.5.3.2 Germany
- 5.5.3.3 France
- 5.5.3.4 Italy
- 5.5.3.5 Rest of Europe
- 5.5.4 Asia-Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 South Korea
- 5.5.4.4 India
- 5.5.4.5 Rest of Asia Pacific
- 5.5.5 Middle East and Africa
- 5.5.5.1 United Arab Emirates
- 5.5.5.2 Saudi Arabia
- 5.5.5.3 South Africa
- 5.5.5.4 Rest of Middle and Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Cisco Systems
- 6.4.2 Hewlett Packard Enterprise Aruba
- 6.4.3 Huawei Technologies
- 6.4.4 Juniper Networks (Mist)
- 6.4.5 Extreme Networks
- 6.4.6 CommScope - Ruckus
- 6.4.7 Dell Technologies
- 6.4.8 Fortinet
- 6.4.9 Ubiquiti Inc.
- 6.4.10 Arista Networks
- 6.4.11 Cambium Networks
- 6.4.12 Zebra Technologies
- 6.4.13 Netgear
- 6.4.14 TP-Link Technologies
- 6.4.15 Arista Networks
- 6.4.16 Ruijie Networks
- 6.4.17 Alcatel-Lucent Enterprise
- 6.4.18 Huawei Technologies
- 6.4.19 EnGenius Networks
- 6.4.20 Cambium Networks
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment

