PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2124614

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2124614
Central Nervous System Therapeutics - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, central nervous system therapeutics market size in 2026 is estimated at USD 143.32 billion, growing from 2025 value of USD 134.42 billion with 2031 projections showing USD 197.35 billion, growing at 6.62% CAGR over 2026-2031.
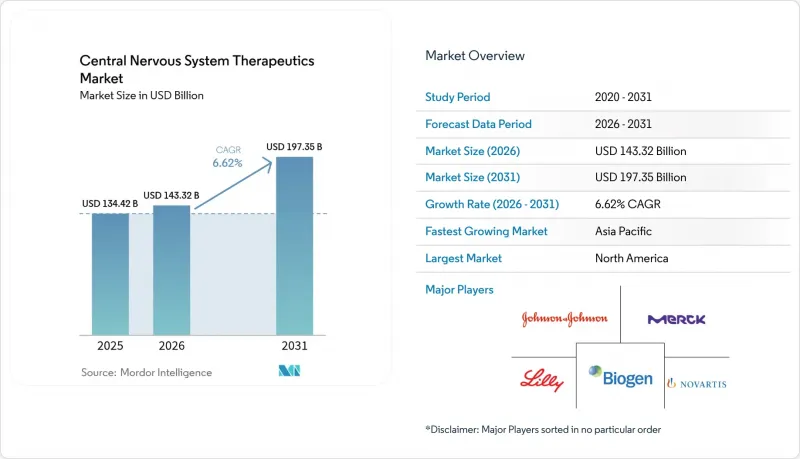
This report is Segmented by Therapeutic Class (Antidepressants, Antipsychotics, and More), Diseases (Neurovascular, Trauma, and More), Drug Type (Small Molecule, Biologic/Large Molecule), Route of Administration (Oral, Parenteral, Others), and Geography (North America, Europe, and More). The Market Forecasts are Provided in Terms of Value (USD).
Global Central Nervous System Therapeutics Market Trends and Insights
Aging Population & Rising CNS Disorder Prevalence
Neurological disorders affected 3.4 billion people in 2024, making them the leading global source of disability-adjusted life years. Incidence accelerates beyond age 65, driving sustained demand for the central nervous system therapeutics market. Annual caregiving costs for cognitive decline reached USD 1.1 trillion in developed economies, motivating payers to endorse interventions that delay institutionalization. Early diagnosis paired with disease-modifying drugs is therefore viewed as fiscally prudent by insurers. As demographic aging is irreversible over the forecast horizon, this demand vector remains the single most durable growth catalyst for the central nervous system therapeutics market.
Growing Generic Penetration Post-LOE
Lyrica generics captured 85% of prescription volume within 18 months of US exclusivity loss, illustrating how quickly price erosion strikes blockbuster CNS brands. Lower cost options widen patient access in emerging economies, swelling treated populations and cementing the central nervous system therapeutics market as a core expenditure line for public payers. Simultaneously, originators accelerate next-generation assets and novel delivery modes that command premium pricing and resist substitution, keeping innovation cycles active.
High Clinical Trial Failure Rates in Neurology
A 92% attrition rate afflicts neurological pipelines, the worst among therapeutic areas. Complex pathophysiology, blood-brain-barrier permeability hurdles, and heterogeneous patient presentations thwart translation of preclinical signals. High-profile setbacks such as emraclidine and dalzanemdor underscore persistent risk. Capital-intensive trials deter smaller firms, fostering consolidation as deep-pocketed pharmas acquire distressed assets, yet overall innovation velocity suffers, tempering the growth outlook for the central nervous system therapeutics market.
Other drivers and restraints analyzed in the detailed report include:
- Favorable Reimbursement for Breakthrough CNS Drugs
- Improved Neuroimaging & Biomarker-Based Diagnosis
- Stringent CNS Safety Labeling Requirements
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
The disease-modifying cohort is on track to expand at a 6.83% CAGR, outpacing all other categories inside the central nervous system therapeutics market. Antidepressants remain the volume leader at 25.12% 2025 share, sustained by widespread prescribing in primary care. Investor interest has pivoted, however, toward agents that alter disease course, exemplified by Bristol Myers Squibb's USD 14 billion outlay for KarXT. These transactions channel capital into regenerative pathways, immunomodulation, and synaptic repair platforms.
Antipsychotics receive renewed momentum following KarXT, while antiepileptics confront steep generic penetration. Analgesics suffer margin squeeze, yet specialty migraine biologics retain pricing strength. Neurodegeneration assets attract premium valuations despite modest efficacy because any delay in progression yields sizeable societal savings. Convergence is emerging as firms test combo regimens pairing symptomatic relief with disease modification, blurring historic therapeutic silos within the central nervous system therapeutics market.
Depression kept 27.55% of 2025 revenues, but Alzheimer's disease is forecast to post a 7.05% CAGR, the fastest among indications. Reimbursement of lecanemab and pipeline agents such as donanemab creates a multibillion-dollar addressable segment that was previously untapped. Mental-health indications also benefit from digital therapeutics that extend reach beyond traditional clinical settings.
Neurovascular disorders and rare epilepsies remain underserved niches offering orphan-drug pricing power. Infection-linked neurological sequelae and oncology crossover therapies are slowly enlarging, aided by heightened research into latent viral impacts on the CNS. These diverse disease-level dynamics reinforce multi-modal portfolio strategies inside the central nervous system therapeutics market.
Complete Report Scope:
- By Therapeutic Class (Value)
- Antidepressants
- Antipsychotics
- Antiepileptics
- Analgesics (Neuropathic & Migraine)
- Disease-Modifying (MS, ALS, etc.)
- Neurodegeneration (AD, PD)
- Others
- By Diseses
- Neurovascular Diseases
- Trauma
- Mental Health
- Anxiety Disorders
- Epilepsy
- Psychotic Disorders
- Other Mental Health Disorders
- Degenerative Diseases
- Alzheimer's Disease
- Parkinson's Disease
- Multiple Sclerosis
- Amyotrophic Lateral Sclerosis
- Other Degenerative Diseases
- Infectious Diseases
- Cancer
- Other Diseases
- By Drug Type (Value)
- Small Molecule
- Biologic /Large Molecule
- By Route of Administration (Value)
- Oral
- Parenteral
- Others
- By Geography (Value)
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- India
- Japan
- South Korea
- Australia
- Rest of Asia-Pacific
- South America
- Brazil
- Argentina
- Rest of South America
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- North America
Geography Analysis
North America accounted for 45.01% of 2025 revenue, underpinned by Medicare coverage expansions and dense clinical-trial infrastructure. The United States leads with sophisticated payer frameworks that adopt value-based contracts, whereas Canada provides stable uptake through universal coverage. Mexico is emerging on the back of growing middle-class insurance penetration. Pricing pressures from generic proliferation and buyer consolidation temper revenue per patient but are offset by the premium commanded by innovative launches, sustaining leadership for the central nervous system therapeutics market.
Asia-Pacific is the growth heartbeat, projected at 7.78% CAGR, driven by China's regulatory liberalization, Japan's fast-track approvals, and India's expanding access programs. Rapid urbanization correlates with higher incidence of mood and anxiety disorders, unlocking volume. Japan and South Korea anchor regional clinical trials, while Southeast Asian nations import affordable generics to widen coverage. Government recognition of neurological disease burden is translating into reimbursement reforms that uplift market value, positioning the region as a pivotal expansion arena for the central nervous system therapeutics market.
Europe delivers steady gains through EMA-coordinated pathways and universal healthcare. Germany and the United Kingdom dominate launches due to robust assessment agencies, whereas southern European markets contribute scale. The new Clinical Trials Information System streamlines submissions, slightly trimming timelines. Cost-effectiveness scrutiny remains stringent, sometimes delaying premium products, yet predictable reimbursement decisions create long-tail revenue stability. Collectively, these continental patterns diversify growth drivers and risk profiles for stakeholders in the central nervous system therapeutics market.
- Biogen
- Pfizer
- Eli Lilly and Company
- Johnson & Johnson
- Novartis
- Otsuka
- Lundbeck A/S
- Teva Pharmaceutical Industries
- UCB
- GlaxoSmithKline
- Merck
- Roche
- Amgen
- AstraZeneca
- Takeda Pharmaceuticals
- Sunovion Pharmaceuticals
- Jazz Pharmaceuticals plc
- ACADIA Pharmaceuticals Inc.
- Sage Therapeutics
- Marinus Pharmaceuticals, Inc.
- GW Pharmaceuticals
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Aging population & rising CNS disorder prevalence
- 4.2.2 Growing generic penetration post-LOE
- 4.2.3 Favorable reimbursement for breakthrough CNS drugs
- 4.2.4 Improved neuroimaging & biomarker-based diagnosis
- 4.2.5 Psychedelic-assisted therapy clinical wins
- 4.2.6 Venture funding into CNS-focused digital twins
- 4.3 Market Restraints
- 4.3.1 High clinical trial failure rates in neurology
- 4.3.2 Generic erosion of blockbusters (e.g., Lyrica)
- 4.3.3 Stringent CNS safety labeling requirements
- 4.3.4 Supply-chain scarcity of specialized excipients
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts
- 5.1 By Therapeutic Class (Value)
- 5.1.1 Antidepressants
- 5.1.2 Antipsychotics
- 5.1.3 Antiepileptics
- 5.1.4 Analgesics (Neuropathic & Migraine)
- 5.1.5 Disease-Modifying (MS, ALS, etc.)
- 5.1.6 Neurodegeneration (AD, PD)
- 5.1.7 Others
- 5.2 By Diseses
- 5.2.1 Neurovascular Diseases
- 5.2.2 Trauma
- 5.2.3 Mental Health
- 5.2.3.1 Anxiety Disorders
- 5.2.3.2 Epilepsy
- 5.2.3.3 Psychotic Disorders
- 5.2.3.4 Other Mental Health Disorders
- 5.2.4 Degenerative Diseases
- 5.2.4.1 Alzheimer's Disease
- 5.2.4.2 Parkinson's Disease
- 5.2.4.3 Multiple Sclerosis
- 5.2.4.4 Amyotrophic Lateral Sclerosis
- 5.2.4.5 Other Degenerative Diseases
- 5.2.5 Infectious Diseases
- 5.2.6 Cancer
- 5.2.7 Other Diseases
- 5.3 By Drug Type (Value)
- 5.3.1 Small Molecule
- 5.3.2 Biologic /Large Molecule
- 5.4 By Route of Administration (Value)
- 5.4.1 Oral
- 5.4.2 Parenteral
- 5.4.3 Others
- 5.5 By Geography (Value)
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 India
- 5.5.3.3 Japan
- 5.5.3.4 South Korea
- 5.5.3.5 Australia
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 South America
- 5.5.4.1 Brazil
- 5.5.4.2 Argentina
- 5.5.4.3 Rest of South America
- 5.5.5 Middle East and Africa
- 5.5.5.1 GCC
- 5.5.5.2 South Africa
- 5.5.5.3 Rest of Middle East and Africa
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 6.3.1 Biogen Inc.
- 6.3.2 Pfizer Inc.
- 6.3.3 Eli Lilly and Company
- 6.3.4 Johnson & Johnson (Janssen)
- 6.3.5 Novartis AG
- 6.3.6 Otsuka Holdings Co., Ltd.
- 6.3.7 Lundbeck A/S
- 6.3.8 Teva Pharmaceutical Industries Ltd.
- 6.3.9 UCB S.A.
- 6.3.10 GlaxoSmithKline plc
- 6.3.11 Merck & Co., Inc.
- 6.3.12 Roche Holding AG
- 6.3.13 Amgen Inc.
- 6.3.14 AstraZeneca plc
- 6.3.15 Takeda Pharmaceutical Company Limited
- 6.3.16 Sunovion Pharmaceuticals Inc.
- 6.3.17 Jazz Pharmaceuticals plc
- 6.3.18 ACADIA Pharmaceuticals Inc.
- 6.3.19 Sage Therapeutics, Inc.
- 6.3.20 Marinus Pharmaceuticals, Inc.
- 6.3.21 GW Pharmaceuticals plc
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment

