PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2124632

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2124632
United States School Bus - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
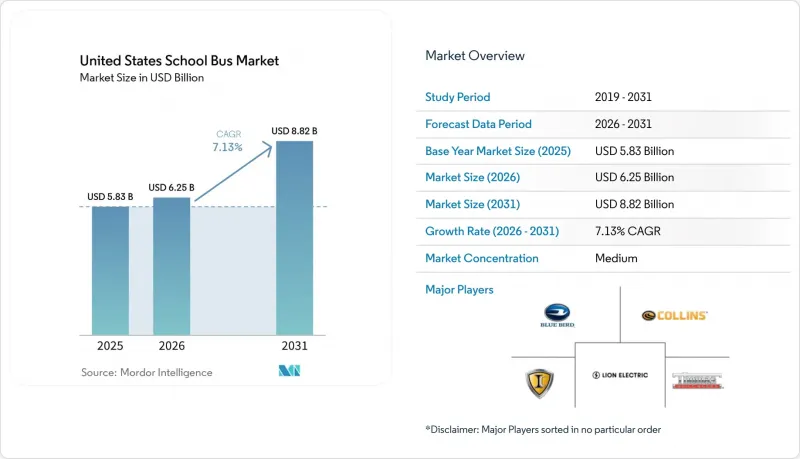
According to Mordor Intelligence, the United States school bus market size was valued at USD 5.83 billion in 2025 and estimated to grow from USD 6.25 billion in 2026 to reach USD 8.82 billion by 2031, at a CAGR of 7.13% during the forecast period (2026-2031).
This report is Segmented by Design Type (Type A (Cut-Away), Type B, and More), Powertrain Type (Internal Combustion Engine and Hybrid and Electric), Ownership Model (District-Owned Fleets and Contractor-Owned Fleets), and Seating Capacity (Less Than 30 Seats, 30-60 Seats, and More). The Market Forecasts are Provided in Terms of Value (USD) and Volume (Units).
United States School Bus Market Trends and Insights
Federal Funding Surge via EPA Clean School Bus Program
Congress allocated USD 5 billion over five years (FY 2022-2026) to accelerate fleet electrification, and the third funding round in September 2024 awarded USD 965 million in rebates that cover a notable share of the diesel-to-electric price gap . The incentive structure is heavily skewed toward zero-emission vehicles, prompting districts to compress traditional 10-year replacement cycles into 3-to-5-year windows. Equity provisions direct a disproportionate share of rebates to high-need rural and tribal communities, broadening the customer base for manufacturers. OEM order books now stretch up to 24 months, signalling sustained demand momentum through 2027. The funding cadence also gives financing partners long-term visibility, spurring new depot-as-a-service offerings that anchor the United States school bus market.
Aging National Fleet (Above 11 yrs) Pushing Replacement Demand
By 2024, a significant portion of the United States school buses surpassed the 11-year mark, a consequence of deferred spending following the 2008-2012 recession. Maintenance on these aging buses has become increasingly costly, prompting many to consider accelerated scrappage. Issues like rust-belt corrosion, diesel particulate filter failures, and frame fatigue are leading to emergency retirements, especially in states like Ohio, Michigan, and Pennsylvania. A thriving market for used buses has emerged, with resale values potentially offsetting a substantial portion of the added costs for districts transitioning to battery models. This demographic surge provides a buffer, shielding the United States school bus market from fluctuations in enrollment.
Sparse Rural Charging Infrastructure
Rural districts are compelled to invest in oversized battery packs, as many non-metropolitan counties find themselves without a DC fast-charging station within a reasonable distance. The situation is exacerbated by sub-zero winters, which can significantly diminish the bus range. Moreover, local substations frequently provide less than half of the power required for a depot servicing a full fleet of buses. While federal NEVI funds focus on highway corridors, they largely overlook funding for last-mile depot access. Upgrading the grid can involve substantial costs, hindering rural electrification efforts and dampening growth prospects for the United States school bus market, especially in areas beyond urban and suburban locales.
Other drivers and restraints analyzed in the detailed report include:
- Stringent On-board Safety Mandates Accelerating Fleet Renewal
- Low-NOx "Other Fuels" Demand in Non-attainment Counties
- High Upfront Cost of E-Buses Despite Incentives
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Type C conventional buses accounted for 79.12% of 2025 deliveries and are projected to expand faster than the wider United States school bus market at a 9.02% CAGR through 2031. Their 54-84 passenger capacity, maneuverability, and front-engine design suit the mixed-density routes common in suburban districts. Electric conversions are easier on Type C frames, requiring smaller battery packs and offering better cold-weather performance than rear-engine Type D models.
Type D transit buses hold a nominal share and dominate dense urban corridors where routes exceed 80 passengers. The steep price premium and depot space limitations constrain broader uptake. Type A cutaways, with under-30-seat layouts, fill rural and special-needs niches and will grow at a notable CAGR. Their commercial van chassis improves fuel economy and lowers maintenance costs, providing an attractive entry point for small districts transitioning to alternative energy. Design diversification, therefore, underpins steady growth within the United States school bus market.
Hybrid and electric units are forecast to grow at a 36.45% CAGR through 2031, although internal-combustion engines retained 88.35% of the United States school bus market share in 2025. The premium price tag on electric powertrains is narrowing as federal rebates stack with state incentives, especially in California and New York. Electric deployments increased in coastal states that have firm zero-emission deadlines, while diesel remains entrenched in the Southeast and Great Plains due to cheaper fuel and limited charging infrastructure. Renewable diesel compatibility and advanced emissions after-treatment are extending the runway for traditional engines, offering a bridge strategy where grid readiness lags.
Electric bus makers are clustering production in the Midwest to capture Buy America credits, and battery suppliers are co-locating to minimize logistics costs. Lion Electric's Joliet plant aims for significant annual output, hinting at potential scale efficiencies that might reduce acquisition costs by 2028. In response, diesel offerings have introduced duty-cycle-optimized engines, achieving a notable reduction in particulate emissions and compatibility with hydrotreated vegetable oil. Meanwhile, hybrids are becoming less relevant as districts leap directly to zero-emission technologies. This shift not only maximizes incentive capture but also channels investments into battery platforms, bolstering the overall momentum of the United States school bus market.
Complete Report Scope:
- By Design Type
- Type A (Cut-away)
- Type B
- Type C (Conventional)
- Type D (Transit-Style)
- By Powertrain Type
- Internal Combustion Engine (IC Engine)
- Hybrid and Electric
- By Ownership Model
- District-Owned Fleets
- Contractor-Owned Fleets
- By Seating Capacity
- Less than 30 Seats
- 30-60 Seats
- Above 60 Seats
List of Companies Covered in this Report:
- Blue Bird Corporation
- Daimler Truck North America LLC (Thomas Built)
- Navistar Inc. (IC Bus)
- Collins Bus Corporation
- Lion Electric Company
- GreenPower Motor Company Inc.
- Micro Bird Inc. (Girardin)
- BYD Motors USA
- Van-Con, Inc.
- Starcraft Bus
- Trans Tech Bus
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Federal Funding Surge via EPA Clean School Bus Program
- 4.2.2 Aging National Fleet (Above 11 yrs) Pushing Replacement Demand
- 4.2.3 Stringent On-board Safety Mandates Accelerating Fleet Renewal
- 4.2.4 Low-NOx "Other Fuels" Demand in Non-attainment Counties
- 4.2.5 Vehicle-to-Grid (V2G) Revenue Potential for School Districts
- 4.2.6 Depot Micro-grid and Solar Pairing Lowers Electric TCO
- 4.3 Market Restraints
- 4.3.1 Sparse Rural Charging Infrastructure
- 4.3.2 High Upfront Cost of E-Buses Despite Incentives
- 4.3.3 Scarcity of High-Voltage Maintenance Technicians
- 4.3.4 Medium-Duty Chassis Supply Bottlenecks
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory & Funding Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces
- 4.7.1 Bargaining Power of Suppliers
- 4.7.2 Bargaining Power of Buyers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value (USD) and Volume (Units))
- 5.1 By Design Type
- 5.1.1 Type A (Cut-away)
- 5.1.2 Type B
- 5.1.3 Type C (Conventional)
- 5.1.4 Type D (Transit-Style)
- 5.2 By Powertrain Type
- 5.2.1 Internal Combustion Engine (IC Engine)
- 5.2.2 Hybrid and Electric
- 5.3 By Ownership Model
- 5.3.1 District-Owned Fleets
- 5.3.2 Contractor-Owned Fleets
- 5.4 By Seating Capacity
- 5.4.1 Less than 30 Seats
- 5.4.2 30-60 Seats
- 5.4.3 Above 60 Seats
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Strategic Moves & Partnerships
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, SWOT Analysis, and Recent Developments)
- 6.4.1 Blue Bird Corporation
- 6.4.2 Daimler Truck North America LLC (Thomas Built)
- 6.4.3 Navistar Inc. (IC Bus)
- 6.4.4 Collins Bus Corporation
- 6.4.5 Lion Electric Company
- 6.4.6 GreenPower Motor Company Inc.
- 6.4.7 Micro Bird Inc. (Girardin)
- 6.4.8 BYD Motors USA
- 6.4.9 Van-Con, Inc.
- 6.4.10 Starcraft Bus
- 6.4.11 Trans Tech Bus
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment

