PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2124656

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2124656
United States Aluminum Beverage Cans - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the United States aluminum beverage cans market size in 2026 is estimated at USD 28.9 billion, growing from 2025 value of USD 28.10 billion with 2031 projections showing USD 33.26 billion, growing at 2.85% CAGR over 2026-2031.
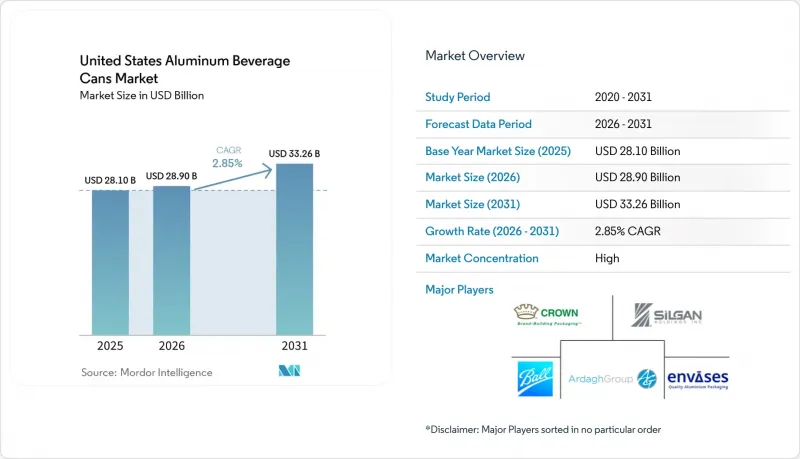
This report is Segmented by Type (Two-Piece Draw-And-Iron D and I, and Three-Piece Welded), Beverage Types (Carbonated Soft Drinks, Beer, Flavoured Alcoholic Drinks/Hard Seltzer, Energy Drinks, and More), Can Size (<=12 Oz, 12-16 Oz, 16-24 Oz, >24 Oz), Distribution Channel (Direct Sales, and Indirect Sales). The Market Forecasts are Provided in Terms of Value (USD).
United States Aluminum Beverage Cans Market Trends and Insights
Growing Demand from Non-Alcoholic Beverage Producers
Energy drink and ready-to-drink coffee brands favor aluminum formats to boost shelf life and brand differentiation. Red Bull's Phoenix complex runs a through-the-wall setup that merges can making with beverage filling, trimming logistics costs, and protecting its proprietary 250 ml format. National retailers report that aluminum containers lift premium shelf pricing by 6-8%, allowing functional beverage makers to maintain margins despite stiff competition. RTD tea producers similarly leverage aluminum's light barrier to save 25% in cold-chain expenses compared with PET. These format advantages are translating into firm purchase commitments that lock in rolled sheet contracts through 2027. As demand widens beyond energy drinks into sports nutrition beverages, small fillers expect can volumes to rise another 5% annually.
Surge in Craft Beer and Hard Seltzer Launches
Hard seltzer's sleek 12 oz profile became a packaging standard after multiple brands captured double-digit share in flavored alcohol sales during 2024. Craft breweries that once relied on bottles migrated to cans as large converters like Ball offered short-run graphics and lighter gauge material. However, spot buyers paid up to 60% premiums in 2024 when contract volumes were fully allocated, forcing many small breweries to secure distributor-managed inventory buffers. With capacity additions coming online, price gaps are narrowing, yet sleek and 16 oz formats continue to dominate new product launches as consumers associate cans with freshness and recyclability. The trend is likely to persist as alcoholic sparkling teas and spirit-based RTDs replicate hard seltzer's marketing playbook.
PET Lightweighting and Tethered-Cap Compliance
Competing PET bottle suppliers trimmed resin by up to 10% per unit in 2024, narrowing the delivered-cost gap with cans. European tethered-cap mandates inspired a pipeline of universal lid systems that global beverage multinationals could adopt across regions, threatening can volumes if consumer acceptance grows. State-level extended producer responsibility legislation will add further compliance costs to all packaging materials, though aluminum's 30-day average recycling loop remains an advantage. To counter PET's advances, can makers are testing even thinner gauges and exploring printable embossing to maintain brand shelf impact without extra weight.
Other drivers and restraints analyzed in the detailed report include:
- Corporate ESG Targets Favoring Infinitely Recyclable Packaging
- Aluminum Smelter Capacity Expansions in North America
- Domestic Aluminum Price Volatility from Section 232 Tariffs
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Two-piece draw-and-iron cans accounted for 88.35% of the United States aluminum beverage cans market share in 2025, and performance gains should lift this segment at a 3.58% CAGR to 2031. Ball's STARcan family already delivers up to 8% weight savings versus legacy D and I designs, reinforcing margins as metal premiums rise. Incremental lightweighting through base compression and alloy refinements reduces material consumption while preserving the top-load strength required for high-speed filling. Embedded vision systems now inspect every formed shell, cutting defect rates below 50 parts per million and minimizing scrap.
Three-piece welded cans remain a niche for specialty beverages that favor distinctive shapes, yet the FDA's PFAS phase-out will drive coating redesign and could accelerate their decline. Production cycle times for welded formats remain roughly 30% slower than high-speed D and I lines, discouraging volume beverages from adopting them. Nonetheless, select craft producers opt for three-piece to create retro branding cues, and aerospace-grade coatings under development may extend shelf life for acidic juice blends. Capital requirements for D and I presses, however, still deter small fillers, leaving limited pockets of demand for welded cans.
Flavored alcoholic beverages, led by hard seltzer line extensions, are forecast to post a 3.95% CAGR and will continue outpacing core beer volumes through 2031. Sleek 12-oz formats deliver strong visual differentiation at retail while catering to calorie-conscious consumers who prefer smaller serving sizes. Carbonated soft drinks retain a broad consumption base, but growth trails functional beverage categories that promise energy, immunity, or hydration benefits.
RTD coffee and tea exploit aluminum's barrier to oxygen and light, allowing ambient shipping for products that once required costly refrigeration. As nitro coffee grows, pressurized aluminum containers provide consistent crema, sparking partnerships between independent roasters and regional canners. Energy drinks sustain volume growth in 16 oz sizes, cementing aluminum's role in high-impact branding with matte and textured finishes. Innovations in can lining chemistry now tolerate low-pH citrus mixes, opening potential for canned juice cocktails.
Complete Report Scope:
- By Material Type
- Aluminium
- Steel
- By Can Structure
- Two-Piece
- Three-Piece
- Monobloc Aerosol
- By Capacity / Size
- <=12 oz
- 250-500 ml
- 500-1,000 ml
- >1,000 ml
- By Manufacturing Process
- Drawn and Ironed (DandI)
- Drawn and Redrawn (DRD)
- Impact Extrusion
- By End-User Industry
- Food
- Beverage
- Personal Care and Cosmetics
- Pharmaceuticals
- Paints and Industrial Chemicals
- Automotive Fluids and Lubricants
- Other End-User Industry
List of Companies Covered in this Report:
- Crown Holdings, Inc.
- Ball Corporation
- Silgan Holdings Inc.
- Mauser Packaging Solutions Holding Company
- Ardagh Metal Packaging S.A.
- DS Containers, LLC
- CCL Industries Inc. (CCL Container division)
- Independent Can Company
- Tecnocap S.p.A.
- CAN-PACK S.A.
- Allstate Can Corporation
- Envases Universales Group
- Trivium Packaging B.V.
- Greif, Inc.
- Toyo Seikan Group Holdings, Ltd.
- Montebello Packaging Inc.
- Berlin Packaging LLC
- TricorBraun Inc.
- Crown Cork and Seal USA, Inc.
- Metal Container Corporation
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Drivers
- 4.1.1 High recyclability rates of metal packaging
- 4.1.2 Convenience and extended shelf life offered by canned foods
- 4.1.3 Craft-beer and RTD beverage boom boosting can demand
- 4.1.4 Regulatory push for sustainable, single-material packaging
- 4.1.5 Lightweighting innovations lowering per-unit can cost
- 4.1.6 Brand-owner circular-packaging pledges securing can volumes
- 4.2 Market Restraints
- 4.2.1 Proliferation of alternate packaging formats (PET, pouches)
- 4.2.2 Volatility in aluminum and steel input prices
- 4.2.3 BPA-substitute migration concerns affecting consumer trust
- 4.2.4 Domestic can-sheet capacity constraints creating supply risk
- 4.3 Industry Value Chain Analysis
- 4.4 Porter's Five Forces Analysis
- 4.4.1 Bargaining Power of Suppliers
- 4.4.2 Bargaining Power of Buyers
- 4.4.3 Threat of New Entrants
- 4.4.4 Threat of Substitutes
- 4.4.5 Intensity of Competitive Rivalry
- 4.5 The Impact of Macroeconomic Factors on the Market
- 4.6 Regulatory Landscape
- 4.7 Technological Outlook
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Material Type
- 5.1.1 Aluminium
- 5.1.2 Steel
- 5.2 By Can Structure
- 5.2.1 Two-Piece
- 5.2.2 Three-Piece
- 5.2.3 Monobloc Aerosol
- 5.3 By Capacity / Size
- 5.3.1 <=12 oz
- 5.3.2 250-500 ml
- 5.3.3 500-1,000 ml
- 5.3.4 >1,000 ml
- 5.4 By Manufacturing Process
- 5.4.1 Drawn and Ironed (DandI)
- 5.4.2 Drawn and Redrawn (DRD)
- 5.4.3 Impact Extrusion
- 5.5 By End-User Industry
- 5.5.1 Food
- 5.5.2 Beverage
- 5.5.3 Personal Care and Cosmetics
- 5.5.4 Pharmaceuticals
- 5.5.5 Paints and Industrial Chemicals
- 5.5.6 Automotive Fluids and Lubricants
- 5.5.7 Other End-User Industry
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, and Recent Developments)
- 6.4.1 Crown Holdings, Inc.
- 6.4.2 Ball Corporation
- 6.4.3 Silgan Holdings Inc.
- 6.4.4 Mauser Packaging Solutions Holding Company
- 6.4.5 Ardagh Metal Packaging S.A.
- 6.4.6 DS Containers, LLC
- 6.4.7 CCL Industries Inc. (CCL Container division)
- 6.4.8 Independent Can Company
- 6.4.9 Tecnocap S.p.A.
- 6.4.10 CAN-PACK S.A.
- 6.4.11 Allstate Can Corporation
- 6.4.12 Envases Universales Group
- 6.4.13 Trivium Packaging B.V.
- 6.4.14 Greif, Inc.
- 6.4.15 Toyo Seikan Group Holdings, Ltd.
- 6.4.16 Montebello Packaging Inc.
- 6.4.17 Berlin Packaging LLC
- 6.4.18 TricorBraun Inc.
- 6.4.19 Crown Cork and Seal USA, Inc.
- 6.4.20 Metal Container Corporation
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment

