PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2124672

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2124672
Fluid Power Equipment - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the fluid power equipment market size is expected to grow from USD 69.98 billion in 2025 to USD 73.07 billion in 2026 and is forecast to reach USD 90.72 billion by 2031 at 4.42% CAGR over 2026-2031.
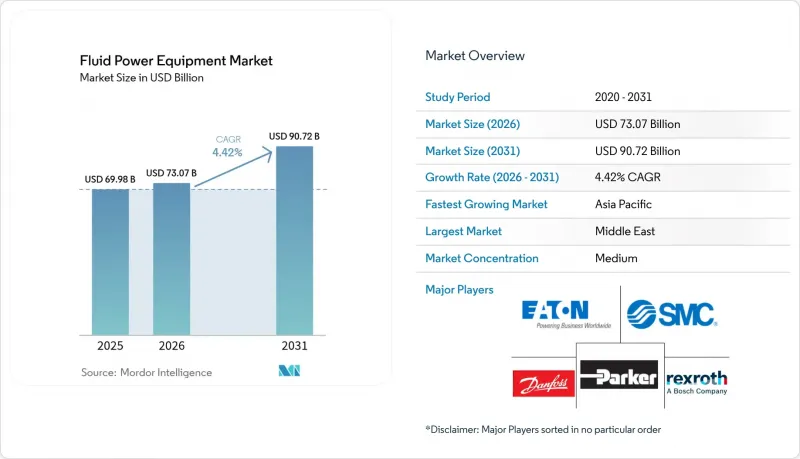
This report is Segmented by Technology (Hydraulic Equipment, and Pneumatic Equipment), Product Type (Pumps, Motors, Valves, Cylinders, and Accumulators and Filters), End-User Industry (Construction, Agriculture, Material Handling and Logistics, Aerospace and Defense and More), Distribution Channel (OEM, and Aftermarket), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Fluid Power Equipment Market Trends and Insights
Energy Efficiency and Environmental Considerations
Regulations such as CARB Tier 5 and forthcoming EPA 2027 rules are accelerating the adoption of high-efficiency pumps, motors and valves in mobile and stationary equipment. Variable-speed drives paired with IE5 synchronous reluctance motors are cutting pump electricity use by up to 60 % in municipal water utilities. Digital hydraulic valves managed through pulse-width modulation are eliminating throttling losses, raising hydrostatic transmission efficiency by 15-36 %. Parker Hannifin aims to lower its operational carbon footprint 50 % by 2030, a target that underpins demand for its energy-optimized components. Combined, these forces lift the fluid power equipment market by driving retrofit and replacement activity across core applications.
Advances in Industrial Automation
Industry 4.0 architectures allow fluid power components to communicate operating parameters in real time, facilitating adaptive control and remote diagnostics. SMC Corporation's OPC UA-enabled pneumatics cut unscheduled downtime 20-30 % in electronics assembly lines. Machine-learning algorithms now adjust pump displacement and working pressures dynamically, improving energy utilization by 36 % in hydrostatic transmissions. Hybrid electro-hydraulic actuation is gaining traction in collaborative robots and automated guided vehicles, enlarging addressable demand for the fluid power equipment market.
Cyclical Capital Expenditure in Heavy Industries
North American diversified industrial revenue at Parker Hannifin fell 5.8 % organically in Q2 2025 as transportation and off-highway customers delayed new hydraulic equipment orders. Construction machinery OEMs are stretching rebuild cycles amid higher interest rates and uncertain infrastructure outlays, dampening near-term fluid power component uptake. Similar caution is visible in mining and primary metal segments, both large consumers of high-pressure pumps and motors. These swings limit consistent growth for the fluid power equipment market until macro-investment sentiment stabilizes.
Other drivers and restraints analyzed in the detailed report include:
- Technical Improvements in Sealing and Material Science
- Growing Investments in Off-Highway Electrification
- Price Volatility of Raw Materials
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Hydraulic solutions accounted for 60.92% of 2025 revenue, underpinning the largest slice of the fluid power equipment market share thanks to unmatched power density in excavators, presses and drilling rigs. Vendors are pairing variable-displacement pumps with digital controllers, improving metering accuracy and lowering fuel burn. Pneumatics, although smaller, is set to register a 4.69% CAGR to 2031 on the strength of lightweight end-effectors in electronics assembly and life-science packaging. The fluid power equipment market size expansion in pneumatics is further supported by smart sensors that transmit cycle counts and leak-rate alerts to edge gateways. Hybrid architectures are also emerging: low-flow pneumatics handles positioning, while hydraulics delivers peak force, creating incremental revenue opportunities across both lines.
Continuous R&D in high-switch-frequency digital valves is narrowing performance gaps between the two technologies. Field tests show discrete-flow hydraulic circuits trimming energy losses 20 % relative to proportional control, an upgrade gaining favor in material-handling forklifts. On the pneumatic side, vacuum-ejector designs with integrated pressure feedback now reduce compressed-air consumption up to 50 %, cutting factory operating costs. Together these advances keep the fluid power equipment market on a modernization trajectory that balances traditional strengths with digital agility.
Pumps represented 27.12% of 2025 sales, affirming their role as the heart of every circuit and a cornerstone of the broader fluid power equipment market. Demand spans utility water management, steel mills and forestry harvesters. Electronic pressure compensation, bi-directional telematics and condition-monitoring probes all raise pump bill-of-materials content, enlarging supplier value capture. In contrast, accumulators and filters, while smaller today, are forecast to grow 5.52% annually to 2031. Their surge stems from energy-recovery mandates and stricter contamination codes in semiconductor fabs and food plants, respectively.
Filters are shifting toward high-separation microglass media that deliver lower differential pressure, prolonging element life and reducing motor load. Accumulator designs now incorporate bladder materials rated for 20,000 charge cycles, meeting duty profiles of hybrid cranes and agricultural sprayers. Margins in these categories trend above corporate averages, reinforcing why vendors allocate R&D aimed at total-system optimization and lifecycle monitoring. The mix shift positions the fluid power equipment market size for better profitability even as headline growth remains moderate.
Complete Report Scope:
- By Technology
- Hydraulic Equipment
- Pneumatic Equipment
- By Product Type
- Pumps
- Motors
- Valves
- Cylinders
- Accumulators and Filters
- By End-User Industry
- Construction
- Agriculture
- Material Handling and Logistics
- Oil and Gas
- Aerospace and Defense
- Machine Tools
- Food Processing and Packaging
- Other End-User Industries
- By Distribution Channel
- OEM
- Aftermarket
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- France
- United Kingdom
- Italy
- Spain
- Russia
- Rest of Europe
- Asia Pacific
- China
- Japan
- India
- South Korea
- Australia and New Zealand
- Southeast Asia
- Rest of Asia Pacific
- Middle East
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- North America
Geography Analysis
Asia Pacific accounted for a leading 34.10% of 2025 turnover, anchored by China's electronics clusters, India's highway build-out and Southeast Asia's packaging export hubs. Regional governments continue to promote industrial automation grants that favor both hydraulic presses and pneumatic pick-and-place systems, supporting consistent growth in the fluid power equipment market. China's accelerated shift to electric vehicles is stimulating demand for battery manufacturing conveyors and cooling pumps. India's Production-Linked Incentive schemes for mobile phone assembly call for dozens of new clean-room facilities, each equipped with hydrogen-tolerant pneumatic valves, further lifting volumes.
The Middle East is the fastest-growing territory, projected at a 5.44% CAGR through 2031. Saudi Arabia's Vision 2030 and the UAE's Operation 300 Bn strategies funnel investment into solar desalination, green hydrogen electrolysers and advanced logistics, all reliant on robust fluid power control. Harsh ambient temperatures demand specialty seals and high-thermal-stability fluids, creating premium niches for global component vendors. Turkey, acting as a bridge to European supply chains, is expanding automotive stamping capacity that employs high-tonnage hydraulic presses, propelling incremental orders.
North America and Europe display slower near-term momentum due to softer capital expenditure, yet they remain vital innovation hubs for the fluid power equipment market. Parker Hannifin's North American industrial sales slipped, but aerospace aftermarket demand and medical equipment orders offset part of the decline. The European transition to Tier 5 off-road standards is sparking retrofits of hydraulic excavators and agricultural sprayers with low-emission pumps, counterbalancing weaker new-machine builds. These mature regions will likely regain traction once macro uncertainty eases, aided by legislated energy-efficiency upgrades across brownfield factories.
- Bosch Rexroth AG
- Parker-Hannifin Corporation
- Danfoss A/S
- SMC Corporation
- Eaton Corporation plc
- Festo SE and Co. KG
- Kawasaki Heavy Industries Ltd.
- Hydac Verwaltungs GmbH
- HydraForce Inc.
- Emerson Electric Co.
- IMI plc (IMI Precision Engineering)
- Ingersoll Rand Inc.
- Flowserve Corporation
- Nachi-Fujikoshi Corp.
- Argo-Hytos Group AG
- Bucher Industries AG (Bucher Hydraulics)
- Camozzi Automation SpA
- Norgren Limited
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Energy Efficiency and Environmental Considerations
- 4.2.2 Advances in Industrial Automation
- 4.2.3 Technical Improvements in Sealing and Material Science
- 4.2.4 Growing Investments in Off-Highway Electrification
- 4.2.5 Rising Demand from Smart Manufacturing Facilities
- 4.2.6 Hydrogen-Ready Pneumatics for Clean-Room Operations
- 4.3 Market Restraints
- 4.3.1 Cyclical Capital Expenditure in Heavy Industries
- 4.3.2 Price Volatility of Raw Materials
- 4.3.3 Leakage-Driven Energy Losses in Hydraulic Systems
- 4.3.4 Supply Chain Fragmentation for Precision Components
- 4.4 Industry Ecosystem Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Industry Rivalry
- 4.8 Impact of Macroeconomic Factors
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Technology
- 5.1.1 Hydraulic Equipment
- 5.1.2 Pneumatic Equipment
- 5.2 By Product Type
- 5.2.1 Pumps
- 5.2.2 Motors
- 5.2.3 Valves
- 5.2.4 Cylinders
- 5.2.5 Accumulators and Filters
- 5.3 By End-User Industry
- 5.3.1 Construction
- 5.3.2 Agriculture
- 5.3.3 Material Handling and Logistics
- 5.3.4 Oil and Gas
- 5.3.5 Aerospace and Defense
- 5.3.6 Machine Tools
- 5.3.7 Food Processing and Packaging
- 5.3.8 Other End-User Industries
- 5.4 By Distribution Channel
- 5.4.1 OEM
- 5.4.2 Aftermarket
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 South America
- 5.5.2.1 Brazil
- 5.5.2.2 Argentina
- 5.5.2.3 Rest of South America
- 5.5.3 Europe
- 5.5.3.1 Germany
- 5.5.3.2 France
- 5.5.3.3 United Kingdom
- 5.5.3.4 Italy
- 5.5.3.5 Spain
- 5.5.3.6 Russia
- 5.5.3.7 Rest of Europe
- 5.5.4 Asia Pacific
- 5.5.4.1 China
- 5.5.4.2 Japan
- 5.5.4.3 India
- 5.5.4.4 South Korea
- 5.5.4.5 Australia and New Zealand
- 5.5.4.6 Southeast Asia
- 5.5.4.7 Rest of Asia Pacific
- 5.5.5 Middle East
- 5.5.5.1 Saudi Arabia
- 5.5.5.2 United Arab Emirates
- 5.5.5.3 Turkey
- 5.5.5.4 Rest of Middle East
- 5.5.6 Africa
- 5.5.6.1 South Africa
- 5.5.6.2 Egypt
- 5.5.6.3 Rest of Africa
- 5.5.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (Includes Global Level Overview, Market Level Overview, Core Segments, Financials as Available, Strategic Information, Market Rank/Share for Key Companies, Products and Services, and Recent Developments)
- 6.4.1 Bosch Rexroth AG
- 6.4.2 Parker-Hannifin Corporation
- 6.4.3 Danfoss A/S
- 6.4.4 SMC Corporation
- 6.4.5 Eaton Corporation plc
- 6.4.6 Festo SE and Co. KG
- 6.4.7 Kawasaki Heavy Industries Ltd.
- 6.4.8 Hydac Verwaltungs GmbH
- 6.4.9 HydraForce Inc.
- 6.4.10 Emerson Electric Co.
- 6.4.11 IMI plc (IMI Precision Engineering)
- 6.4.12 Ingersoll Rand Inc.
- 6.4.13 Flowserve Corporation
- 6.4.14 Nachi-Fujikoshi Corp.
- 6.4.15 Argo-Hytos Group AG
- 6.4.16 Bucher Industries AG (Bucher Hydraulics)
- 6.4.17 Camozzi Automation SpA
- 6.4.18 Norgren Limited
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

