PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2124747

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2124747
North America Shrink And Stretch Film - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the North America shrink and stretch film market size is expected to grow from USD 5.32 billion in 2025 to USD 5.52 billion in 2026 and is forecast to reach USD 6.61 billion by 2031 at 3.69% CAGR over 2026-2031.
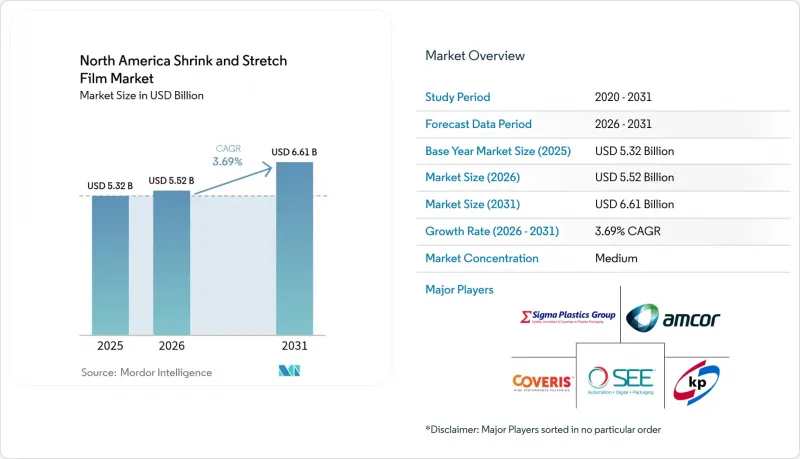
This report is Segmented by Product Type (Hoods, Wraps, Sleeve Labels, Bags and Pouches), Material (LDPE, LLDPE, PVC, PET, and More), End-Use Industry (Food and Beverage, Consumer Goods, Pharmaceutical and Healthcare, and More), Packaging Application (Pallet Unitization, Bundling and Multipack, and More), and Country. The Market Forecasts are Provided in Terms of Value (USD).
North America Shrink And Stretch Film Market Trends and Insights
E-Commerce Fulfillment Boom Raises Pallet-Wrap Usage
Robust online retail expansion continues to transform the North America shrink and stretch film market, with fulfillment campuses demanding machine-grade stretch films that deliver repeatable performance at 60-plus pallets per hour. Amazon's plan for 15 new U.S. and Canadian centers and Walmart's USD 4.2 billion logistics upgrade highlight how automated stretch hoods now outperform spiral wraps for mixed-SKU pallet loads. Converters able to fine-tune seven-layer formulations onsite win contracts by helping operators cut film waste and downtime. Load-stability requirements also favor puncture-resistant films that maintain clarity for barcode scanning. Regional film plants near Midwestern and Southwestern warehouse corridors shorten lead times and mitigate freight surcharges, strengthening competitive positions.
Growth of Processed and Frozen Foods Drives Retail Shrink Film
Accelerating demand for convenience meals sustained an 8.2% rise in U.S. frozen food sales during 2024, lifting orders for retail shrink sleeves that tolerate cold-chain temperature swings. Beverage bottlers likewise adopt tamper-evident bands to satisfy FDA guidance, pushing converters toward multilayer sleeves with perforated tear strips. Product-launch velocity compels labels to integrate wash-off inks, as seen in Klockner Pentaplast's SmartCycle sleeves that remain attached during PET reclamation. These developments reinforce the North America shrink and stretch film market's stability even amid sustainability scrutiny, because recyclable barrier structures now address retailer mandates without sacrificing shelf life.
Volatile Polyethylene and PVC Resin Prices
North American spot polyethylene values swung 40% during 2024 amid feedstock outages and shipping bottlenecks, squeezing converter margins that hinge on thin unit economics. PVC resin spiked 35% year-over-year, eroding the competitiveness of high-clarity shrink sleeves. Large vertically integrated players hedge inventory with forward contracts, but smaller converters struggle to pass through surcharges promptly, eroding working-capital positions. These unpredictable inputs slow capital spending on new extrusion lines, tempering near-term expansion of the North America shrink and stretch film market.
Other drivers and restraints analyzed in the detailed report include:
- Warehouse Automation Prefers Stretch Hoods for Load Stability
- Tamper-Evident Regulations in Pharma and Beverages
- Stringent Single-Use-Plastic Legislation in U.S. States and Canada
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Stretch wraps secured 51.35% of the North America shrink and stretch film market share in 2025, underscoring their entrenched use for pallet load containment in conventional warehouses. The North America shrink and stretch film market size tied to stretch wraps is forecast to edge forward at roughly 3.08% CAGR through 2031 as downgauging and automation sustain baseline demand. Parallelly, stretch hoods record a stronger 3.74% CAGR as robotic palletizers require uniform tension and film breathability. Sigma Plastics Group's 2024 purchase of Stalwart's stretch-film assets bolsters supply depth and signals strategic concentration around high-run SKUs. Sleeve labels and bags segments confront greater sustainability headwinds yet find respite in tamper-evident and recyclable PET-compatible innovations.
Adoption curves demonstrate that high-volume distributors justify hood capital expenditures once yearly pallet throughput exceeds 300,000. Hoods deliver superior puncture resistance that minimizes rewrap labor, although higher unit film cost restricts penetration among small to mid-sized shippers. Sleeve label buyers increasingly specify wash-off coatings that meet bottle-to-bottle PET guidelines, pushing converters toward solvent-free gravure inks. As state fees escalate, interest grows in compostable cellulosic shrink bags for specialty meat processors, adding differentiated avenues to the North America shrink and stretch film market.
LLDPE retained a 62.35% share during 2025 as its high elongation and tear strength suit machine wraps for 1-ton pallets. Recycled and bio-based resins, however, are advancing at a 3.99% CAGR, the fastest among material options, aided by Nova Chemicals securing FDA food-contact clearance for 35% PCR LLDPE blends. The North America shrink and stretch film market size attributable to PCR grades remains modest yet enjoys premium pricing that offsets throughput de-rates during extrusion.
PVC's optical clarity maintains relevance for high-shrink sleeve labels on contoured beverage containers, though its chlorine content draws regulatory scrutiny and hinders landfill diversion. PET shrink films anchor premium pharmaceuticals that demand scuff resistance and oxygen barrier, justifying their cost profile. The imminent PFAS phase-outs push research toward fluorine-free friction reducers, while post-industrial scrap recycling loops gain traction among integrated converters striving to meet 25% recycled-content pledges by 2027.
Complete Report Scope:
- By Product Type
- Hoods
- Wraps (Machine and Hand)
- Sleeve Labels
- Bags and Pouches
- By Material
- LDPE
- LLDPE
- PVC
- PET
- Recycled and Bio-based Resins
- By End-use Industry
- Food and Beverage
- Consumer Goods
- Pharmaceutical and Healthcare
- Industrial and Logistics
- E-commerce Fulfilment Centers
- By Packaging Application
- Pallet Unitization
- Bundling and Multipack
- Tamper-evident Sleeve Labeling
- Secondary Retail Packaging
- By Country
- United States
- Canada
- Mexico
List of Companies Covered in this Report:
- Sigma Plastics Group LLC
- Amcor Group GmbH
- Sealed Air Corporation
- Intertape Polymer Group Inc.
- Dow Inc.
- Taghleef Industries LLC
- Klockner Pentaplast Group
- Transcontinental Inc.
- Paragon Films Inc.
- AEP Industries Inc.
- Coveris Holdings S.A.
- Clysar LLC
- Winpak Ltd.
- Jindal Films Americas LLC
- Poly-America L.P.
- Revolution Company
- Charter Next Generation Inc.
- FlexSol Packaging Corp.
- Bollore Inc. (Bolphane USA)
- Hood Packaging Corporation
- Uflex Limited
- Bemis Company LLC
- Sigma Stretch Film Corp.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 E-commerce fulfilment boom raises pallet-wrap usage
- 4.2.2 Growth of processed and frozen foods drives retail shrink film
- 4.2.3 Warehouse automation prefers stretch hoods for load stability
- 4.2.4 Tamper-evident regulations in pharma and beverages
- 4.2.5 Surge in Mexico near-shoring boosting cross-border pallet traffic
- 4.2.6 Cold-chain cannabis logistics adopting downgauged stretch film
- 4.3 Market Restraints
- 4.3.1 Volatile polyethylene and PVC resin prices
- 4.3.2 Stringent single-use-plastic legislation in U.S. states and Canada
- 4.3.3 Post-consumer recycled (PCR) supply shortage limits film output
- 4.3.4 Patent litigation slowing seven-layer film commercialisation
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Bargaining Power of Buyers
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
- 4.8 Shrink and Stretch Film Pricing Analysis
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product Type
- 5.1.1 Hoods
- 5.1.2 Wraps (Machine and Hand)
- 5.1.3 Sleeve Labels
- 5.1.4 Bags and Pouches
- 5.2 By Material
- 5.2.1 LDPE
- 5.2.2 LLDPE
- 5.2.3 PVC
- 5.2.4 PET
- 5.2.5 Recycled and Bio-based Resins
- 5.3 By End-use Industry
- 5.3.1 Food and Beverage
- 5.3.2 Consumer Goods
- 5.3.3 Pharmaceutical and Healthcare
- 5.3.4 Industrial and Logistics
- 5.3.5 E-commerce Fulfilment Centers
- 5.4 By Packaging Application
- 5.4.1 Pallet Unitization
- 5.4.2 Bundling and Multipack
- 5.4.3 Tamper-evident Sleeve Labeling
- 5.4.4 Secondary Retail Packaging
- 5.5 By Country
- 5.5.1 United States
- 5.5.2 Canada
- 5.5.3 Mexico
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)
- 6.4.1 Sigma Plastics Group LLC
- 6.4.2 Amcor Group GmbH
- 6.4.3 Sealed Air Corporation
- 6.4.4 Intertape Polymer Group Inc.
- 6.4.5 Dow Inc.
- 6.4.6 Taghleef Industries LLC
- 6.4.7 Klockner Pentaplast Group
- 6.4.8 Transcontinental Inc.
- 6.4.9 Paragon Films Inc.
- 6.4.10 AEP Industries Inc.
- 6.4.11 Coveris Holdings S.A.
- 6.4.12 Clysar LLC
- 6.4.13 Winpak Ltd.
- 6.4.14 Jindal Films Americas LLC
- 6.4.15 Poly-America L.P.
- 6.4.16 Revolution Company
- 6.4.17 Charter Next Generation Inc.
- 6.4.18 FlexSol Packaging Corp.
- 6.4.19 Bollore Inc. (Bolphane USA)
- 6.4.20 Hood Packaging Corporation
- 6.4.21 Uflex Limited
- 6.4.22 Bemis Company LLC
- 6.4.23 Sigma Stretch Film Corp.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment

