PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2124779

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2124779
Fertility Supplement - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the fertility supplement market size was valued at USD 2.70 billion in 2025 and estimated to grow from USD 2.88 billion in 2026 to reach USD 3.94 billion by 2031, at a CAGR of 6.49% during the forecast period (2026-2031).
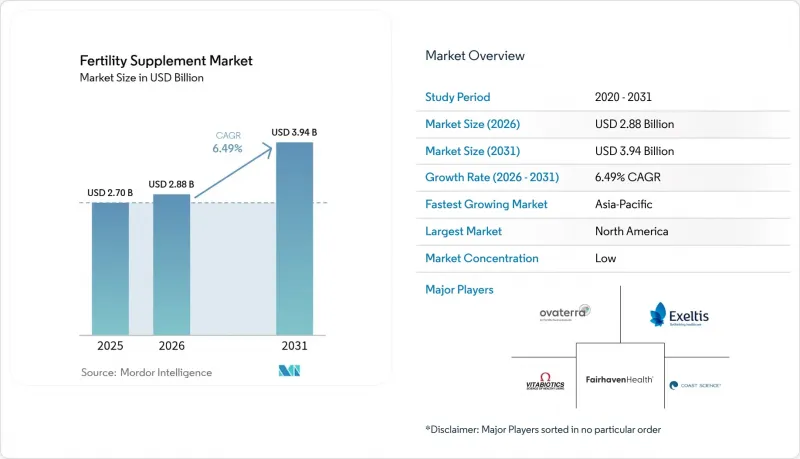
This report is Segmented by Ingredient (Natural Ingredients, and More), Form (Capsules, Tablets, and More), Consumer (Female-Specific Supplements and Male-Specific Supplements), Distribution Channel (Retail Pharmacy, and More), Geography (North America, Europe, Asia-Pacific, The Middle East and Africa, and South America). The Market Forecasts are Provided in Terms of Value (USD).
Global Fertility Supplement Market Trends and Insights
Rising Global Infertility Incidence
Roughly 8-12% of couples now struggle with male-factor infertility, and secondary infertility is climbing sharply across Asia-Pacific, with the Philippines reporting some of the highest regional rates. Contributing factors-later childbearing, sedentary lifestyles and environmental stressors-have moved fertility supplements from discretionary status to perceived healthcare essentials. Evidence for nutrients such as myo-inositol and selenium in managing polycystic ovary syndrome (PCOS) underpins long-range demand, particularly for women who postpone pregnancy into their thirties. These structural epidemiological shifts establish a durable growth platform for the fertility supplements market.
Growing Awareness of Preconception Nutrition
Survey work across five high-income countries shows the United States leading on pre-conception knowledge, yet uptake of recommended micronutrient regimens remains inconsistent. Physician guidance is the most trusted information source, elevating clinical backing as a sales catalyst. Research linking optimal copper, manganese and vitamin B12 levels during pregnancy to lower mid-life blood-pressure risk widens the conversation from immediate conception to lifelong health outcomes. By embedding these insights, brands are positioning fertility supplements as part of holistic prenatal wellness rather than short-term fixes.
Stringent Regulatory Oversight on Supplement Claims
The U.S. FDA now mandates a 75-day pre-market notification for novel dietary ingredients, including substantial toxicology data, before commercialization. California's pending SB 646 will require heavy-metal testing for prenatal vitamins, and advocacy bodies such as the Center for Science in the Public Interest have openly challenged unsubstantiated fertility claims. Compliance outlays climb fastest for smaller firms, effectively raising entry barriers yet gradually building consumer confidence in the fertility supplements market.
Other drivers and restraints analyzed in the detailed report include:
- Expansion of Assisted Reproductive Technologies
- Increasing Disposable Income and Healthcare Spending
- Limited Clinical Evidence Supporting Efficacy
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Natural ingredients accounted for 54.22% of the fertility supplements market in 2025, reflecting consumer trust in botanicals such as maca, ashwagandha and tribul us. Vitamins and minerals with long clinical pedigrees-folic acid, zinc and selenium-continue to anchor many formulations. Antioxidants like coenzyme Q10 and omega-3 fatty acids are increasingly positioned as gamete-protective agents against oxidative stress. Synthetic bioactives still meet hesitation, but science-driven messaging around higher absorption and genetic suitability is helping to bridge perceptions.
The blend segment is forecast to log the fastest 8.39% CAGR through 2031, marrying botanical familiarity with synthetic precision. Brands are styling these hybrids as "clinically complete" solutions, justifying premium price tags through comprehensive label claims. For example, Quatrefolic's superior absorption profile is being paired with whole-herb inositol to meet both female-fertility and MTHFR-related needs. This positioning aligns with rising willingness in North America and Asia-Pacific to invest in condition-specific micronutrient stacks, a critical propellant for the fertility supplements market.
Capsules retained a 37.76% revenue share in 2025, appreciated for dose precision and easy inclusion of multi-ingredient matrices. Softgels dominate fat-soluble nutrients such as omega-3 DHA and ubiquinol, whereas tablets offer manufacturing economies for mass-market SKUs. Powders and ready-mix sachets fulfill niche preferences for additive-free or customizable dosing, yet palatability hurdles limit their mainstream uptake.
Gummies are projected to progress at a 9.12% CAGR to 2031-a trajectory mirrored in several adjacent supplement categories-as younger consumers equate health maintenance with snack-like convenience. Formulators address thermal sensitivity and sugar-content warnings by deploying pectin bases and lower-glycemic sweeteners. Should these technological refinements hold, gummies will carve out a larger slice of the fertility supplements market, especially in e-pharmacy baskets.
Complete Report Scope:
- By Ingredient
- Natural Ingredients
- Herbal Extracts (Maca, Ashwagandha, Tribulus)
- Vitamins & Minerals (Folic Acid, Zinc, Selenium)
- Antioxidants (CoQ10, Omega-3, Lycopene)
- Synthetic Ingredients
- Blend of Natural & Synthetic
- Natural Ingredients
- By Form
- Capsules
- Tablets
- Softgels
- Gummies
- Powders
- Other Forms (Liquids, Sprays)
- By Consumer
- Female-Specific Supplements
- Male-Specific Supplements
- By Distribution Channel
- Retail Pharmacy
- E-pharmacy
- Other Distribution Channels
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America controlled 35.41% of global revenues in 2025, buoyed by the highest employer penetration of fertility benefits and a mature supplement culture that accepts premium pricing for clinically backed formulations. The United States' pre-conception knowledge advantage partially offsets patchy supplement adherence, creating room for professional-only lines that double as prescription adjuncts. Regulatory rigor is also intensifying: the FDA's 75-day new-ingredient rule is weeding out under-substantiated SKUs but simultaneously consolidating consumer confidence. This confluence of favorable coverage, medical endorsement and consumer trust solidifies North America's role as the anchor market for fertility supplements.
Asia-Pacific is the fastest-growing theatre, anticipated to log a 7.48% CAGR. Rising infertility-exacerbated by urban lifestyles, postponement of parenting and mounting PCOS incidence-has magnified demand in China, India and the Philippines. The fertility supplements market size for Asia-Pacific is projected to eclipse USD 1.49 billion by 2031, capturing more than one-third of incremental global dollars. Multinationals are responding through local acquisitions-Barentz's purchase of China's Fengli Group and Nestle's expanded women's-health platform-while domestic entrants leverage herbal heritages to differentiate in an ingredient-conscious consumer base.
Europe, grounded in stringent health-claim regulation under EFSA, registers steady mid-single-digit growth as brands lead with documented benefits and transparent labelling. South America and the Middle East & Africa are still nascent, yet incremental rises in disposable income and e-commerce penetration are nurturing early adoption. Currency fluctuations and fragmented distribution keep short-term growth tempered, but escalating ART uptake and government-sponsored maternal-health programs point to medium-term potential. Consequently, the fertility supplements market maintains a genuinely global profile, albeit shaped by region-specific regulatory and cultural determinants.
- Vitabiotics
- Fairhaven Health
- Exeltis USA
- Fertility Nutraceuticals
- Coast Science
- LENUS Pharma GesmbH
- Active Bio Life Science
- Orthomol Pharmazeutische Vertriebs
- Zenith Nutrition
- Bionova
- Theralogix
- Eu Natural
- NutraBlast
- Nestle (Nature's Bounty)
- Jamieson Wellness
- Nutrafol
- OLLY Nutrition
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising Global Infertility Incidence
- 4.2.2 Growing Awareness of Preconception Nutrition
- 4.2.3 Expansion of Assisted Reproductive Technologies
- 4.2.4 Increasing Disposable Income and Healthcare Spending
- 4.2.5 Product Innovations With Evidence-Based Ingredients
- 4.2.6 Proliferation of Online And Retail Distribution Channels
- 4.3 Market Restraints
- 4.3.1 Stringent Regulatory Oversight on Supplement Claims
- 4.3.2 Limited Clinical Evidence Supporting Efficacy
- 4.3.3 High Price Sensitivity Among Consumers
- 4.3.4 Competition From Alternative Treatment Modalities
- 4.4 Regulatory Landscape
- 4.5 Porter's Five Forces
- 4.5.1 Threat of New Entrants
- 4.5.2 Bargaining Power of Buyers
- 4.5.3 Bargaining Power of Suppliers
- 4.5.4 Threat of Substitutes
- 4.5.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Ingredient
- 5.1.1 Natural Ingredients
- 5.1.1.1 Herbal Extracts (Maca, Ashwagandha, Tribulus)
- 5.1.1.2 Vitamins & Minerals (Folic Acid, Zinc, Selenium)
- 5.1.1.3 Antioxidants (CoQ10, Omega-3, Lycopene)
- 5.1.2 Synthetic Ingredients
- 5.1.3 Blend of Natural & Synthetic
- 5.1.1 Natural Ingredients
- 5.2 By Form
- 5.2.1 Capsules
- 5.2.2 Tablets
- 5.2.3 Softgels
- 5.2.4 Gummies
- 5.2.5 Powders
- 5.2.6 Other Forms (Liquids, Sprays)
- 5.3 By Consumer
- 5.3.1 Female-Specific Supplements
- 5.3.2 Male-Specific Supplements
- 5.4 By Distribution Channel
- 5.4.1 Retail Pharmacy
- 5.4.2 E-pharmacy
- 5.4.3 Other Distribution Channels
- 5.5 Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East & Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East & Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global level Overview, Market level overview, Core Business Segments, Financials, Headcount, Key Information, Market Rank, Market Share, Products and Services, and analysis of Recent Developments)
- 6.3.1 Vitabiotics Ltd
- 6.3.2 Fairhaven Health
- 6.3.3 Exeltis USA Inc.
- 6.3.4 Fertility Nutraceuticals LLC (Ovaterra)
- 6.3.5 Coast Science
- 6.3.6 LENUS Pharma GesmbH
- 6.3.7 Active Bio Life Science GmbH
- 6.3.8 Orthomol Pharmazeutische Vertriebs GmbH
- 6.3.9 Zenith Nutrition
- 6.3.10 Bionova
- 6.3.11 Theralogix
- 6.3.12 Eu Natural
- 6.3.13 NutraBlast
- 6.3.14 Nestle (Nature's Bounty)
- 6.3.15 Jamieson Wellness
- 6.3.16 Nutrafol
- 6.3.17 OLLY Nutrition
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-need Assessment

