PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2124797

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2124797
Insufflation Devices - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the insufflation devices market size is expected to grow from USD 3.10 billion in 2025 to USD 3.28 billion in 2026 and is forecast to reach USD 4.37 billion by 2031 at 5.88% CAGR over 2026-2031.
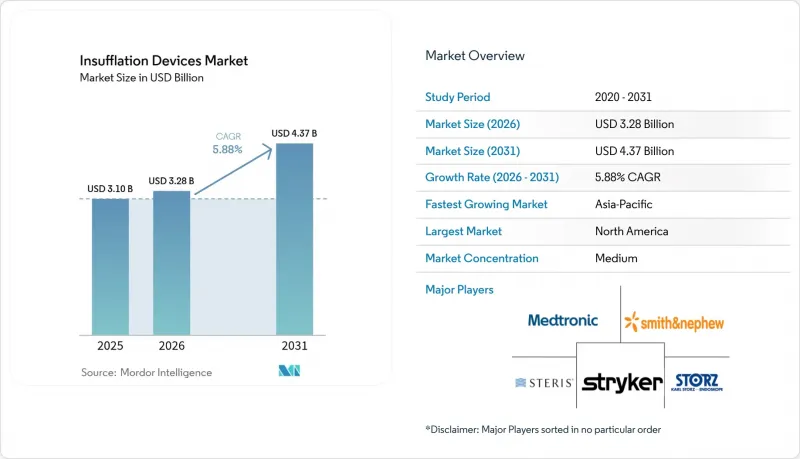
This report is Segmented by Product Type (Insufflation Systems and Disposable Tubing & Accessories), Application (Laparoscopic Surgery, and More), End User (Hospitals, Ambulatory Surgical Centers, Specialty Clinics, and Other End Users), and Geography (North America, Europe, Asia-Pacific, Middle East & Africa, and South America). The Market Forecasts are Provided in Terms of Value (USD).
Global Insufflation Devices Market Trends and Insights
Growing Adoption of Minimally Invasive Surgery
Minimally invasive surgery accounted for 65% of eligible abdominal cases in the United States by 2024 and shows uneven uptake elsewhere, producing sizable white spaces for vendors to target surgeon training and bundled leasing solutions. Sleeve gastrectomy led bariatric procedures, with robotic assistance rising to 30% by 2024. Near-complete laparoscopic conversion rates for cholecystectomy in OECD markets demonstrate how standardization cements console utilization, whereas penetration below 40% in parts of Southeast Asia and Sub-Saharan Africa reflects capital and training gaps. Regulatory burden remains light because 510(k) reviews emphasize safety over clinical efficacy, leaving reimbursement as the primary driver of adoption. Bundled payment policies that reward shorter stays favor low-pressure pneumoperitoneum management and therefore stimulate purchases of advanced consoles that sustain pressures below 10 mmHg.
Continuous Technological Advancements in Insufflation Platforms
Innovation is migrating from stand-alone hardware toward software-defined modules that interoperate with anesthesia workstations and navigation systems. CONMED's AirSeal iFS, now installed in 5,857 facilities and used in more than 8 million procedures, exemplifies continuous smoke evacuation and valve-free pressure control that reduces postoperative shoulder pain by 34%. AI-enabled algorithms predict phase transitions and preempt pressure spikes, though Software-as-a-Medical-Device clearances add 18 months to development cycles. ISO 13485 compliance remains entry-level, but competitive advantage now hinges on HL7 FHIR-ready data output that feeds OR dashboards. Vendors that master connectivity gain a service revenue stream from predictive maintenance and analytics subscriptions.
Clinical Concerns Over Carbon Dioxide-Related Complications
Prolonged CO2 insufflation can elevate arterial PCO2 by up to 25%, producing respiratory acidosis that complicates anesthesia and extends recovery. Meta-analysis published in 2024 linked pressures above 12 mmHg for more than 90 minutes to pulmonary complications in up to 20% of cases. Although alternatives such as helium remain unapproved, clinician caution slows uptake of high-flow devices unless they include closed-loop pressure caps. Subcutaneous emphysema incidence of 0.5-2% further heightens scrutiny in bundled-payment environments where hospitals absorb readmission costs. Absent mandatory clinical trial data in 510(k) submissions, surgeons rely on peer-reviewed studies and society guidelines, forcing manufacturers to generate post-market evidence to counter safety concerns.
Other drivers and restraints analyzed in the detailed report include:
- Surge in Bariatric and Gynecologic Procedure Volumes
- Integration with Digital Operating Room Ecosystems
- High Upfront Investment for Next-Generation Console Systems
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Disposable tubing & accessories accounted for 27.88% revenue in 2025 and are projected to expand at a 7.65% CAGR through 2031. The insufflation devices market for disposables is poised to grow steadily as infection-prevention regulations tilt preference toward single-use components. Proprietary filter and tubing sets priced between USD 15 and USD 45 per procedure deliver gross margins above 60%, encouraging vendors to discount consoles in exchange for consumable contracts. A 2024 U.S. hospital survey revealed that 78% of infection-control committees now require single-use tubing, a 16-percentage-point increase in two years. Vendors exploit this trend by bundling disposables with software licenses that monitor tubing expiration dates, enhancing supply-chain compliance and reducing waste.
Conversely, console revenue grows modestly at 3-4% as the installed base ages across seven-to-ten-year replacement cycles. The insufflation devices market share held by Insufflation Systems remains dominant at 72.12% in 2025, yet pricing headwinds and embedded integration within robotic platforms erode standalone demand. Manufacturers, therefore, position consoles as gateways to higher-margin consumable streams, emulating razor-and-blade economics. Facilities with high laparoscopic case volumes justify console upgrades when predictive maintenance and closed-loop pressure modulation cut unplanned downtime and postoperative complications, supporting procurement under value-based payment models.
Complete Report Scope:
- By Product Type
- Insufflation Systems
- Disposable Tubing & Accessories
- By Application
- Laparoscopic Surgery
- Bariatric Surgery
- Gynecological Surgery
- Cardiac & Thoracic Surgery
- Urological & Renal Surgery
- Pediatric Surgery
- Other Applications
- By End User
- Hospitals (Tier I/II/III)
- Ambulatory Surgical Centers
- Specialty Clinics
- Other End Users
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East & Africa
- GCC
- South Africa
- Rest of Middle East & Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
North America led the insufflation devices market with 42.54% revenue share in 2025, translating to an insufflation devices market size of about USD 1.38 billion that year. Robust robotic-surgery penetration exceeding 50% in prostatectomy and hysterectomy, Medicare payment parity for bariatric procedures, and early deployment of digital OR ecosystems sustain mid-single-digit growth in console replacements. The United States drives the region, performing 280,000 bariatric surgeries in 2024, a volume that demands extended insufflation times and repeat filter changes. Canada's CAD 120 million (USD 88 million) surgical modernization outlay in 2024-2025 funded insufflator upgrades in 45 hospitals, while Mexico's 1.2 million inbound medical tourists in 2024 spurred private-hospital investment in premium equipment. Vendor strategies center on bundled equipment-consumable deals that lock high-volume U.S. centers into proprietary tubing, while offering Mexico's price-sensitive clinics flexible leasing options. FDA cybersecurity rules, effective in 2025, add compliance costs yet also raise switching barriers, cementing incumbent share.
Asia-Pacific is forecast to grow at a 6.54% CAGR through 2031, the fastest regional pace in the insufflation devices market. China logged 18.5 million laparoscopic procedures in 2024, up 9.2% year on year, after the National Health Commission financed 400 new minimally invasive surgery suites. India's Ayushman Bharat insurance expansion unlocked district-hospital procurements, though domestic brands undercut multinationals by 40-50% on console price, fracturing share. Japan counted 450 da Vinci installations by 2025, but tight reimbursement caps limit procedure growth, curbing console refresh cycles. Australia's private hospitals, which are responsible for 60% of elective surgeries, adopt compact, battery-powered consoles that align with ambulatory workflows. Regional distributors play an outsized role, especially in Indonesia and the Philippines, where fragmented hospital networks favor vendors able to offer local service and financing packages. The insufflation devices industry faces localization mandates in China that require joint manufacturing, pushing global OEMs toward technology-transfer partnerships to secure tenders.
Europe accounts for roughly 30% of global revenue, yet EU Medical Device Regulation stringency lengthens certification timelines, consolidating share with Medtronic, Karl Storz, and Olympus. Germany's 1.8 million laparoscopic cases in 2024 generate steady filter demand, while hospital DRG reimbursement tables reward low complication rates that precision-flow consoles can document. The United Kingdom invested GBP 200 million (USD 255 million) in surgical equipment upgrades during 2024-2025, though 30% of planned installs face delivery delays from supply-chain bottlenecks. France's target of 70% ambulatory surgery by 2025 lifts sales of space-saving consoles with mobile carts. Gulf Cooperation Council countries, led by the UAE and Saudi Arabia, import premium systems for medical-tourism hubs that promise surgeons integrated smoke evacuation and cybersecurity compliance. South America and Africa trail in absolute volume; Brazil's pilot laparoscopic programs under the SUS scheme and Nigeria's private-hospital corridor in Lagos represent beachheads for vendors prepared to bundle training with equipment financing.
- Alesi Surgical Ltd.
- Applied Medical Resources
- B. Braun
- Conmed
- Genicon
- Hoya Corp. (Pentax Medical)
- Johnson & Johnson
- Karl Storz
- Lexion Medical
- Medtronic
- Northgate Technologies Inc.
- Olympus
- Richard Wolf
- Smiths Group
- STERIS
- Stryker
- Teleflex
- W.O.M. World Of Medicine GmbH
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Growing Adoption of Minimally Invasive Surgery
- 4.2.2 Continuous Technological Advancements in Insufflation Platforms
- 4.2.3 Surge in Bariatric and Gynecologic Procedure Volumes
- 4.2.4 Expansion of Ambulatory Surgery Infrastructure
- 4.2.5 Integration with Digital Operating Room Ecosystems
- 4.2.6 Shift Toward Disposable Insufflation Consumables
- 4.3 Market Restraints
- 4.3.1 Clinical Concerns Over Carbon Dioxide-Related Complications
- 4.3.2 High Upfront Investment for Next-Generation Console Systems
- 4.3.3 Tightening Regulations on Medical-Grade Carbon Dioxide Supply
- 4.3.4 Emerging Cybersecurity Compliance Burden for Connected Devices
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat Of New Entrants
- 4.7.2 Bargaining Power Of Buyers
- 4.7.3 Bargaining Power Of Suppliers
- 4.7.4 Threat Of Substitutes
- 4.7.5 Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Product Type
- 5.1.1 Insufflation Systems
- 5.1.2 Disposable Tubing & Accessories
- 5.2 By Application
- 5.2.1 Laparoscopic Surgery
- 5.2.2 Bariatric Surgery
- 5.2.3 Gynecological Surgery
- 5.2.4 Cardiac & Thoracic Surgery
- 5.2.5 Urological & Renal Surgery
- 5.2.6 Pediatric Surgery
- 5.2.7 Other Applications
- 5.3 By End User
- 5.3.1 Hospitals (Tier I/II/III)
- 5.3.2 Ambulatory Surgical Centers
- 5.3.3 Specialty Clinics
- 5.3.4 Other End Users
- 5.4 Geography
- 5.4.1 North America
- 5.4.1.1 United States
- 5.4.1.2 Canada
- 5.4.1.3 Mexico
- 5.4.2 Europe
- 5.4.2.1 Germany
- 5.4.2.2 United Kingdom
- 5.4.2.3 France
- 5.4.2.4 Italy
- 5.4.2.5 Spain
- 5.4.2.6 Rest of Europe
- 5.4.3 Asia-Pacific
- 5.4.3.1 China
- 5.4.3.2 Japan
- 5.4.3.3 India
- 5.4.3.4 Australia
- 5.4.3.5 South Korea
- 5.4.3.6 Rest of Asia-Pacific
- 5.4.4 Middle East & Africa
- 5.4.4.1 GCC
- 5.4.4.2 South Africa
- 5.4.4.3 Rest of Middle East & Africa
- 5.4.5 South America
- 5.4.5.1 Brazil
- 5.4.5.2 Argentina
- 5.4.5.3 Rest of South America
- 5.4.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (Includes Global-Level Overview, Market-Level Overview, Core Segments, Financials As Available, Strategic Information, Market Rank/Share For Key Companies, Products & Services, And Recent Developments)
- 6.3.1 Alesi Surgical Ltd.
- 6.3.2 Applied Medical Resources
- 6.3.3 B. Braun Melsungen AG
- 6.3.4 CONMED Corporation
- 6.3.5 Genicon Inc.
- 6.3.6 Hoya Corp. (Pentax Medical)
- 6.3.7 Johnson & Johnson (Ethicon)
- 6.3.8 Karl Storz SE & Co. KG
- 6.3.9 Lexion Medical
- 6.3.10 Medtronic plc
- 6.3.11 Northgate Technologies Inc.
- 6.3.12 Olympus Corporation
- 6.3.13 Richard Wolf GmbH
- 6.3.14 Smith & Nephew plc
- 6.3.15 STERIS plc
- 6.3.16 Stryker Corporation
- 6.3.17 Teleflex Incorporated
- 6.3.18 W.O.M. World Of Medicine GmbH
7 Market Opportunities & Future Outlook
- 7.1 White-Space & Unmet-Need Assessment

