PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2124820

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2124820
Digital Signal Processor - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the digital signal processor market size is expected to grow from USD 2.69 billion in 2025 to USD 2.77 billion in 2026 and is forecast to reach USD 3.23 billion by 2031 at 3.10% CAGR over 2026-2031.
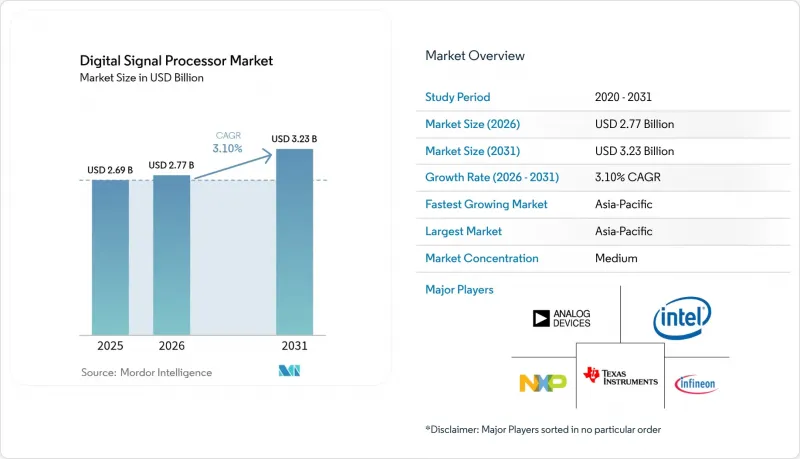
This report is Segmented by Core (Single-Core, and More), Product Type (General-Purpose Stand-Alone DSPs, and More), Architecture (Single Instruction Multiple Data, Very-Long-Instruction-Word, and More), Numeric Format (Fixed-Point, and More), End-User Industry (Communication, Automotive, Consumer Electronics, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Digital Signal Processor Market Trends and Insights
Proliferation of 5G Open-RAN Deployments in Asia
Open RAN architectures separate hardware and software functions, replacing proprietary baseband cards with programmable DSP platforms that can be retargeted in software. Operators in China, Japan, and South Korea are using these open stacks to trim vendor lock-in and speed feature updates. Testbeds combining NVIDIA ARC GPUs with high-performance DSP cores have exceeded 500 Mbps downlink under multi-user loads. This performance proof drives a procurement wave for multicore, floating-point-capable DSPs that execute beam-forming, channel estimation, and fronthaul compression in real time. The resulting pull-through effect is lifting orders for both merchant silicon and licensable DSP IP in Asia-Pacific and secondary deployments in North America.
Automotive ADAS Tier-1 Designs Migrating from MCU to DSP-centric SoCs
As camera, radar, and LiDAR counts rise per vehicle, microcontrollers lack the throughput to perform real-time sensor fusion. Tier-1 suppliers are therefore shifting to heterogeneous SoCs combining multi-core DSP engines with AI accelerators. AMD's Zynq UltraScale+ XA MPSoC shows how a tightly coupled DSP fabric processes radar chirps while adjacent AI engines classify objects, all inside a single safety-certified package. The automotive supply chain in Europe and East Asia is committing design wins through 2027, anchoring double-digit unit growth even as average selling prices drift lower.
Supply-chain Volatility in Advanced Node (<= 7 nm) Foundries
A limited pool of ultra-modern fabs in Taiwan and South Korea faces periodic geopolitical and logistics disruptions. When capacity tightens, DSP lead-times stretch beyond 40 weeks, pushing designers to retape-out on mature processes that meet neither power nor performance targets. Chipmakers with multi-foundry strategies and adaptable physical-design kits remain better insulated than rivals locked to single-source partnerships.
Other drivers and restraints analyzed in the detailed report include:
- AI-enhanced Audio & Voice Processing in Hearables and Smart Speakers
- Adoption of Software-Defined Radar in Aerospace & Defense
- Integration Trade-offs Between Fixed- and Floating-Point Precision in Battery-Powered Devices
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Multi-core devices generated 64.30% of 2025 revenue, equivalent to a USD 1.73 billion slice of the digital signal processor market size, underscoring their essential role in 5G baseband, automotive radar, and industrial vision. The digital signal processor market favors these parts because task-level parallelism maps naturally to multiple homogeneous cores, allowing deterministic latency under real-time constraints. Texas Instruments' C66x family demonstrates how eight fixed-/floating-point cores harness a unified Multicore Navigator fabric to eliminate copy overhead. The configuration headroom supports product-line variants spanning medical imaging, motor control, and SATCOM terminals.
Single-core and dual-core options survive in deeply embedded, price-sensitive end-nodes such as smart meters, while heterogeneous multi-core SoCs that blend DSP, CPU, and AI accelerators are gaining traction. Sustained 3.64% CAGR through 2031 keeps the multi-core slice of the digital signal processor market expanding faster than overall industry revenue. As open-source toolchains mature, multicore programming burdens fall, reinforcing supplier roadmaps that prioritize scalable tile-based fabrics, scratchpad memory hierarchies, and inter-core message passing.
Application-specific DSPs captured 47.60% of revenue in 2025, or USD 1.28 billion of the digital signal processor market size, because tightly focused instruction sets and accelerator blocks deliver watt-efficient performance in smartphones, base stations, and infotainment head units. Their growth aligns with OEM demands for BOM savings and board-space reductions. Qualcomm's modem-integrated DSP blocks and Analog Devices' RF-optimized cores exemplify this fit-for-purpose approach.
The fastest expansion, however, comes from licensable embedded DSP IP inserted into wider SoC projects. At a 4.02% CAGR, this vector raises the total addressable slice for EDA vendors and soft-IP houses. General-purpose discrete DSPs now orient toward military, aerospace, and laboratory instrumentation niches that value long product lifecycles. FPGA-based hybrids fill customization gaps where mid-volume customers need reconfigurability without ASIC risk.
Complete Report Scope:
- By Core
- Single-core
- Dual-core
- Multi-core
- By Product Type
- General-purpose Stand-alone DSPs
- Application-specific DSP (ASSP/ASIP)
- Embedded DSP IP Cores
- FPGA/SoC-based Hybrid DSPs
- By Architecture
- SIMD (Single Instruction Multiple Data)
- VLIW (Very-long-instruction-word)
- SIMT/Vector DSPs
- MLIW and Novel Heterogeneous Designs
- By Numeric Format
- Fixed-point
- Floating-point
- Mixed/Adaptive Precision
- By End-user Industry
- Communication
- Cellular Infrastructure (4G/5G, Open-RAN)
- Data Center and Cloud Edge
- VoIP and IP Video
- Automotive
- ADAS and Autonomous Driving
- In-vehicle Infotainment
- Consumer Electronics
- Smartphones and Tablets
- Hearables/Wearables
- Smart TVs and STBs
- Industrial
- Motor Control and Drives
- Machine Vision and Robotics
- Smart Grid and Energy
- Aerospace and Defense
- Radar and EW Systems
- Satellite and Space Electronics
- Healthcare
- Medical Imaging
- Patient Monitoring and Diagnostics
- Communication
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- South Korea
- India
- South East Asia
- Australia
- Rest of Asia-Pacific
- South America
- Brazil
- Rest of South America
- Middle East and Africa
- Middle East
- United Arab Emirates
- Saudi Arabia
- Rest of Middle East
- Africa
- South Africa
- Rest of Africa
- Middle East
- North America
Geography Analysis
Asia-Pacific generated 48.20% of worldwide revenue in 2025, just under half of the global digital signal processor market. China alone drives more than one quarter of wafer demand as its telecom operators build ultra-dense 5G grids and EV makers load vehicles with radar and infotainment processors. South Korea and Japan add further pull through their advanced memory, sensor, and automotive supply chains. A 3.74% CAGR keeps the region at the top of the growth league, and its installed fab capacity secures a supply advantage when advanced-node allocations tighten.
North America ranks second in both revenue and R&D depth. Silicon Valley start-ups and Austin-based incumbents push leading-edge multicore architectures and neural-DSP hybrids, while US defense projects guarantee a steady market for rad-hard floating-point parts. Federal incentives under the CHIPS and Science Act catalyze domestic fab expansions scheduled to come online by 2027, promising to ease node scarcity for local DSP houses.
Europe completes the triad with robust demand from German and French automakers and a growing cohort of machine-vision integrators. Regional initiatives such as IPCEI Micro-electronics support pilot lines for 12-in wafers, narrowing the production gap with Asia. Meanwhile, South America plus the Middle East & Africa contribute an emerging tail, largely tied to telecom infrastructure roll-outs and satellite broadband gateways that rely on high-throughput DSP-based modems.
- Texas Instruments Inc.
- Analog Devices Inc.
- Qualcomm Technologies Inc.
- Intel Corporation
- NXP Semiconductors N.V.
- STMicroelectronics N.V.
- Infineon Technologies AG
- Renesas Electronics Corp.
- Xilinx Inc. (AMD)
- Broadcom Inc.
- Samsung Electronics Co. Ltd.
- Toshiba Corp.
- Cirrus Logic Inc.
- MediaTek Inc.
- HiSilicon Technologies Co. Ltd.
- Marvell Technology Inc.
- ARM Ltd. (DSP IP)
- CEVA Inc.
- Cadence Design Systems (Tensilica DSP)
- Synopsys Inc. (ARC DSP)
- ON Semiconductor Corp.
- Silicon Labs Inc.
- Realtek Semiconductor Corp.
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Proliferation of 5G Open-RAN Deployments in Asia
- 4.2.2 Automotive ADAS Tier-1 Designs Migrating from MCU to DSP-centric SoCs
- 4.2.3 AI-enhanced Audio and Voice Processing in Hearables and Smart Speakers
- 4.2.4 Adoption of Software-Defined Radar in Aerospace and Defense
- 4.2.5 Edge-based Industrial Machine Vision for Quality 4.0 in Europe
- 4.2.6 Cloud-native Radio Access Networks Requiring High-throughput Baseband DSPs
- 4.3 Market Restraints
- 4.3.1 Supply-chain Volatility in Advanced Node (?7 nm) Foundries
- 4.3.2 Integration Trade-offs Between Fixed- and Floating-Point Precision in Battery-Powered Devices
- 4.3.3 Escalating Royalty Costs for Licensable DSP IP Cores
- 4.3.4 Global Cyber-export Controls Limiting DSP Shipments to Select Regions
- 4.4 Industry Ecosystem Analysis
- 4.5 Technological Outlook
- 4.6 Porter's Five Forces Analysis
- 4.6.1 Bargaining Power of Suppliers
- 4.6.2 Bargaining Power of Buyers
- 4.6.3 Threat of New Entrants
- 4.6.4 Threat of Substitutes
- 4.6.5 Intensity of Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUES)
- 5.1 By Core
- 5.1.1 Single-core
- 5.1.2 Dual-core
- 5.1.3 Multi-core
- 5.2 By Product Type
- 5.2.1 General-purpose Stand-alone DSPs
- 5.2.2 Application-specific DSP (ASSP/ASIP)
- 5.2.3 Embedded DSP IP Cores
- 5.2.4 FPGA/SoC-based Hybrid DSPs
- 5.3 By Architecture
- 5.3.1 SIMD (Single Instruction Multiple Data)
- 5.3.2 VLIW (Very-long-instruction-word)
- 5.3.3 SIMT/Vector DSPs
- 5.3.4 MLIW and Novel Heterogeneous Designs
- 5.4 By Numeric Format
- 5.4.1 Fixed-point
- 5.4.2 Floating-point
- 5.4.3 Mixed/Adaptive Precision
- 5.5 By End-user Industry
- 5.5.1 Communication
- 5.5.1.1 Cellular Infrastructure (4G/5G, Open-RAN)
- 5.5.1.2 Data Center and Cloud Edge
- 5.5.1.3 VoIP and IP Video
- 5.5.2 Automotive
- 5.5.2.1 ADAS and Autonomous Driving
- 5.5.2.2 In-vehicle Infotainment
- 5.5.3 Consumer Electronics
- 5.5.3.1 Smartphones and Tablets
- 5.5.3.2 Hearables/Wearables
- 5.5.3.3 Smart TVs and STBs
- 5.5.4 Industrial
- 5.5.4.1 Motor Control and Drives
- 5.5.4.2 Machine Vision and Robotics
- 5.5.4.3 Smart Grid and Energy
- 5.5.5 Aerospace and Defense
- 5.5.5.1 Radar and EW Systems
- 5.5.5.2 Satellite and Space Electronics
- 5.5.6 Healthcare
- 5.5.6.1 Medical Imaging
- 5.5.6.2 Patient Monitoring and Diagnostics
- 5.5.1 Communication
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 Europe
- 5.6.2.1 Germany
- 5.6.2.2 United Kingdom
- 5.6.2.3 France
- 5.6.2.4 Italy
- 5.6.2.5 Spain
- 5.6.2.6 Rest of Europe
- 5.6.3 Asia-Pacific
- 5.6.3.1 China
- 5.6.3.2 Japan
- 5.6.3.3 South Korea
- 5.6.3.4 India
- 5.6.3.5 South East Asia
- 5.6.3.6 Australia
- 5.6.3.7 Rest of Asia-Pacific
- 5.6.4 South America
- 5.6.4.1 Brazil
- 5.6.4.2 Rest of South America
- 5.6.5 Middle East and Africa
- 5.6.5.1 Middle East
- 5.6.5.1.1 United Arab Emirates
- 5.6.5.1.2 Saudi Arabia
- 5.6.5.1.3 Rest of Middle East
- 5.6.5.2 Africa
- 5.6.5.2.1 South Africa
- 5.6.5.2.2 Rest of Africa
- 5.6.5.1 Middle East
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles {(includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products and Services, and Recent Developments)}
- 6.4.1 Texas Instruments Inc.
- 6.4.2 Analog Devices Inc.
- 6.4.3 Qualcomm Technologies Inc.
- 6.4.4 Intel Corporation
- 6.4.5 NXP Semiconductors N.V.
- 6.4.6 STMicroelectronics N.V.
- 6.4.7 Infineon Technologies AG
- 6.4.8 Renesas Electronics Corp.
- 6.4.9 Xilinx Inc. (AMD)
- 6.4.10 Broadcom Inc.
- 6.4.11 Samsung Electronics Co. Ltd.
- 6.4.12 Toshiba Corp.
- 6.4.13 Cirrus Logic Inc.
- 6.4.14 MediaTek Inc.
- 6.4.15 HiSilicon Technologies Co. Ltd.
- 6.4.16 Marvell Technology Inc.
- 6.4.17 ARM Ltd. (DSP IP)
- 6.4.18 CEVA Inc.
- 6.4.19 Cadence Design Systems (Tensilica DSP)
- 6.4.20 Synopsys Inc. (ARC DSP)
- 6.4.21 ON Semiconductor Corp.
- 6.4.22 Silicon Labs Inc.
- 6.4.23 Realtek Semiconductor Corp.
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-space and Unmet-need Assessment

