PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2124895

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2124895
Sensors And Actuators - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the sensors and actuators market size is projected to be USD 19.98 billion in 2025, USD 21.89 billion in 2026, and reach USD 34.24 billion by 2031, growing at a CAGR of 9.36% from 2026 to 2031.
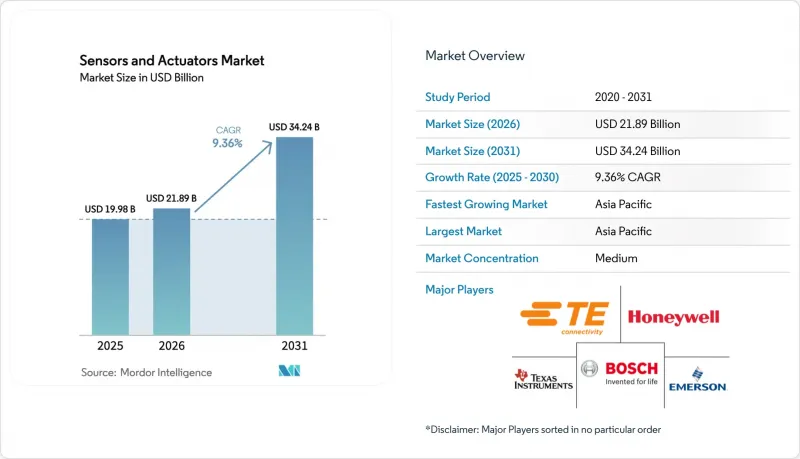
This report is Segmented by Product Type (Sensors, and Actuators), Technology (MEMS, and Non-MEMS), Connectivity (Wired, and Wireless), Output Signal (Digital, and Analog), End-User Industry (Automotive and Mobility, Industrial Automation and Robotics, Consumer Electronics and Wearables, Healthcare and Medical Devices, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global Sensors And Actuators Market Trends and Insights
Proliferation Of Low-Power MEMS Sensors Unlocking New IoT Use-Cases
Battery-sipping MEMS accelerometers, gyroscopes, and environmental sensors now operate for up to a decade on primary cells, enabling smart-city air-quality grids, agricultural soil-moisture probes, and cold-chain asset trackers. China shipped more than 800 million sub-10-microampere sensors in 2025, driven by municipal deployments, while Indian cities installed over 200,000 wireless leak-detection nodes the same year. New MEMS packages integrate vibration or thermal energy harvesters, lowering total cost of ownership by roughly one-third across a ten-year life cycle. These economics are shortening payback periods for public-sector and industrial buyers, sustaining double-digit unit growth.
Rapid Electrification And ADAS Integration In European Automotive Manufacturing
European vehicle platforms now contain 35-50 sensing nodes per car as OEMs migrate to Level 2-plus driver assistance and battery-electric powertrains. More than two-thirds of cars registered in Germany in 2025 featured adaptive cruise control and lane-keeping support, each requiring radar, ultrasonic, and optical image sensors. Component suppliers have inked multi-year contracts exceeding EUR 2 billion (USD 2.2 billion) for 77 GHz radar modules and high-dynamic-range CMOS imagers. Battery packs add dozens of current, voltage, and temperature sensors for thermal-runaway prevention, extending the sensor content and reinforcing demand for automotive-grade MEMS foundry capacity.
Rare-Earth Magnet Price Volatility Inflating Precision Actuator BOM Costs
Neodymium-iron-boron magnet prices climbed more than one-third between mid-2024 and early 2025 after export-quota cuts and mining disruptions. Magnetic actuator suppliers faced 12%-18% bill-of-materials inflation and saw gross margins compress by roughly 250 basis points. Alternate ferrite magnets reduce torque density, while switched-reluctance designs introduce complex control algorithms, limiting substitution. Smaller vendors without scale procurement contracts feel the squeeze most acutely as they cede share to vertically integrated multinationals.
Other drivers and restraints analyzed in the detailed report include:
- High Adoption Of Predictive-Maintenance Platforms Amplifying Smart Actuator Demand
- Hydrogen And CCUS Megaproject Investments Spurring Specialty Sensor Demand
- EU Data-Security Legislation Slowing Wireless Sensor-Network Adoption
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Chemical and bio-sensors are forecast to grow at a 10.40% CAGR through 2031, the quickest pace among product classes. They underpin glucose, lactate, and cortisol wearables and deliver rapid infectious-disease diagnostics, driving heightened procurement from hospitals and consumer-health brands. Pressure sensors still dominate volume in automotive tire-pressure monitoring, HVAC controllers, and process instrumentation, while temperature devices serve battery-management and cold-chain use cases. Electric actuators are increasingly preferred over pneumatic units for precise motion profiles, though hydraulics remain standard in heavy construction and aerospace flight controls.
Image sensors, particularly CMOS devices, serve automotive ADAS and industrial vision, with shipments rising in line with Level 2-plus automation. Flow and torque sensors cater to specialized medical ventilators and electric-vehicle powertrains, commanding premium pricing. Together these dynamics reinforce the sensors and actuators market as a multi-speed landscape where innovation clusters around miniaturization, multi-modal integration, and lifecycle cost reduction.
MEMS devices accounted for 68.43% of the sensors and actuators market share in 2025. Batch silicon fabrication lowers unit cost to under USD 2 while enabling co-packaged ASIC logic. Total shipments from a leading European supplier surpassed 4 billion units in 2025, buoyed by smartphone, wearable, and automotive orders. Conventional macroscale sensors still serve harsh environments such as gas turbines and subsea wells where MEMS reliability tapers, yet that niche is narrowing as hermetic wafer-level packaging broadens MEMS temperature and vibration envelopes.
Wireless networks amplify the appeal of MEMS parts because coin-cell batteries can power them for years, whereas conventional sensors often require wired feeds. Foundries in Taiwan and Japan committed more than USD 500 million to expand 8-inch MEMS lines in 2025, targeting automotive safety and industrial vibration applications. As packaging innovation advances, MEMS penetration should deepen across process-automation, aerospace, and medical devices, further enlarging the sensors and actuators market size.
Complete Report Scope:
- By Product Type
- Sensors
- Pressure Sensors
- Temperature Sensors
- Position Sensors
- Level Sensors
- Image Sensors
- Chemical/Bio-Sensors
- Torque Sensors
- Flow Sensors
- Actuators
- Hydraulic Actuators
- Pneumatic Actuators
- Electric Actuators
- Magnetic Actuators
- Mechanical Actuators
- Linear Actuators
- Rotary Actuators
- Sensors
- By Technology
- MEMS
- Non-MEMS / Conventional
- By Connectivity
- Wired
- Wireless
- By Output Signal
- Digital
- Analog
- By End-User Industry
- Automotive and Mobility
- Industrial Automation and Robotics
- Consumer Electronics and Wearables
- Healthcare and Medical Devices
- Oil, Gas and Energy
- Aerospace and Defense
- Building Automation and HVAC
- Utilities, Water and Waste-Water, Power
- Mining and Metals
- By Geography
- North America
- United States
- Canada
- Mexico
- South America
- Brazil
- Argentina
- Rest of South America
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia Pacific
- China
- Japan
- South Korea
- India
- Australia
- New Zealand
- Rest of Asia-Pacific
- Middle East and Africa
- Middle East
- United Arab Emirates
- Saudi Arabia
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Nigeria
- Kenya
- Rest of Africa
- Middle East
- North America
Geography Analysis
Asia-Pacific accounted for 37.38% of global revenue in 2025 and will grow at a 12.88% CAGR to 2031, fueled by China's 290,000 new robot installations, India's electronics mandates, and South Korea's industrial 5G networks. Japan's wafer-capacity additions are easing earlier MEMS shortages, while Australian miners deploy autonomous haulage systems laden with LiDAR and radar.
North America ranks second as predictive-maintenance adoption climbs in refineries and discrete manufacturing. U.S. factories integrate edge-AI gateways that crunch vibration and temperature streams, while Canadian oil-sands producers retrofit high-temp sensors into SAGD wells. Mexican automotive plants add pressure and inertial sensors as near-shoring accelerates electric-vehicle production.
Europe advances sensor content through electrified drivetrains and Level 2-plus ADAS, but wireless rollouts in critical infrastructure have slowed under NIS2 cyber-security rules. The Middle East prioritizes hydrogen pipelines and carbon-capture megaprojects that need specialty instrumentation. South American mines in Brazil and Chile automate fleets with ruggedized sensory suites, and African utilities gradually adopt water-quality and air-quality nodes as infrastructure spending ticks upward.
- TE Connectivity
- Honeywell International Inc.
- Bosch Sensortec GmbH
- Emerson Electric Co.
- Texas Instruments Incorporated
- Schneider Electric SE
- Siemens AG
- SMC Corporation
- Parker-Hannifin Corporation
- Renesas Electronics Corporation
- Infineon Technologies AG
- ABB Ltd.
- Rockwell Automation Inc.
- NXP Semiconductors N.V.
- Denso Corporation
- Analog Devices Inc.
- Flowserve Corporation
- Schlumberger Limited
- Balluff GmbH
- OMRON Corporation
- STMicroelectronics N.V.
- KYOCERA AVX Components
- Festo SE and Co. KG
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 INTRODUCTION
- 1.1 Study Assumptions and Market Definition
- 1.2 Scope of the Study
2 RESEARCH METHODOLOGY
3 EXECUTIVE SUMMARY
4 MARKET LANDSCAPE
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Proliferation of Low-Power MEMS Sensors Unlocking New IoT Use-Cases Across Asia
- 4.2.2 Rapid Electrification and ADAS Integration in European Automotive Manufacturing
- 4.2.3 High Adoption of Predictive-Maintenance Platforms Amplifying Smart Actuator Demand in North America
- 4.2.4 Hydrogen and CCUS Megaproject Investments Spurring Specialty Sensor Demand in Middle East Oil and Gas
- 4.2.5 Accelerated 5G and Edge-AI Roll-outs Elevating Industrial Sensor Uptake in South Korea and Taiwan
- 4.2.6 Surge in Wearable Health-Monitoring Devices Requiring Miniature Multi-Modal Sensors in the United States
- 4.3 Market Restraints
- 4.3.1 Rare-Earth Magnet Price Volatility Inflating Precision Actuator BOM Costs
- 4.3.2 EU Data-Security Legislation Slowing Wireless Sensor-Network Adoption
- 4.3.3 High Calibration Complexity of Multi-Axis Sensors Hindering SME Uptake
- 4.3.4 Semiconductor Wafer Shortages Curtailing MEMS Sensor Supply in Japan
- 4.4 Industry Value-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Bargaining Power of Buyers
- 4.7.2 Bargaining Power of Suppliers
- 4.7.3 Threat of New Entrants
- 4.7.4 Threat of Substitutes
- 4.7.5 Competitive Rivalry
5 MARKET SIZE AND GROWTH FORECASTS (VALUE)
- 5.1 By Product Type
- 5.1.1 Sensors
- 5.1.1.1 Pressure Sensors
- 5.1.1.2 Temperature Sensors
- 5.1.1.3 Position Sensors
- 5.1.1.4 Level Sensors
- 5.1.1.5 Image Sensors
- 5.1.1.6 Chemical/Bio-Sensors
- 5.1.1.7 Torque Sensors
- 5.1.1.8 Flow Sensors
- 5.1.2 Actuators
- 5.1.2.1 Hydraulic Actuators
- 5.1.2.2 Pneumatic Actuators
- 5.1.2.3 Electric Actuators
- 5.1.2.4 Magnetic Actuators
- 5.1.2.5 Mechanical Actuators
- 5.1.2.6 Linear Actuators
- 5.1.2.7 Rotary Actuators
- 5.1.1 Sensors
- 5.2 By Technology
- 5.2.1 MEMS
- 5.2.2 Non-MEMS / Conventional
- 5.3 By Connectivity
- 5.3.1 Wired
- 5.3.2 Wireless
- 5.4 By Output Signal
- 5.4.1 Digital
- 5.4.2 Analog
- 5.5 By End-User Industry
- 5.5.1 Automotive and Mobility
- 5.5.2 Industrial Automation and Robotics
- 5.5.3 Consumer Electronics and Wearables
- 5.5.4 Healthcare and Medical Devices
- 5.5.5 Oil, Gas and Energy
- 5.5.6 Aerospace and Defense
- 5.5.7 Building Automation and HVAC
- 5.5.8 Utilities, Water and Waste-Water, Power
- 5.5.9 Mining and Metals
- 5.6 By Geography
- 5.6.1 North America
- 5.6.1.1 United States
- 5.6.1.2 Canada
- 5.6.1.3 Mexico
- 5.6.2 South America
- 5.6.2.1 Brazil
- 5.6.2.2 Argentina
- 5.6.2.3 Rest of South America
- 5.6.3 Europe
- 5.6.3.1 Germany
- 5.6.3.2 United Kingdom
- 5.6.3.3 France
- 5.6.3.4 Italy
- 5.6.3.5 Spain
- 5.6.3.6 Rest of Europe
- 5.6.4 Asia Pacific
- 5.6.4.1 China
- 5.6.4.2 Japan
- 5.6.4.3 South Korea
- 5.6.4.4 India
- 5.6.4.5 Australia
- 5.6.4.6 New Zealand
- 5.6.4.7 Rest of Asia-Pacific
- 5.6.5 Middle East and Africa
- 5.6.5.1 Middle East
- 5.6.5.1.1 United Arab Emirates
- 5.6.5.1.2 Saudi Arabia
- 5.6.5.1.3 Turkey
- 5.6.5.1.4 Rest of Middle East
- 5.6.5.2 Africa
- 5.6.5.2.1 South Africa
- 5.6.5.2.2 Nigeria
- 5.6.5.2.3 Kenya
- 5.6.5.2.4 Rest of Africa
- 5.6.5.1 Middle East
- 5.6.1 North America
6 COMPETITIVE LANDSCAPE
- 6.1 Market Concentration
- 6.2 Strategic Moves
- 6.3 Market Share Analysis
- 6.4 Company Profiles (includes Global Level Overview, Market Level Overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share, Products and Services, Recent Developments)
- 6.4.1 TE Connectivity
- 6.4.2 Honeywell International Inc.
- 6.4.3 Bosch Sensortec GmbH
- 6.4.4 Emerson Electric Co.
- 6.4.5 Texas Instruments Incorporated
- 6.4.6 Schneider Electric SE
- 6.4.7 Siemens AG
- 6.4.8 SMC Corporation
- 6.4.9 Parker-Hannifin Corporation
- 6.4.10 Renesas Electronics Corporation
- 6.4.11 Infineon Technologies AG
- 6.4.12 ABB Ltd.
- 6.4.13 Rockwell Automation Inc.
- 6.4.14 NXP Semiconductors N.V.
- 6.4.15 Denso Corporation
- 6.4.16 Analog Devices Inc.
- 6.4.17 Flowserve Corporation
- 6.4.18 Schlumberger Limited
- 6.4.19 Balluff GmbH
- 6.4.20 OMRON Corporation
- 6.4.21 STMicroelectronics N.V.
- 6.4.22 KYOCERA AVX Components
- 6.4.23 Festo SE and Co. KG
7 MARKET OPPORTUNITIES AND FUTURE OUTLOOK
- 7.1 White-Space and Unmet-Need Assessment

