PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2124945

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2124945
Virology Testing - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, the virology testing market size is expected to increase from USD 12.52 billion in 2025 to USD 13.25 billion in 2026 and reach USD 17.56 billion by 2031, growing at a CAGR of 5.79% over 2026-2031.
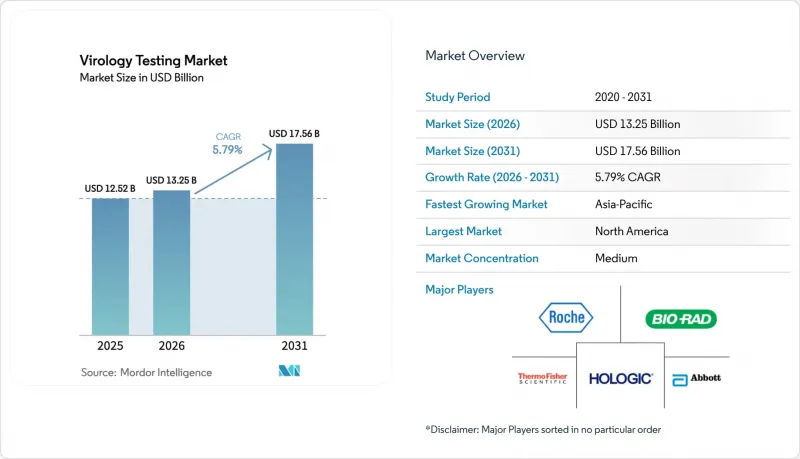
This report is Segmented by Type (Instruments, Assay Kits & Consumables), Diagnostic Technique (Molecular Diagnostics Method, and More), Testing Setting (Centralized Laboratories, and More), End User (Hospitals and Clinics, Diagnostic Laboratories, and More), and Geography (North America, Europe, Asia-Pacific, Middle East and Africa, South America). The Market Forecasts are Provided in Terms of Value (USD).
Global Virology Testing Market Trends and Insights
Rising Prevalence of Viral Diseases
Outbreaks such as 61 U.S. human H5N1 cases in 2024-2025 pressed state labs to expand PCR capacity. Mpox clade Ib detections in Central Africa triggered WHO emergency declarations that accelerated real-time PCR rollouts. Chronic programs, for example Egypt's hepatitis C elimination effort, maintain repeat viral-load testing. These parallel clinical and public-health needs sustain demand for flexible multiplex systems that accept new targets without hardware replacement. Dense populations and expanding access in Asia-Pacific and sub-Saharan Africa amplify volume growth, underpinning the 1.2 percentage-point lift in the global CAGR.
Growing Regulatory Clearances for Novel Assays
The FDA's breakthrough-device pathway shortened review cycles, exemplified by QIAGEN's QIAstat-Dx Rise, cleared in September 2025 after an expedited process. Europe's IVDR, despite deadline extensions, is consolidating suppliers as smaller firms exit rather than absorb high conformity costs. Harmonized guidelines from the International Medical Device Regulators Forum encourage simultaneous submissions, accelerating global launches and adding 0.9 percentage points to the CAGR in developed markets.
Stringent Product-Approval Regulations
IVDR compliance costs can top EUR 500,000 per device family, and notified-body capacity is limited to 30 organizations, creating year-long approval queues. India adopted local-validation rules in 2024, adding further complexity. Smaller assay makers are leaving the EU, narrowing menu variety and shaving 0.5 percentage points off CAGR during the transition.
Other drivers and restraints analyzed in the detailed report include:
- Rapid Adoption of Molecular POC PCR Platforms
- Expansion of Wastewater-Based Viral Surveillance
- Reimbursement & Pricing Reforms in Key Markets
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
Instruments will climb at a 6.76% pace to 2031, outstripping the overall virology testing market. Hospitals are buying integrated PCR workcells such as Roche's cobas 5800 to overcome staffing gaps and compress turnaround. Consumables still generated 62.46% of 2025 revenue, anchoring the virology testing market size with recurring sales. Instruments, however, carry 50%-60% gross margins and deliver service-contract annuities, fostering vendor lock-in. Public-sector budget caps in Europe temper adoption, but automation imperatives keep the sub-segment on a faster trajectory.
Consumables will continue to dominate revenue through 2031 as wastewater programs and chronic-disease monitoring lift test volumes. Even so, capital budgets are prioritizing multi-panel PCR systems that accept respiratory, STI and bloodborne targets on a single chassis, keeping instrument growth lively. Validation costs and staff-training hurdles create switching friction that benefits established vendors.
Molecular methods captured 49.26% of 2025 dollars and will advance at a 6.67% clip, steering the virology testing market share toward higher-complexity assays. PCR remains the backbone, bolstered by CLIA-waived cartridges like Xpert Bordetella pertussis.
Falling sequencing costs-USD 200-300 per sample on Illumina's NextSeq 1000/2000-are making NGS surveillance feasible for routine outbreak response. Immunoassays lose ground as molecular platforms match turnaround speed at declining prices. Mass-spectrometry stays niche for viral work, and culture techniques remain isolated to reference labs.
Complete Report Scope:
- By Type
- Instruments
- Assay Kits & Consumables
- By Diagnostic Technique
- Molecular Diagnostics Method
- PCR-based Methods
- NGS-based Methods
- Immunoassay-based Method
- Mass-Spectrometry-based Method
- Others
- Molecular Diagnostics Method
- By Testing Setting
- Centralized Laboratories
- Point-of-Care Testing
- At-Home and Self-Testing
- By End User
- Hospitals and Clinics
- Diagnostic Laboratories
- Public Health and Surveillance Agencies
- Others
- By Geography
- North America
- United States
- Canada
- Mexico
- Europe
- Germany
- United Kingdom
- France
- Italy
- Spain
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- Australia
- South Korea
- Rest of Asia-Pacific
- Middle East and Africa
- GCC
- South Africa
- Rest of Middle East and Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
Asia-Pacific's rapid infrastructure spend and infectious-disease burden position the region for the fastest ascent, even as North America continues to supply 40.23% of 2025 sales. China's domestic firms leverage lower pricing to win tenders, while India deploys 1,000 district-level PCR labs by 2027. Australia's nationwide wastewater network exemplifies policy-driven demand outside clinical cycles.
Europe, holding roughly one-quarter of 2025 revenue, is constrained by IVDR compliance costs that push smaller vendors out, narrowing instrument menus but solidifying demand for big-platform replacements. Bulk-purchase price deals in Germany and France hold down ASPs.
Middle East and Africa expand regional hubs to meet fast-response regulations, yet donor-funding cuts threaten sub-Saharan HIV testing continuity. South America adds capacity via public-private deals, but foreign-exchange swings hamper reagent imports, moderating growth.
- Abbott Laboratories
- Becton Dickinson & Co.
- bioMerieux
- Bio-Rad Laboratories
- Cepheid
- Danaher (Cepheid)
- Diasorin SpA
- Roche
- Fujirebio Diagnostics
- GenMark Diagnostics
- Hologic
- Illumina
- QIAGEN
- QuidelOrtho Corp.
- Revvity (PerkinElmer)
- Seegene
- Siemens Healthineers
- Thermo Fisher Scientific
- Trinity Biotech
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 Introduction
- 1.1 Study Assumptions & Market Definition
- 1.2 Scope of the Study
2 Research Methodology
3 Executive Summary
4 Market Landscape
- 4.1 Market Overview
- 4.2 Market Drivers
- 4.2.1 Rising prevalence of viral diseases
- 4.2.2 Growing regulatory clearances for novel assays
- 4.2.3 Rapid adoption of molecular POC PCR platforms
- 4.2.4 Expansion of wastewater-based viral surveillance
- 4.2.5 AI-driven automated laboratory workflows
- 4.2.6 Government stockpiling of multi-pathogen panels
- 4.3 Market Restraints
- 4.3.1 Stringent product-approval regulations
- 4.3.2 Reimbursement & pricing reforms in key markets
- 4.3.3 Donor-funding cuts disrupting LMIC HIV testing
- 4.3.4 Global shortage of skilled molecular technologists
- 4.4 Value / Supply-Chain Analysis
- 4.5 Regulatory Landscape
- 4.6 Technological Outlook
- 4.7 Porter's Five Forces Analysis
- 4.7.1 Threat of New Entrants
- 4.7.2 Bargaining Power of Buyers / Consumers
- 4.7.3 Bargaining Power of Suppliers
- 4.7.4 Threat of Substitute Products
- 4.7.5 Intensity of Competitive Rivalry
5 Market Size & Growth Forecasts (Value, USD)
- 5.1 By Type
- 5.1.1 Instruments
- 5.1.2 Assay Kits & Consumables
- 5.2 By Diagnostic Technique
- 5.2.1 Molecular Diagnostics Method
- 5.2.1.1 PCR-based Methods
- 5.2.1.2 NGS-based Methods
- 5.2.2 Immunoassay-based Method
- 5.2.3 Mass-Spectrometry-based Method
- 5.2.4 Others
- 5.2.1 Molecular Diagnostics Method
- 5.3 By Testing Setting
- 5.3.1 Centralized Laboratories
- 5.3.2 Point-of-Care Testing
- 5.3.3 At-Home and Self-Testing
- 5.4 By End User
- 5.4.1 Hospitals and Clinics
- 5.4.2 Diagnostic Laboratories
- 5.4.3 Public Health and Surveillance Agencies
- 5.4.4 Others
- 5.5 By Geography
- 5.5.1 North America
- 5.5.1.1 United States
- 5.5.1.2 Canada
- 5.5.1.3 Mexico
- 5.5.2 Europe
- 5.5.2.1 Germany
- 5.5.2.2 United Kingdom
- 5.5.2.3 France
- 5.5.2.4 Italy
- 5.5.2.5 Spain
- 5.5.2.6 Rest of Europe
- 5.5.3 Asia-Pacific
- 5.5.3.1 China
- 5.5.3.2 Japan
- 5.5.3.3 India
- 5.5.3.4 Australia
- 5.5.3.5 South Korea
- 5.5.3.6 Rest of Asia-Pacific
- 5.5.4 Middle East and Africa
- 5.5.4.1 GCC
- 5.5.4.2 South Africa
- 5.5.4.3 Rest of Middle East and Africa
- 5.5.5 South America
- 5.5.5.1 Brazil
- 5.5.5.2 Argentina
- 5.5.5.3 Rest of South America
- 5.5.1 North America
6 Competitive Landscape
- 6.1 Market Concentration
- 6.2 Market Share Analysis
- 6.3 Company Profiles (includes Global-level Overview, Market-level Overview, Core Segments, Financials, Strategic Info, Market Rank/Share, Products & Services, Recent Developments)
- 6.3.1 Abbott Laboratories
- 6.3.2 Becton Dickinson & Co.
- 6.3.3 bioMerieux SA
- 6.3.4 Bio-Rad Laboratories Inc.
- 6.3.5 Cepheid
- 6.3.6 Danaher (Cepheid)
- 6.3.7 Diasorin SpA
- 6.3.8 F. Hoffmann-La Roche AG
- 6.3.9 Fujirebio Diagnostics Inc.
- 6.3.10 GenMark Diagnostics
- 6.3.11 Hologic Inc.
- 6.3.12 Illumina Inc.
- 6.3.13 Qiagen
- 6.3.14 QuidelOrtho Corp.
- 6.3.15 Revvity (PerkinElmer)
- 6.3.16 Seegene Inc.
- 6.3.17 Siemens Healthineers
- 6.3.18 Thermo Fisher Scientific Inc.
- 6.3.19 Trinity Biotech
7 Market Opportunities & Future Outlook
- 7.1 White-space & Unmet-Need Assessment

