PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2124976

PUBLISHER: Mordor Intelligence | PRODUCT CODE: 2124976
3D IC Packaging - Market Share Analysis, Industry Trends & Statistics, Growth Forecasts (2026 - 2031)
According to Mordor Intelligence, 3D IC packaging market size in 2026 is estimated at USD 18.64 billion, growing from 2025 value of USD 16.22 billion with 2031 projections showing USD 37.41 billion, growing at 14.95% CAGR over 2026-2031.
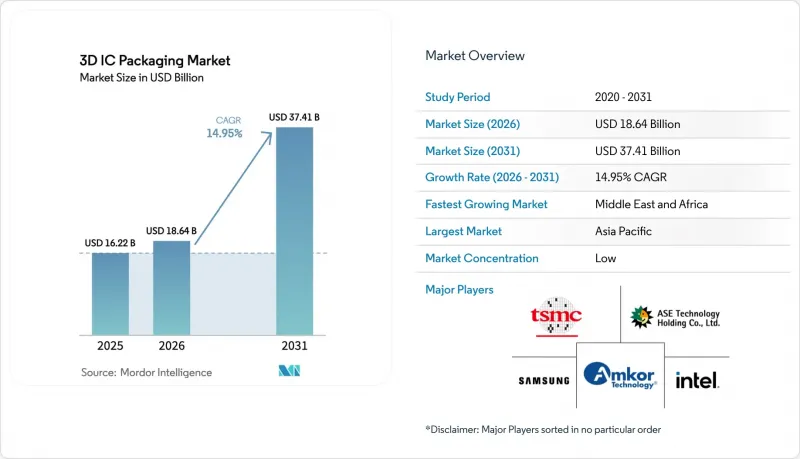
This report is Segmented by Packaging Technology (3D TSV, 3D WLCSP and More), Integration Approach (2. 5D Interposer, True 3D Stacking, and More), Device Type (Memory, Logic/Processor and More), End-User Application (HPC & AI, Consumer Electronics & Mobile, and More), and Geography. The Market Forecasts are Provided in Terms of Value (USD).
Global 3D IC Packaging Market Trends and Insights
Explosive AI / HPC Demand for HBM-Stacked Packages
A wave of data-center accelerators is reshaping bill-of-materials priorities, pushing HBM stacks inside the 3D IC packaging market to the top of every advanced-node roadmap. TSMC is scaling CoWoS output to 88,000 wafers per month by 2026 to keep pace with Nvidia's next-generation GPUs. The shift from HBM3E to HBM4+ triples effective bandwidth density while holding thermal design limits steady, forcing substrate makers to qualify thicker core materials and finer copper redistribution layers. Samsung's H-Cube platform couples' logic and memory on-package, illustrating how memory-centric topologies are cascading down to board-level architecture. The net effect is a higher stacked-die ratio per device, a richer TSV mix and, ultimately, an elevated ASP across the 3D IC packaging market.
Mobile and Wearables Shift to Wafer-Level Chip-Scale Packages (WLCSP)
Wearable and premium-smartphone OEMs now view wafer-level system-in-package footprints as the default path to squeezing radios, PMICs and MEMS into sub-7 mm platforms. Apple's 2026 flagship is widely expected to showcase advanced WLCSP for its A-series SoC, a signal that form-factor is trumping traditional cost-per-pin trade-offs. Taiwanese OSATs have responded by doubling lithography lines dedicated to redistributed-layer-count (RDL)-first flows, while South Korean rivals pivot toward resin-coated copper foils to mitigate warpage. These moves expand the 3D IC packaging market beyond data-center silicon and into everyday consumer devices, diversifying revenue streams and improving fab loading factors.
Scarcity of Production TSV Tools and CoWoS Capacity
TSV etchers, bonding aligners and CoWoS-grade substrate laminators remain booked 12-18 months out, constraining upside for OSATs scrambling to meet AI accelerator schedules. Applied Materials and Tokyo Electron both forecast double-digit equipment backlog into mid-2026, yet component shortages and install-crew bottlenecks slow actual ramp-ups. With TSMC commanding the lion's share of CoWoS substrates, buyers compete for wafer-start allocations, sometimes pre-paying quarters in advance. The scarcity curtails immediate revenue realization across the 3D IC packaging market even when demand signals are unmistakably strong.
Other drivers and restraints analyzed in the detailed report include:
- Foundry "Foundry 2.0" Strategy Integrating Packaging
- Glass-Core and Panel-Level Substrates Lowering Cost at Scale
- Defense-Grade Chiplets Mandate Secure Heterogeneous Integration
- Thermal-Design-Limit (TDL) Challenges Beyond 1 W/mm2
For complete list of drivers and restraints, kindly check the Table Of Contents.
Segment Analysis
3D TSV nodes retained 37.96% of the 3D IC packaging market share in 2025 because mature lithographic rules, bulk production tooling and field reliability data aligned with memory vendors' cost-per-GB targets. Multiple HBM3E lines already amortized their TSV drill and fill equipment, stabilizing gross margins even as die counts increased. Yet the hybrid-bond segment is expanding at a 21.15% CAGR, levering copper-to-copper direct contact to cut z-height by 40% and interconnect resistance by 15%. These electrical gains are pivotal in compute-dense AI accelerators that push beyond traditional package-substrate escape routing limits.
The pivot does not render TSV obsolete. Instead, dual-path roadmaps emerge: TSV remains the default for high-volume memory and sensor stacks, while hybrid bonding occupies compute-centric, low-latency corners of the 3D IC packaging market. OSATs able to host both flows on adjacent lines secure risk-diversified bookings. As substrate makers scale glass cores, hy-brid bonding alignment accuracy improves further, hinting at future cross-over where cost curves intersect and hybrid bonding usurps TSV in certain volume SKUs.
2.5D interposers booked 57.38% revenue in 2025, capitalizing on a decade of yield learning that brought silicon-interposer defectivity to <0.1 dpm. Because interposers decouple front-end node choice from back-end assembly, GPU vendors ship reticle-sized compute tiles beside older-node I/O dies without redesigning the full stack. However, true 3D stacking logs a 21.28% CAGR, fuelled by die-to-die latency gains that can cut model-training time by double-digit percentages. Flagship use cases include vertical NAND, near-memory compute lenses and in-package high-Q RF filters-all scenarios where z-axis proximity beats planar reticulation.
Early reliability fears-electro-migration in buried micro-bumps and thermo-mechanical shear at die corners-are being mitigated by low-modulus under-fills and hybrid-bond copper diffusion barriers. As micro-fluidic cooling and graphene heat-spreaders mature, true 3D adoption accelerates. The 3D IC packaging market therefore bifurcates into an interposer mainstream and a true-stacked performance edge, each advancing on differentiated KPI roadmaps rather than price alone.
Complete Report Scope:
- By Packaging Technology
- 3D TSV
- 3D Wafer-Level Chip-Scale Package (WLCSP)
- Hybrid-Bond Stacking (WoW, CoW, SoIC)
- Fan-Out 3D & Panel-Level Packaging (PLP)
- By Integration Approach
- 2.5D Interposer
- True 3D Stacking
- System-in-Package / Chiplet-based HI
- By Device Type
- Memory (HBM, Wide-I/O, HMC)
- Logic / Processor
- Sensor & MEMS
- RF & Analog
- By End-User Application
- High-Performance Computing & AI
- Consumer Electronics & Mobile
- Automotive & ADAS
- Aerospace & Defence
- Medical & Industrial IoT
- Geography
- North America
- United States
- Canada
- Mexico
- Europe
- United Kingdom
- Germany
- France
- Italy
- Rest of Europe
- Asia-Pacific
- China
- Japan
- India
- South Korea
- Rest of Asia
- Middle East
- Israel
- Saudi Arabia
- United Arab Emirates
- Turkey
- Rest of Middle East
- Africa
- South Africa
- Egypt
- Rest of Africa
- South America
- Brazil
- Argentina
- Rest of South America
- North America
Geography Analysis
Asia-Pacific commanded 62.41% of the 3D IC packaging market in 2025, a consequence of Taiwan's advanced-node hegemony, South Korea's memory-centric back-end clusters and mainland China's sprint toward domestic capacity. TSMC's CoWoS, Samsung's H-Cube and ASE's FOCoS platforms anchor dense supplier habitats, driving low logistics latency and fast process transfer loops. Even so, relocation risk under geopolitical crosscurrents pushes some customers to dual source into Malaysia, Singapore and Vietnam, lengthening the region's technology reach while marginally raising cost baselines.
North America benefits from USD-denominated CHIPS Act incentives that subsidize capex for both leading-edge wafers and advanced packaging lines. TSMC Arizona and Intel Ohio collectively exceed a projected 100,000 wafers per month of back-end capacity by 2028, a cushion against Asia-bound supply disruption. Proximity to Nvidia, AMD and a host of machine-learning start-ups tightens design-manufacturing feedback loops, granting North America disproportionate influence over the direction of the 3D IC packaging market even if absolute volume lags Asia.
The Middle East and Africa region posts the highest forecast CAGR at 19.06%, albeit from a small base. Sovereign-wealth-fund-backed fabs in the UAE and Saudi Arabia's Vision 2030 industrial zones earmark billions for glass-core substrate lines and OSAT pilot plants. Europe focuses on automotive reliability and green-manufacturing leadership, leveraging German power-electronic expertise and French photonics clusters. Latin America remains a niche assembly point for consumer devices, while Eastern Europe eyes defense-oriented secure-package initiatives. Together, these moves fragment capacity geographically, opening localized demand pockets inside the broader 3D IC packaging market.
- Taiwan Semiconductor Manufacturing Co. Ltd.
- Samsung Electronics Co., Ltd.
- Advanced Semiconductor Engineering Inc.
- Amkor Technology Inc.
- Intel Corporation
- Siliconware Precision Industries Co. Ltd.
- GlobalFoundries Inc.
- Invensas Corporation
- Powertech Technology Inc.
- United Microelectronics Corporation
- Jiangsu Changjiang Electronics Technology Co. Ltd.
- Tongfu Microelectronics Co. Ltd.
- STATS ChipPAC Pte Ltd.
- ChipMOS Technologies Inc.
- ASE Test Limited
- Kyocera Corporation
- Texas Instruments Incorporated
- Micron Technology Inc.
- SK hynix Inc.
- Lam Research Corporation
Additional Benefits:
- The market estimate (ME) sheet in Excel format
- 3 months of analyst support
TABLE OF CONTENTS
1 A
2 INTRODUCTION
- 2.1 Study Assumptions & Market Definition
- 2.2 Scope of the Study
3 RESEARCH METHODOLOGY
4 EXECUTIVE SUMMARY
5 MARKET LANDSCAPE
- 5.1 Market Overview
- 5.2 Market Drivers
- 5.2.1 Explosive AI / HPC demand for HBM-stacked packages
- 5.2.2 Mobile & wearables shift to Wafer-Level Chip-Scale Packages (WLCSP)
- 5.2.3 Foundry -Foundry 2.0- strategy integrating packaging (e.g., TSMC, Samsung)
- 5.2.4 Glass-core & panel-level substrates lowering cost at scale (under-the-radar)
- 5.2.5 Defense-grade chiplets mandate secure heterogeneous integration (under-the-radar)
- 5.2.6 Carbon-neutral fabs prioritising low-temperature hybrid bonding (under-the-radar)
- 5.3 Market Restraints
- 5.3.1 Scarcity of production TSV tools & CoWoS capacity
- 5.3.2 Thermal-design-limit (TDL) challenges beyond 1 W/mm-
- 5.3.3 High IP / EDA cost for 3D floor-planning (under-the-radar)
- 5.3.4 Panel warp & yield loss >3 % in early PLP lines (under-the-radar)
- 5.4 Value / Supply-Chain Analysis
- 5.5 Regulatory Landscape
- 5.6 Technological Outlook
- 5.7 Porter-s Five Forces
- 5.7.1 Threat of New Entrants
- 5.7.2 Bargaining Power of Buyers
- 5.7.3 Bargaining Power of Suppliers
- 5.7.4 Threat of Substitutes
- 5.7.5 Competitive Rivalry
- 5.8 Pricing Analysis
6 MARKET SIZE & GROWTH FORECASTS (VALUE, USD BN)
- 6.1 By Packaging Technology
- 6.1.1 3D TSV
- 6.1.2 3D Wafer-Level Chip-Scale Package (WLCSP)
- 6.1.3 Hybrid-Bond Stacking (WoW, CoW, SoIC)
- 6.1.4 Fan-Out 3D & Panel-Level Packaging (PLP)
- 6.2 By Integration Approach
- 6.2.1 2.5D Interposer
- 6.2.2 True 3D Stacking
- 6.2.3 System-in-Package / Chiplet-based HI
- 6.3 By Device Type
- 6.3.1 Memory (HBM, Wide-I/O, HMC)
- 6.3.2 Logic / Processor
- 6.3.3 Sensor & MEMS
- 6.3.4 RF & Analog
- 6.4 By End-User Application
- 6.4.1 High-Performance Computing & AI
- 6.4.2 Consumer Electronics & Mobile
- 6.4.3 Automotive & ADAS
- 6.4.4 Aerospace & Defence
- 6.4.5 Medical & Industrial IoT
- 6.5 Geography
- 6.5.1 North America
- 6.5.1.1 United States
- 6.5.1.2 Canada
- 6.5.1.3 Mexico
- 6.5.2 Europe
- 6.5.2.1 United Kingdom
- 6.5.2.2 Germany
- 6.5.2.3 France
- 6.5.2.4 Italy
- 6.5.2.5 Rest of Europe
- 6.5.3 Asia-Pacific
- 6.5.3.1 China
- 6.5.3.2 Japan
- 6.5.3.3 India
- 6.5.3.4 South Korea
- 6.5.3.5 Rest of Asia
- 6.5.4 Middle East
- 6.5.4.1 Israel
- 6.5.4.2 Saudi Arabia
- 6.5.4.3 United Arab Emirates
- 6.5.4.4 Turkey
- 6.5.4.5 Rest of Middle East
- 6.5.5 Africa
- 6.5.5.1 South Africa
- 6.5.5.2 Egypt
- 6.5.5.3 Rest of Africa
- 6.5.6 South America
- 6.5.6.1 Brazil
- 6.5.6.2 Argentina
- 6.5.6.3 Rest of South America
- 6.5.1 North America
7 COMPETITIVE LANDSCAPE
- 7.1 Market Concentration
- 7.2 Strategic Moves
- 7.3 Market Share Analysis
- 7.4 Company Profiles (includes Global level Overview, Market level overview, Core Segments, Financials as available, Strategic Information, Market Rank/Share for key companies, Products & Services, and Recent Developments)
- 7.4.1 Taiwan Semiconductor Manufacturing Co. Ltd.
- 7.4.2 Samsung Electronics Co., Ltd.
- 7.4.3 Advanced Semiconductor Engineering Inc.
- 7.4.4 Amkor Technology Inc.
- 7.4.5 Intel Corporation
- 7.4.6 Siliconware Precision Industries Co. Ltd.
- 7.4.7 GlobalFoundries Inc.
- 7.4.8 Invensas Corporation
- 7.4.9 Powertech Technology Inc.
- 7.4.10 United Microelectronics Corporation
- 7.4.11 Jiangsu Changjiang Electronics Technology Co. Ltd.
- 7.4.12 Tongfu Microelectronics Co. Ltd.
- 7.4.13 STATS ChipPAC Pte Ltd.
- 7.4.14 ChipMOS Technologies Inc.
- 7.4.15 ASE Test Limited
- 7.4.16 Kyocera Corporation
- 7.4.17 Texas Instruments Incorporated
- 7.4.18 Micron Technology Inc.
- 7.4.19 SK hynix Inc.
- 7.4.20 Lam Research Corporation
8 MARKET OPPORTUNITIES & FUTURE OUTLOOK
- 8.1 White-Space & Unmet-Need Assessment

